Stock in Focus: Is Utilitywise worth the risk?

Does limiting your investment to companies with high StockRanks mean you miss out on some profitable buying opportunities?
The answer to this is almost certainly yes. But I think it’s the wrong question.
The right question is whether the StockRank system can help you avoid bad investments. After all, you don’t need to invest in every good stock. It’s often much more profitable to simply avoid investing in bad stocks.
Utilitywise is a case in point. Is it an attractive investment at current levels? There are strong arguments on both sides, but a StockRank of just 30 suggests it may not be.
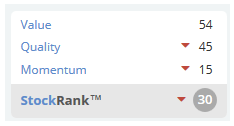
In this week’s column, I’m going to take a look at why Utilitywise scores comparatively poorly against Stockopedia’s StockRanks.
I’ll also look at the arguments in favour of this company. After all, with top fund manager Neil Woodford on the shareholder register holding a 26% stake, Utilitywise must have something in its favour.
What’s the big deal?
The controversy starts with the Utilitywise business model. The firm essentially acts as a bulk-buying middleman for business customers. It claims to be able to offer customers cheaper rates for utilities than if they go direct to the big energy and telecoms firms.
According to the firm’s website, it manages over 20TWh of power for more than 27,000 businesses across the UK. Utilitywise makes money by receiving commission payments from energy and water utilities, in return for providing them with new customers.
These commission payments have historically been generous enough for Utilitywise to generate operating margins of more than 20%. This gives rise to an obvious question. With such high profit margins, will the energy suppliers one day decide that they are paying companies such as Utilitywise too much for each new customer?
We don’t know. But in my opinion, there are several potential risks here:
- Utilitywise salespeople might find themselves in a position where they have to choose between maximising commission payments and maximising customer savings;
- Regulatory changes could result in a dramatic fall in commission payments;
- Utility companies might decide to spend more on marketing in-house and reduce payments to middlemen like Utilitywise.
All of these risks could one day result in a dramatic fall in the profitability of Utilitywise’s business model.
Is it cheap?
Does Utilitywise’s valuation reflect investor uncertainty about the firm’s long-term profitability? A ValueRank of 54 suggests not.
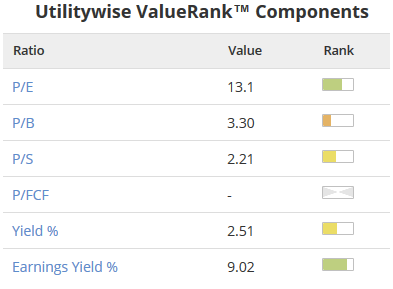
Although the trailing P/E of 13 and dividend yield of 2.5% are not outrageously expensive, they don’t scream value either.
The firm’s other ValueRank components are even less appealing. A price/book ratio of 3.3 is perhaps to be expected for an asset-light firm, but last year’s negative free cash flow and a price/sales ratio of 2.2 suggest to me that the firm’s revenues are already valued quite highly.
What about quality?
A QualityRank of 45 is probably not what you’d expect of a firm with consistently high profit margins and low debt levels.
However, it’s here that the potential problems start. The quality of Utilitywise’s earnings is hotly debated because the company appears to be very slow at converting accounting profits into cash flow.
Investors’ concerns revolve around the accrued revenue and trade and other receivables lines of Utilitywise’s balance sheet. These represent commission payments earned but not yet received by the company following new customer signups or contract extensions.
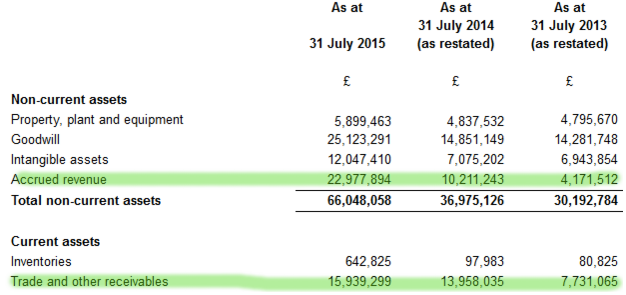
Last year, the firm’s pre-tax profit was £14.1m. Accrued revenue and trade and other receivables rose by £14.8m. This suggests that Utilitywise did not convert any of last year’s profits into cash.
This is very aggressive accounting, in my view. Accrued revenue is listed as a non-current asset, meaning that it is not expected to be received for more than one year. Despite this, Utilitywise recognises this revenue in its income statement each year.
The good news is that because Utilitywise’s customers are the big utilities, it’s very unlikely that any will default on their contractual commission payments to the firm. We’re not looking at a Quindell situation here, although commission payments can be reduced if end-users default or use less energy than expected.
It’s interesting and impressive to see that these risks are picked up by Stockopedia’s algorithms and reflected in Utilitywise’s QualityRank:
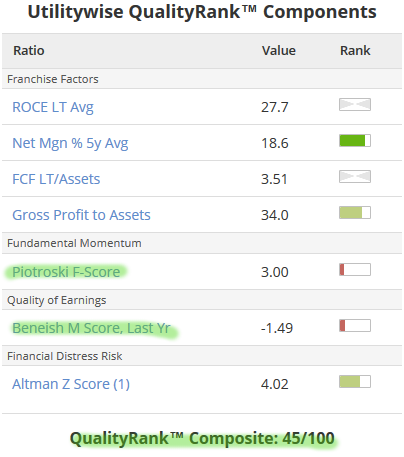
The low Piotroski F-Score of 3/9 is the biggest red flag and is the main reason why Utilitywise qualifies for the James Montier ‘Unholy Trinity’ short-selling screen.
Here’s how the F-score breaks down:
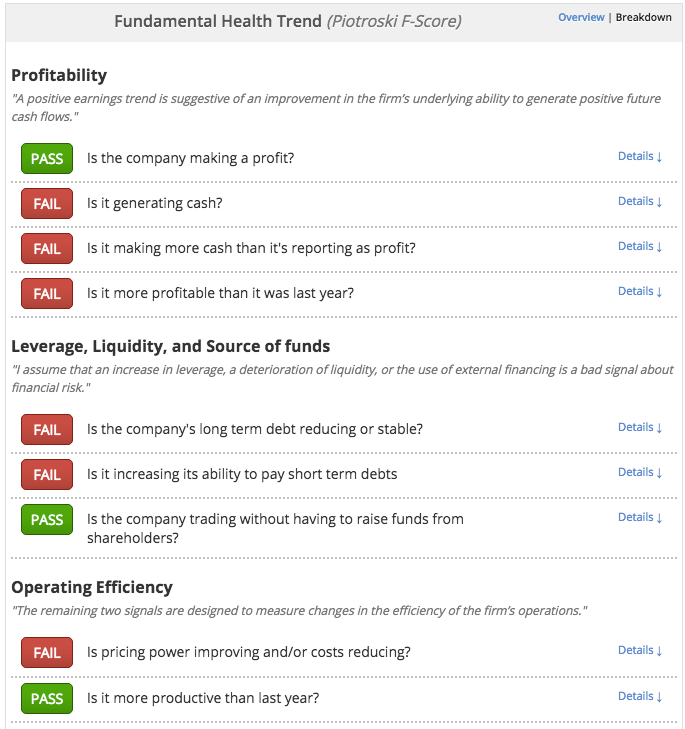
Utilitywise is not generating cash, and profits are much higher than cash flow. The firm’s operating cash flow was actually negative last year, pushing the firm into net debt for the first time.
Profit margins have been falling. A lack of free cash flow means the company’s ability to service current liabilities is deteriorating. The current ratio fell from 1.65 to 1.25 last year. That’s barely adequate, in my view.
However, there are some signs that things could be improving.
A turning point?
At the time of writing, Utilitywise has a MomentumRank of just 15.
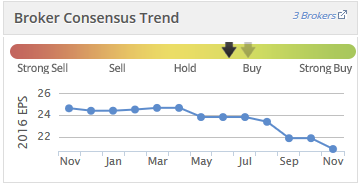
Price momentum is poor and earnings forecasts have been downgraded steadily since April. I don’t think Utilitywise is a momentum buy.
However, alongside the firm’s recent results was a second announcement, which could be significant. Utilitywise has renegotiated its contract with one energy supplier to bring forward commission payments on contract extensions.
The renegotiated contract terms are being applied to historic commissions, too, and the new deal resulted in the firm recently receiving a £3.6m cash payment. Utilitywise says that it is hoping to modify its contract terms with other utility suppliers too. If so, the firm’s cash flow profile could improve dramatically.
In turn, this would reduce accrued revenue and improve the quality of the firm’s profits.
This could well justify a modest re-rating of the group’s share price and could be one reason why Neil Woodford’s fund owns a 26% stake in Utilitywise. Mr Woodford has publicly stated that he is confident the firm’s numbers are okay.
If you believe this version of the story then Utilitywise could be a buy. The shares trade on a 2015 forecast P/E of just 9.5 and offer a 3.6% forecast yield, backed by four years of consistent dividend growth.
Personally, I’m not keen. Utilitywise could be a profitable buy, but there are other equally attractive stocks that don’t carry such risks. I’d rather invest elsewhere.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

19 comments
Thanks for an interesting and well put-together article Roland. Note I posted the following on Paul Scott's Small-Cap Value Report blog on 28th Oct:
Re: UTW note there are several very negative employee and former-employee reviews of UTW on the internet if you dig around for them, such as those at http://bloodinthestreets.weebly.com/stock-ideas/november-16th-2014 . Obviously, I am in no position to verify the claims of a few of the current and former employees, but their claims are serious.
I have no position in UTW.
Regards,
Ed
- See more at: http://www.stockopedia.com/content/small-cap-value-report-28-oct-2015-gbo-utw-pos-109896/?page=1#comments
Hi
Just to confirm, I sold my position in utilitywise a few days ago, and tweeted it at the time.
I can see merit in both the bull and bear cases, so I am currently neutral on the stock.
It's a bit of a special situation, so doesn't really lend itself particularly well to conventional analysis.
Regards, Paul.
UTW is presenting at Proactive do next week in London - chance to quiz them
Thanks Paul, I've updated the article accordingly to avoid any confusion, as it was published just after your trade.
I must have missed that tweet.
Regards, Roland
Yes it does seem like aggressive accounting but presumably it is strictly speaking correct. After all, apart from some adjustment due to leakage, the majority of the accrued revenue is virtually in the bag and will be paid at some point.
One of my concerns was why the accrued revenue had risen so much, from £10.2m to £22.9m.
There's also trade and other receivables of £15.9m under current assets. I'm making a wild guess here that this is mostly also accrued revenue, the only difference being it's payable within one year.
Adding the two figures together you get £39m which represents 56% of revenue compared to 49% last year. So up a bit but not a huge leap.
Presumably websites like the one below could pose a serious threat to UTW's business model?
https://openenergymarket.com/#the-future
"TRADE DIRECTLY WITH ALL UK SUPPLIERS WITHOUT THE NEED FOR A BROKER"
UTW's biggest single challenge is the proposed Code of Practice. They claim to have circa 27,000 "active" customers. The question is, how many new customers did they sign-up in the last financial year? It's probably certainly not 27k. Look at their revenue figures. Even if their newly-acquired customer number was 20,000 rather than 27,000, then that gives an AOV of circa £3,500 based on last year's numbers. The reality is that they are making an absolute "killing" by applying ludicrous (morally questionable) up-lifts on the contracts they place.
The UTW business model is flaky, at best, but they do operate in an unregulated market so the short-term opportunity remains strong.
Unless I am reading it wrongly, the prior year adjustment appears to have had a significant impact on these accounts, its effect having been to take around £3.9m out of the turnover and pre-tax profits of 2013 and put £0.3m of that in 2014 and £3.6m of it in 2015. Without it the earnings for 2015 would have been around £3m less on an after tax basis which equates to eps of around 4p less. Also, these are significant amounts to have taken out of 2013 where turnover and pre-tax profit were £25.5m and £6.2m respectively.
@achenaton,
My understanding of the prior year adjustment is slightly different to yours! What the firm says has happened is that that through accounting error, accrued revenue and trade and other receivables have been overstated in previous years.
As I understand it, the problem was basically that the Utilitywise (LON:UTW) made insufficient provision for "consumption variance" -- customers using less gas/electricty than expected, thus reducing the commission to which UTW was entitled. The firm was also releasing this provision too soon (i.e. before the end of the relevant contract).
The result is that £3.6m was subtracted from 2014 accrued revenue and trade and other receivables, and £3.9m was subtracted from the 2013 figures:
Unless I'm missing something, this restatement does not affect this year's results. I don't think revenue has been taken from previous years and added to this year. This is how the changes are described in the latest results:
Regards,
Roland
Roland,
Thanks for your reply. However, I still think my assessment is correct.
From the accounts:
2013 restated retained earnings were £2.993m lower. 2013 restated post tax profit was also £2.993m lower.
2014 restated retained earnings were £2.756m lower. However, 2014 restated post tax profit was only £0.237m lower (i.e. 2.993 - 2.756).
Therefore, the balance of £2.756m (2.993 - 0.237) must be included within 2015 post tax profit for the year.
In short, the amount by which retained earnings at 1/8/2014 were reduced (by £2.756m) must by its nature have correspondingly increased the earnings for 2015 (and we are told that the under-provision issue does not extend beyond 31/7/2015).
Regards
achenaton,
Thanks for taking the time to follow up on this. Having looked at the figures again, I may be wrong, although I am still not 100% certain I've understood these adjustments correctly.
I originally viewed these adjustments as an impairment of previously accrued revenue, on the grounds that the usage estimates were too high. Hence I was reading it as 'lost' revenue. But the other element is the provisions which were released too early.
It seems as though the provisions may outweigh the incorrect consumption variance estimates, so there's a net gain in 2014 and 2015 profit and perhaps in future years. We don't know how long UTW's contracts are.
2014 restated post-tax profit is £237k higher (not lower), as some of the 2013 adjustment was added back in -- presumably this represents provisions that should have been released in 2014, not 2013.
Utilitywise does not make any mention of the effect of the adjustments on 2015 profits. This is frustrating, since as you point out, it's potentially quite significant. However, I'm not sure that all of the £2.756m has necessarily been added back into 2015 profits.
My reading of the accounting notes is that UTW has corrected its accounting as of 2015 and that there are no issues with any live contracts. Continuing to (correctly) release provisions in 2015 and later years wouldn't be an adjustment, just business as usual (I think?), so wouldn't need disclosure.
If anyone else has a view on this I'd be very interested, so please leave a comment below.
One thing I am sure of is that 2013 profits received a very serious boost as a result of this error. Restated 2013 net profit is just £1.8m, or about 2.6p per share, versus 7.1p reported in 2013...
Regards,
Roland
Excellent article, and definitely worthy of a thumbs-up. Your posts have been consistently high in quality. Keep up the good work!
I think Paul announced somewhere (ADVFN/Twitter) that he is now out of UTW, BTW.
I notice that the trends in operating margins has been down since 2011. it will be very interesting to see their next set of numbers. They are taking on more staff, but those staff don't seem to be as profitable for the company, so maybe the trend will continue. I'm not sure how the up-front payments will factor into the equation, though.
As you say, the Piotroski score is quite low, and seems to indicate that things may be unravelling.
Perhaps we need an extra word of warning about high StockRanks, though. Plenty of frauds seem to have high SRs until they're found out. Wasn't Globo (LON:GBO) a high-scorer, for example? Probably QPP at some point, too.
One important point regarding how UTW is remunerated. The 'commission' which the Energy Suppliers pay them is ultimately paid by the end-user, as Utilitywise applies an up-lift to each Client's new rates and this is their commission (margin). Therefore, there is no cost of acquisition for the Energy Suppliers.
@Big Ralph,
Thanks, I didn't know this and I wouldn't have expected it, but apparently it is possible:
http://www.tpicodeofpractice.co.uk/the-code-of-practice/ (see point 12)
If UTW does this, then in my view it increases the risks associated with the Utilitywise (LON:UTW) business model. Such payments could come under competitive pressure or even be outlawed by the regulator in the future. On the other hand, generating commissions through uplift would explain why at least one of UTW's suppliers is willing to improve its payment terms -- it's a relatively small price to pay to keep the supply of new business coming.
Thanks for flagging this up.
Regards,
Roland
Yes, that would seem to explain a lot.
Another factor to add into the pot is that as part of that, UTW seem to need to extend the tie-up period with the customer.
So, if I'm understanding this correctly, there seems to be a trade-off between giving end-users fairly flexible terms, but not generating much cashflow, or trying to tie them up, which end-users may find unpalatable.
I'll be honest, too, I think UTW have something of a whiff of being bottom-feeders about them. It's like those sales calls you get when someone says you can save money on your internet bill, and such-like.
Sorry - "But I think it’s the wrong question." - what is the question ?
At the top .....,Does limiting your investments to companies with a high StockRank.......'
Question: "Does limiting your investment to companies with high StockRanks mean you miss out on some profitable buying opportunities?"
I thought that was the wrong question. You were asked by LLG what the right question is surely?
NI