Stock in Focus: Severfield promises growth despite UK slowdown

One of the joys of running my screen-based Stock in Focus fund over the last 3.5 years is that it’s (mostly) forced me to set aside my prejudices and macro views. I’ve repeatedly bought stocks which the discretionary investor in me wouldn’t have bought. Quite often, I’ve been rewarded with a profit.
This week is a good example. Having ditched the defensive safety of supermarket giant Tesco last week, I’m now preparing to consider the attractions of structural steel small cap Severfield (LON: SFR).
I’ve gained a positive impression of this company over the last few years, but from a cyclical viewpoint I don’t see it as an obvious choice at the moment.
However, this popular stock qualifies for my screen and is potentially eligible for the SIF fund. This week I’m going to take a closer look at this company, which Stockopedia’s algorithms rate very highly:
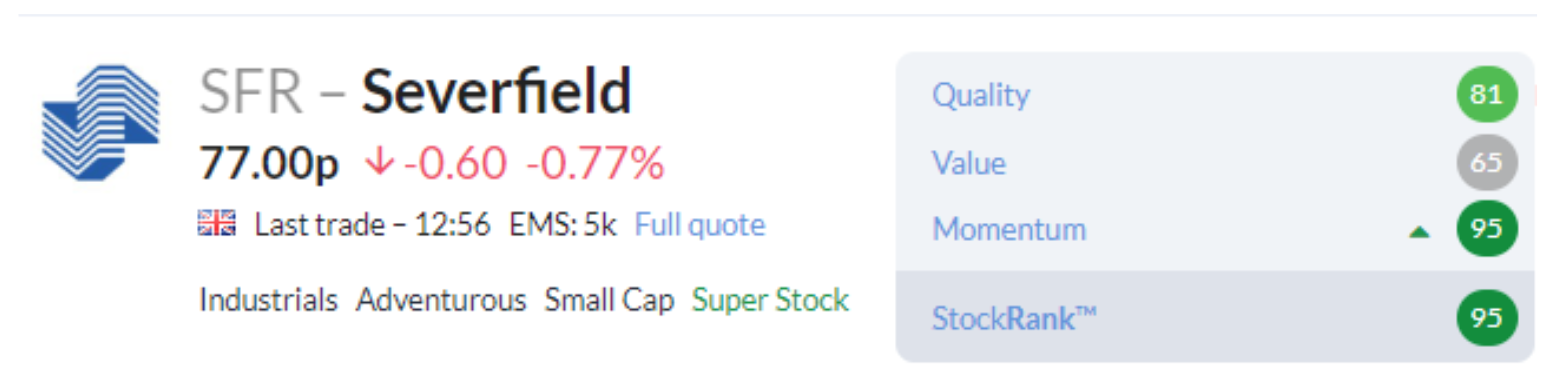
As usual, I’ll look at Severfield’s quality, value and momentum scores. But first, I think it’s worth taking a look at the firm’s latest trading update. I also want to consider an acquisition which appears to have had a significant impact on broker forecasts.
Trading update warns of H2 weighting
In early September, Severfield issued an AGM trading update confirming that the outlook for the year ending 31 March 2020 remained unchanged. The order book stood at £301m, up slightly from £295m at the start of June.
Management commentary seemed bullish but the update contained one sentence which will strike fear into the hearts of many small cap investors:
“Results for the 2020 financial year are expected to be significantly more second half weighted”
As Paul and Graham often comment, guidance for a second-half weighting is often an early sign that a profit warning is likely.
Checking back to June’s full-year results, I see that the company reported softer UK orders, project delays and difficulties closing sales last year:
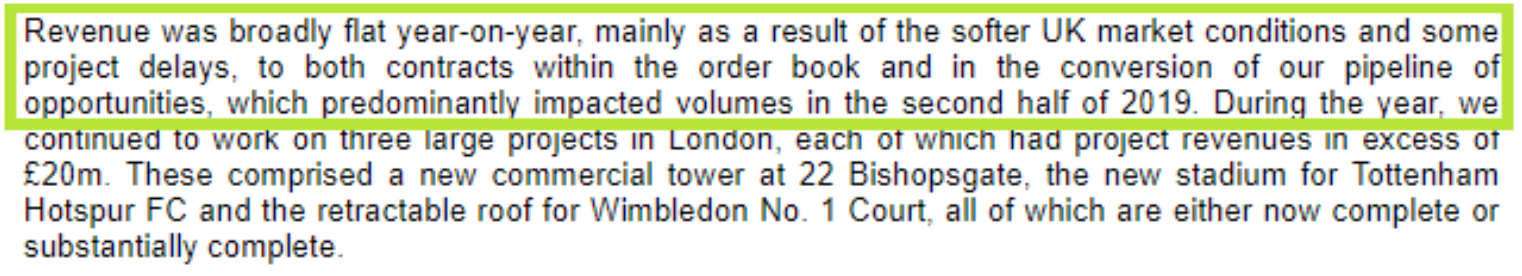
The results didn’t mention a second-half weighting, even though September’s trading update claims that this was “as anticipated”.
In the interests of balance, I should point out that there is a plausible explanation for this year’s expected H2 weighting. A recent (paid) broker note on Research Tree notes that an H2 bias to profits is a logical consequence of a strong (£65m) order intake during the second half of last year.
Understanding the order book: The hypothesis put forward by Severfield’s paid broker makes sense when you understand that the majority of orders are completed within 12 months:
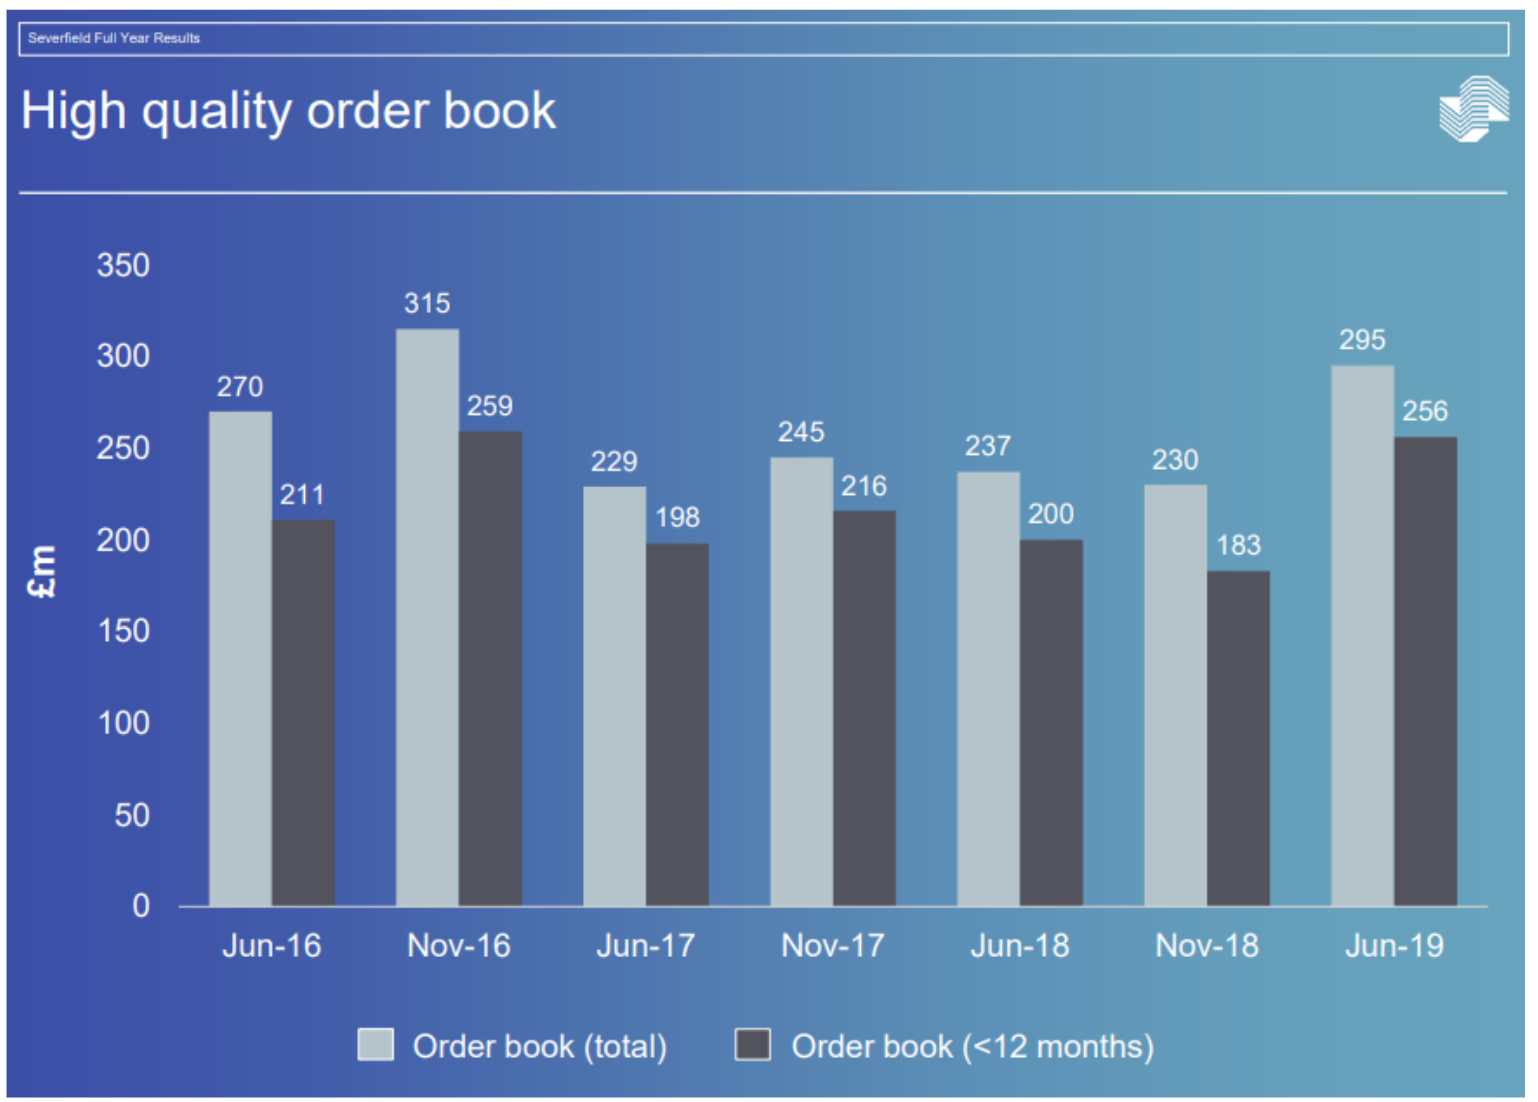
Severfield FY19 results presentation
Limited visibility: However, despite this impressive growth, it seems to me that the prompt conversion of orders to completed sales means that Severfield’s order book does not provide much forward visibility. The slide above shows that the order book fell by 27% in six months following the November 2016 referendum. Shareholders had very little warning that this was likely.
The presentation above also reveals that the proportion of Europe/RoI orders rose from 1% in November 2018 to 37% in June 2019:
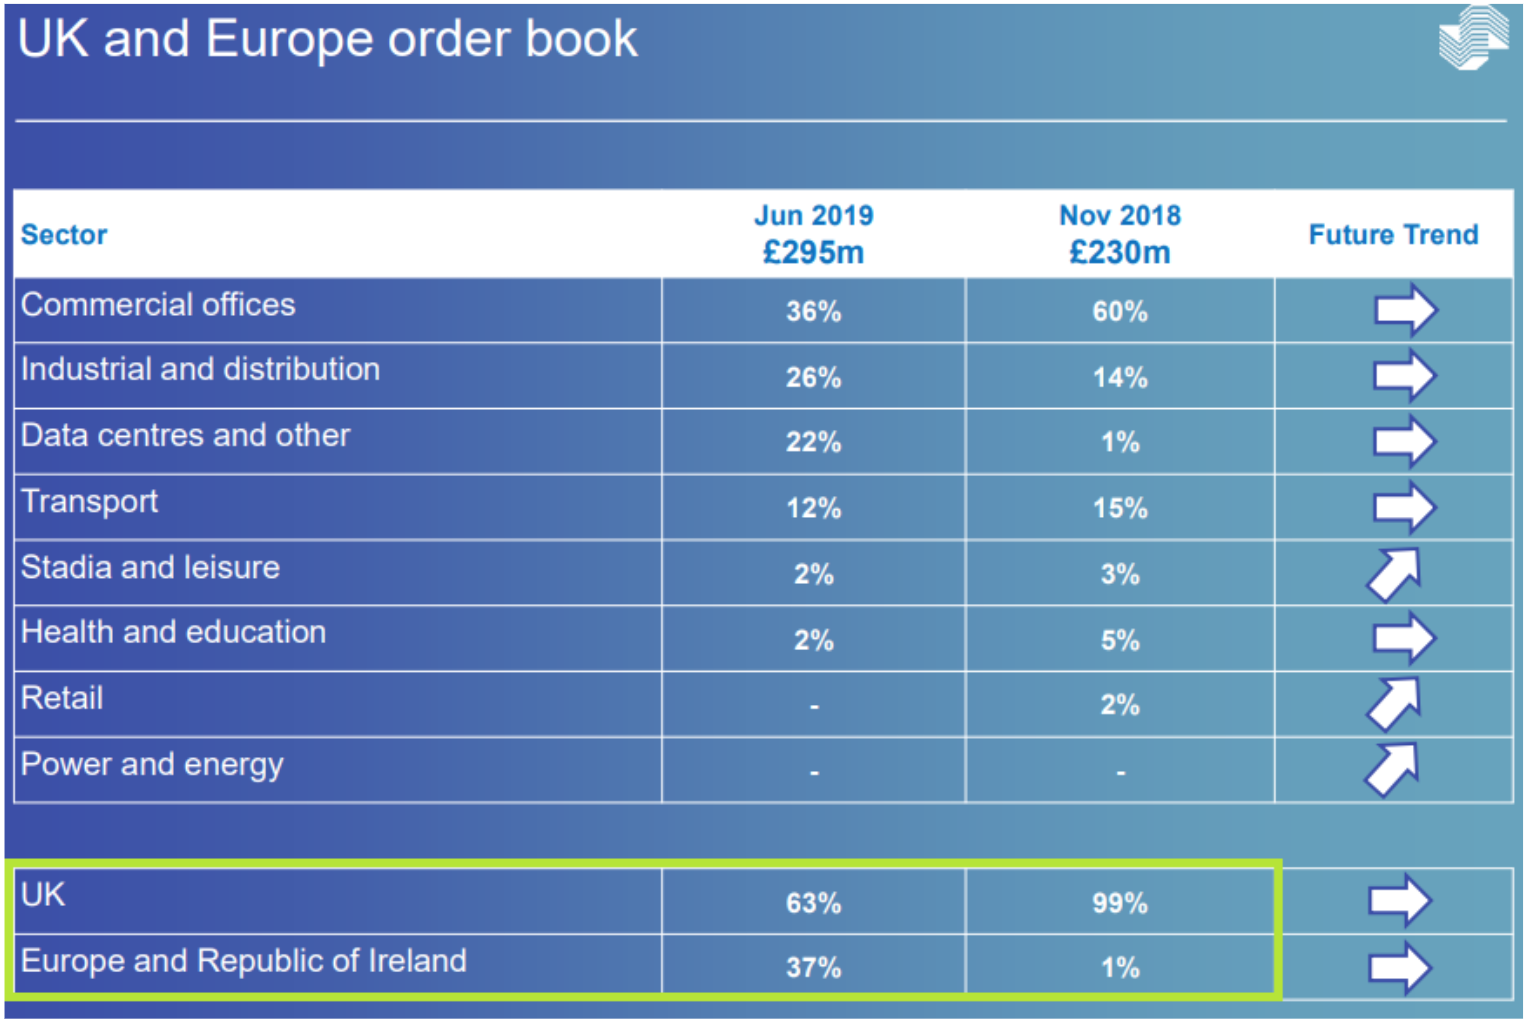
What this presentation seems to gloss over is that the UK order book appears to have fallen sharply during the second half of last year. Using the figures above, my sums suggest that the UK order backlog fell from £227.7m in November 2018 to £185.9m in June 2019.
The UK is still the core of the group’s operations. I imagine that competition is tougher for a relatively new entrant in Europe. Is the European expansion simply a away to prop up the order book, rather than a genuine growth opportunity? I think it’s hard to say at this point in time.
On balance, I feel that Severfield’s order book isn’t as reassuring as it initially appears.
Buying in growth?
Broker forecasts for Severfield rocketed higher at the start of this month:
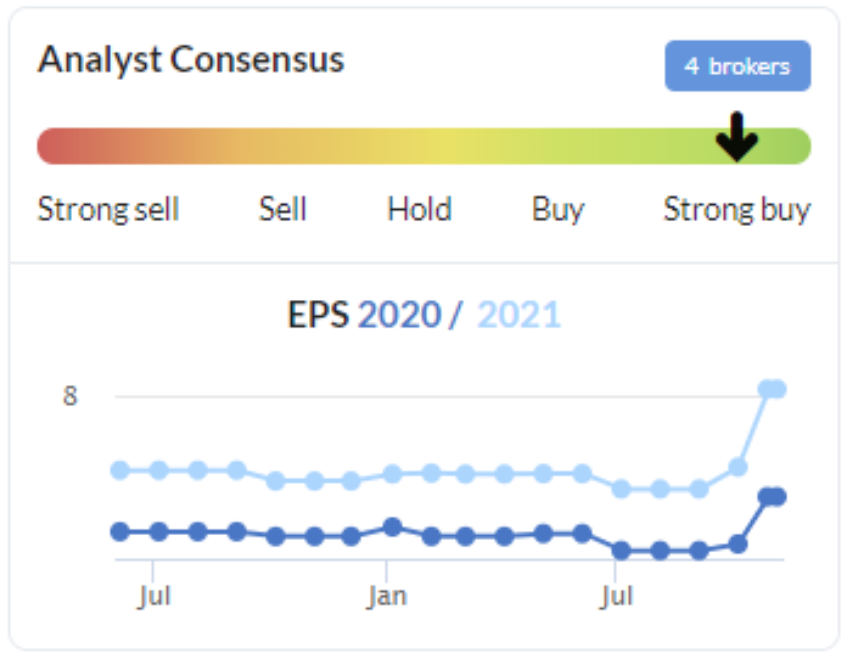
At first, I couldn’t work out why this would be. But I then noticed that the firm had announced an acquisition valued at up to £25m at the start of October.
The deal is for a firm called Harry Peers which is described as a “full-service structural steelwork business”. Peers seems to have a greater exposure to the energy and infrastructure sectors than Severfield, especially the nuclear sector.
I can see the logic behind this deal, but I’m concerned that the company may be buying in growth. Peers’ pre-tax profit for the year to 30 April was £3.4m. Assuming a similar tax rate to the c.20% reported by Severfield, I estimate that this would add about 1.1p per share to the group’s earnings.
Consensus earnings forecasts for the current year have risen by about 0.3p per share since the Peers deal was announced. Forecasts for FY21 have risen by about 0.4p. These figures suggest to me that in the absence of the Peers acquisition, Severfield’s profits might have been expected to fall, both this year and next year.
Broker forecasts from 28 September -- before the Peers deal -- suggest that analysts were taking a similar view:
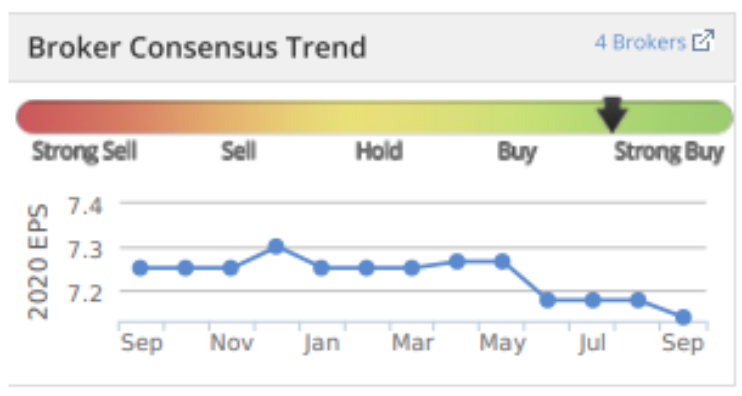
This seems to support my concerns about cyclical contraction in the core UK business. Severfield seems to be relying on European expansion and acquisitions to deliver growth. That’s not ideal, in my view.
QVM analysis
I’m running out of space to analyse Severfield’s QVM scores. But there are a few points I’d like to highlight.
ValueRank: Severfield’s ValueRank of 65 looks reasonable enough. The only glaring problem I can see is that free cash flow appears to have been very poor last year:
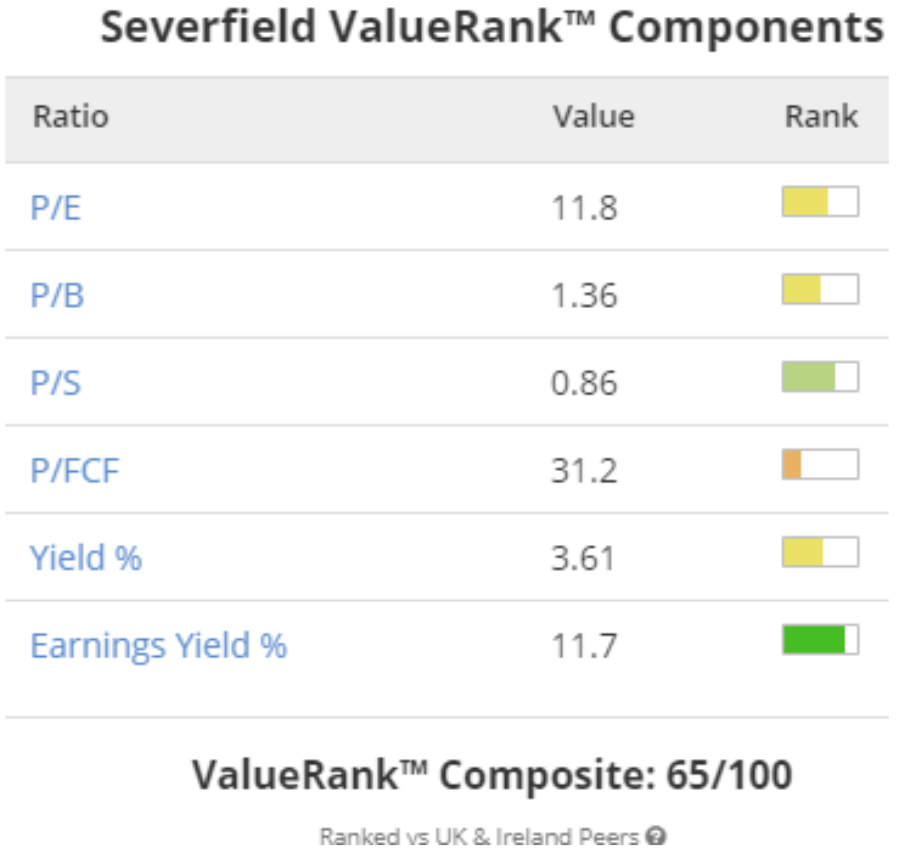
This appears to be down to unfavourable working capital movements. The company says these relating to timing issues on contract cash flows and a normalisation of working capital following an abnormally low year-end figure.
However, I’d note that operating cash flow before working capital movements also fell slightly last year:
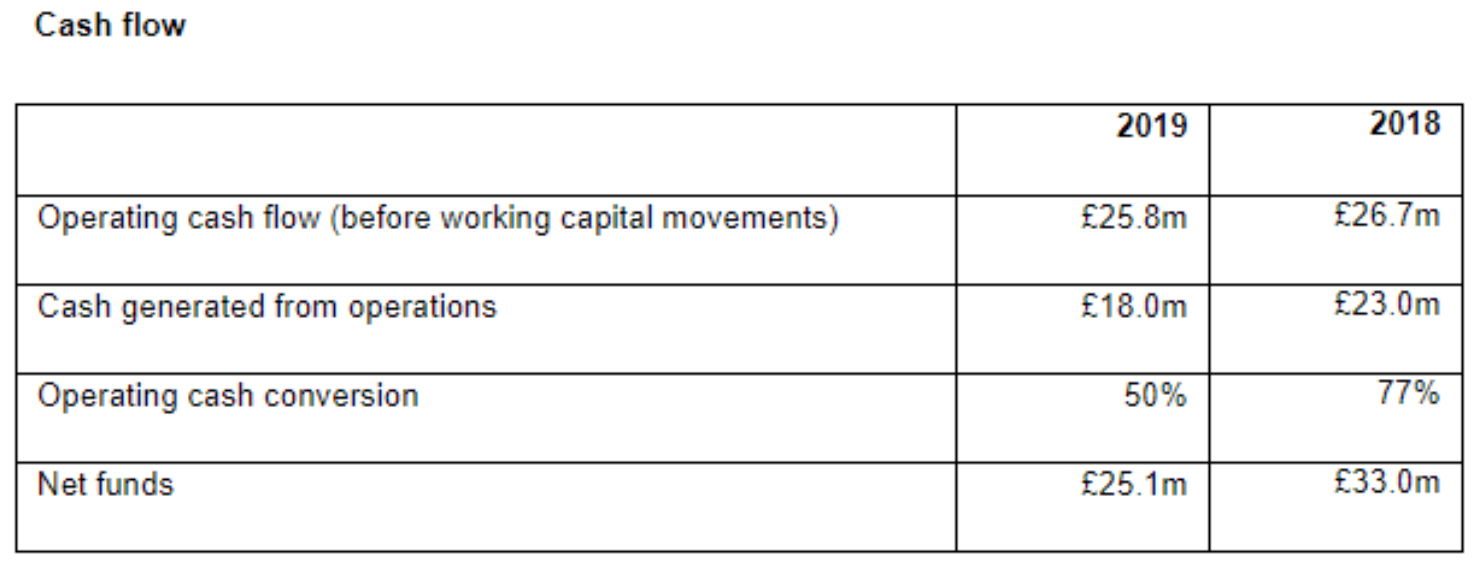
Lumpy contract businesses do often have uneven cash flows. But I think this is worth watching, in case November’s H1 results show continued worsening of the group’s cash performance.
QualityRank: Severfield scores more highly for quality.
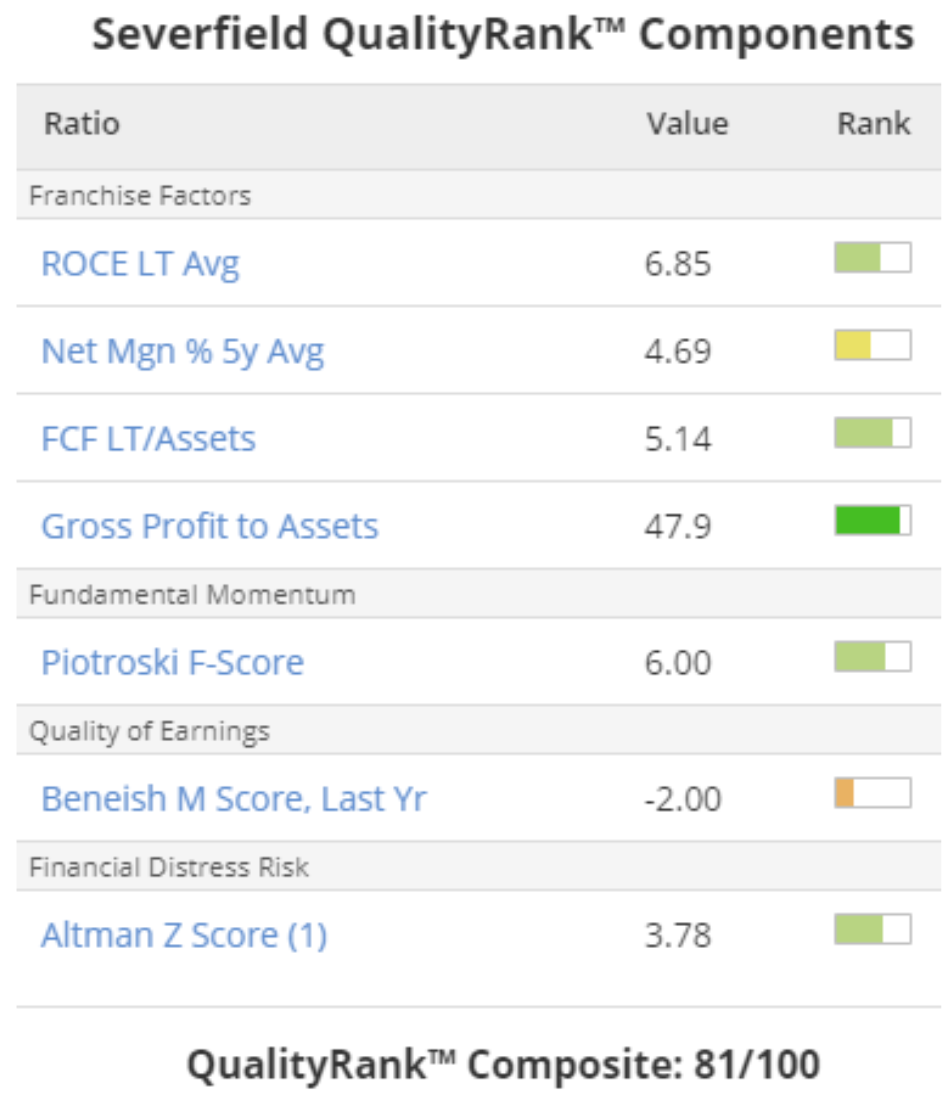
I don’t really have much to add to this. This capital-intensive manufacturing business is never likely to generate a high return on capital. But these figures all look reasonable to me. I don’t see any particular cause for concern.
MomentumRank: The steel group’s highest factor score is its MomentumRank of 95.
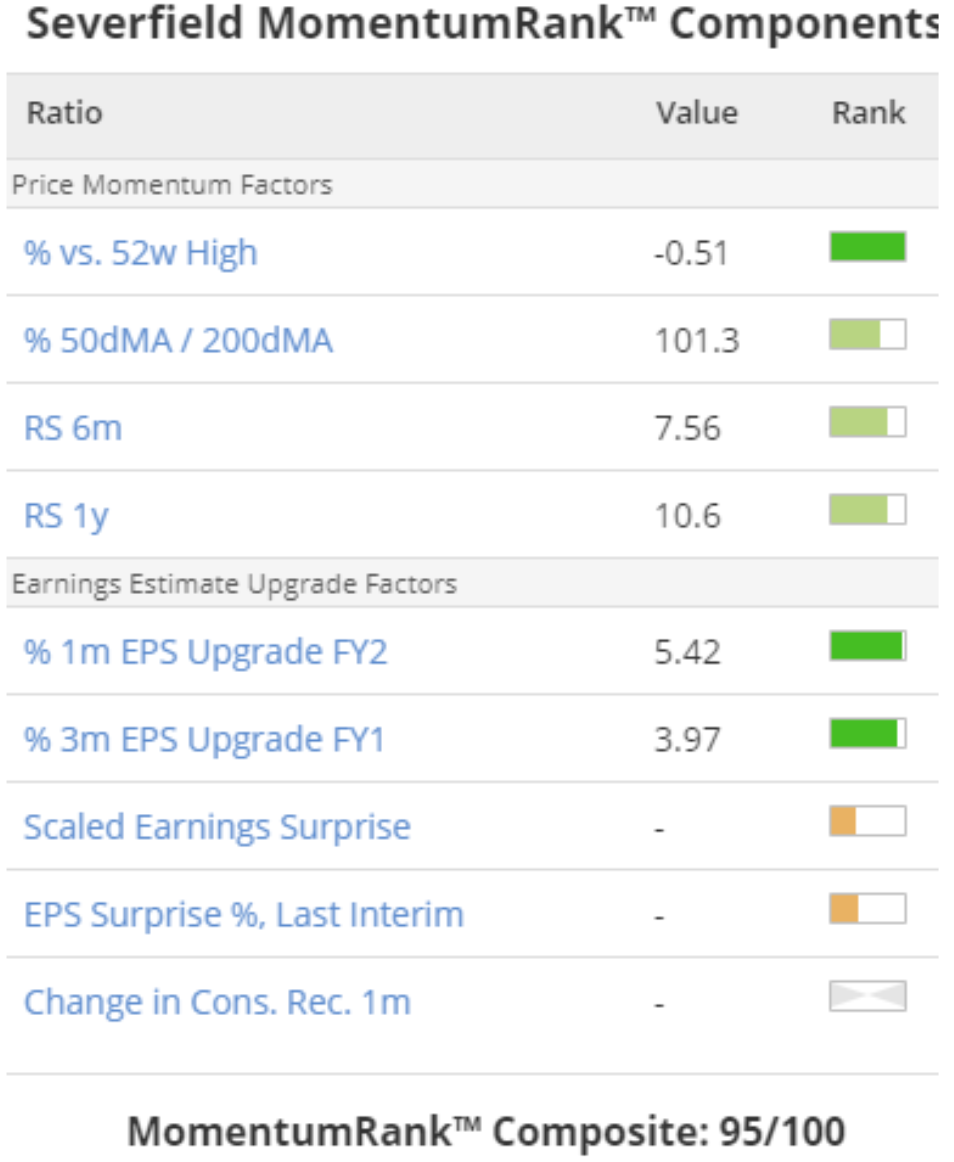
I think we need to ask why this score is so strong. Once again, let’s return to 28 September, just before the Peers acquisition was announced. Here we see a much lower momentum score of 69:
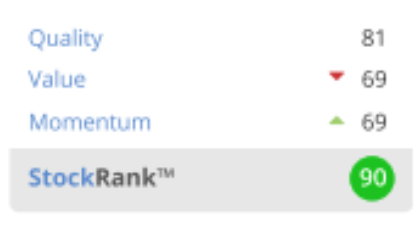
I’m not able to access the component breakdowns of these ranks for past reporting dates. But I think it’s fair to say that the earnings upgrades shown above are a direct result of the Peers acquisition. Without this, I think momentum would look much weaker.
My verdict
I don’t think Severfield is a bad company. But I’m concerned by the apparent contraction in the core UK business, which may prove to be a cyclical slowdown.
I’m also unsure how to interpret management’s decision to seek fresh growth in Europe and by acquisition.
On balance, I’m not comfortable with this situation. Given that I already have some exposure to the UK construction sector through the SIF folio’s holding in brickmaker Michelmersh, I’ve decided not to add Severfield to the portfolio this week.
Severfield’s half-year results are due on 26 November. I will await them with interest and may revisit this company once we have a fresh set of accounts to consider.
Disclosure: Roland owns shares of Michelmersh Brick Holdings.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

9 comments
The Investers Chronicle rated this as a buy not that many months ago, but I was concerned about the UK reliance. I am interested to hear about there reliance on India, how does one go about finding this level of information and as some says below, the order book is flat.
Hi tadreamsirbaggy,
Thanks for your comment. There's some more detailed information about the India order book in the annual results presentation from June:
https://www.severfield.com/wp-content/uploads/2019/06/Full-Year-Results-to-31-March-2019-WEB.pdf
The India order book appears to be growing but the contribution to annual profit from this 50:50 joint venture is still quite small - it was £1.2m last year, versus group profits of c.£20m.
There's also more information in last year's results:
https://www.stockopedia.com/share-prices/severfield-LON:SFR/news/severfield-plc-results-for-the-year-ended-31-march-2019-urn:newsml:reuters.com:20190619:nRSS6744Ca/
and the annual report:
https://www.severfield.com/wp-content/uploads/2019/08/Severfield-AR2019-Index-Linked-PDF.pdf
Regards,
Roland
Thanks for the article Roland.
Coincidentally I researched this company a few days ago and agree that the reliance on the UK was enough to make me not want to purchase.
I also don't recall there being a UK/Europe/ROI revenue split, which I found odd and quite unhelpful.
A lot of emphasis is being placed on growth in India, where the company has a JV.
Whilst growth has indeed been impressive over the last couple of years, the fact that the order book there remained relatively flat makes me suspicious that it is perhaps not the golden goose one might think it is.
I also recall reading about an attempt to target smaller customers with lower margins, and that the company was finding this a difficult area to compete in. Very little emphasis was placed on the progress of this venture in the last report. I always appreciate a thorough update, even if it's negative, and the absence of any news here makes me wary.
It's certainly going on my watch list, but if it's going to be a purchase it will be once the performance (growth?) in the UK becomes clearer.
Cheers
A
Hi Abtan,
The revenue split came from the analyst slide presentation issued at the time of the full-year results. This is available on the website - I often find that these presentations add useful detail and 'colour' to the results RNS.
I'm not sure what to make of the Indian venture in terms of profitability - more research would be required, I think. As you say, achieving profitable growth might be harder than it first seems.
Cheers,
Roland
Severfield (LON:SFR) The share has performed well over the last 3 months and continues into the last month.
If the 5 day graph is upward I will buy with a 2% St.Loss
Thanks for the analysis, Roland. Admirably thorough and objective as usual!
Please will you remind me how to access the breakdown of an individual QVM rank for a company?
Hi FREng,
The breakdown of the QVM ranks can be accessed from the sector pages on the old version of the site, e.g. https://www.stockopedia.com/sectors/construction-engineering-522010//
Just click on any of the individual ranks and the breakdown will pop up.
I don't think this feature is available on the new Stockopedia site yet.
Regards,
Roland
Thaks for the explanation. I'm using the new site almost exclusively, so I hope this feature will appear soon!
According to the product roadmap (link bottom right), it's still in the backlog:
https://www.stockopedia.com/learn
You can add a vote in favour if it's something you'd like to see. At present, Level 2 data has a lot more votes!
Cheers,
Roland