Stock in Focus: Should Sainsbury's shareholders back the Home Retail deal?

Sainsbury pushed negotiations down to the wire, but on Tuesday the supermarket group finally made public the details of a possible £1.3bn offer for Home Retail Group.
For Home Retail shareholders, I believe this is a good potential offer. If the proposed deal goes ahead, Home Retail investors will walk away with cash and Sainsbury shares worth 161p at the time of writing.
If Sainsbury shares don’t appeal, then Home Retail shareholders can sell into the market for around 150p. This equates to a 53% gain since the start of 2016, and prices Home Retail shares on 17 times 2016 forecast earnings. That seems generous for a low margin retailer with an uncertain outlook.
The big question, of course, is whether this is a deal that will enrich Sainsbury shareholders. The supermarket was one of Stockopedia CEO Ed Croft’s NAPS selections for 2016. It’s also a popular income stock and is the best-performing listed supermarket of recent years.
As a result, I suspect many private investors will be trying to work out whether this is an attractive deal. In this week’s column I’ll try and answer that question. By combining an understanding of how Stockopedia ranks Sainsbury with the details of proposed offer, we’ll hopefully be able to draw a sensible conclusion.
Solid foundations
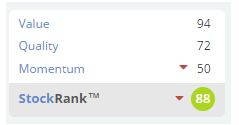
Let’s start with a look at Sainsbury’s quality credentials. The supermarket has a StockRank of 88 and a QualityRank of 72.
The group’s main weakness in terms of quality is its low profitability. A long-term return on capital of 8.1% isn’t too bad, but the 5-year average net margin of 2.1% is uninspiring.
Things seem unlikely to improve soon. During the first half of this year, the supermarket’s sales fell by 2%, despite a 3% rise in transaction numbers and volume growth of 1%. Return on capital employed fell from 11.1% to 9.1%. It’s a tough market.
Despite this, Sainsbury doesn’t seem to have any fundamental problems. The stock has a Piotroski F-Score of eight out of a possible nine. That’s a tribute to effective management, good cash generation and relatively modest debt levels -- net gearing is under 20%.
If I was a shareholder, I’d be keen for management to preserve this low debt advantage. Luckily, the Home Retail deal doesn’t seem to require much, if any, fresh borrowing. The 55p per share cash payment included in the proposed offer for Home Retail equates to a cash payment of £447m. Sainsbury’s latest accounts show a cash balance of £1,266m, suggesting that much of this payment may be able to come from the firm’s cash balance.
Good value without Home Retail?
Before we try to estimate the impact of the acquisition, it’s worth considering whether Sainsbury is attractively valued without Home Retail.
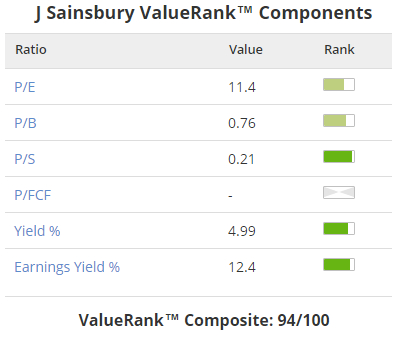
A ValueRank of 94/100 suggest that the answer may be yes. Sainsbury trades on a trailing P/E of 11.4 and a price/book ratio of 0.76. Although Sainsbury’s new dividend policy means that the this year’s yield will probably be lower than last year’s 4.99%, an earnings yield (EBIT/EV) of 12.4% is attractive in this sector.
Looking beyond these statistics, it’s worth noting that Sainsbury's has land and buildings on freehold or long leases worth £7,015m. Sainsbury’s Bank has net assets of £613m. These assets should provide some downside protection, given that Sainsbury’s shares currently trade at a 20% discount to their tangible book value of 304p.
Without Home Retail, I’d feel fairly comfortable investing in Sainsbury’s at current share prices.
How will Home Retail fit?
For each Home Retail share, Sainsbury will issue 0.321 new shares. This equates to 261.1m new Sainsbury shares, which is a 13.5% increase in Sainsbury’s share count.
In return, Sainsbury will acquire the Argos business and Home Retail’s customer credit business (Homebase has already been sold to Australian firm Wesfarmers).
By extrapolating from Home Retail’s interim and last full-year results, I estimate that Argos should deliver an underlying operating profit of about £75m for the current year. The financial services business should contribute about £7m of operating profit. That’s £82m in total.
Sainsbury generated an underlying operating profit of £725m over the twelve months to 26 September. This means that the bought-in operating profit from Home Retail should add around 11% to Sainsbury’s operating profit. That’s fairly similar to the level of stock dilution I calculated above.
By this crude estimate, I’d say the payment in shares should not significantly dilute Sainsbury’s operating profit margin. This is important because it should mean that Sainsbury can afford to maintain a similar dividend payout ratio after the acquisition.
It may not surprise you to learn that Sainsbury’s board is slightly more optimistic. In its offer statement, Sainsbury said that it expects the possible offer to be “earnings accretive in the first full year following completion”. In other words the extra profit will outweigh the dilutive effect of new shares.
My other concern relates to the potential of this deal to provide cost savings and profit growth. Sainsbury needs to justify the £447m cash consideration it will pay. It also needs to justify the £140m it plans to spend on “the realisation of identified synergies” during the three years following completion.
Sainsbury's plans to realise synergies in three main ways:
- Closing down Argos stores as their leases expire, and relocating them into nearby Sainsbury’s stores. Also opening new Argos concessions in Sainsbury’s stores;
- Removing duplication from head office and support functions;
- Selling Sainsbury’s non-food range through the Argos network.
Can this generate £587m of additional profit over time? Sainsbury’s has said that it expects the combined company to “generate EBITDA synergies of not less than £120m in the third full year after completion”.
Based on this comment, the group expects a long haul, but there is also a second possibility. Argos’s profit margins have fallen sharply this year. During Home Retail’s last full financial year, Argos generated an underlying operating profit of £129m -- nearly 50% more than I expect Argos to make this year.
As Sainsbury increases the number of new-style Argos concessions and closes costly old stores, Argos profit margins may improve. Sales may even rise, if Sainsbury’s customers can be tempted to try catalogue shopping...
I’m concerned that Sainsbury is expanding outside its area of core competence and attempting to go head-to-head with Amazon and Dixons Carphone. This seems a tall order to me, even with the potential advantage of same-day delivery and high street collection points.
On the other hand, I’m tempted to say that the Home Retail acquisition seems reasonably priced. I don’t think it will do any harm to Sainsbury’s earnings or dividend prospects. It could even trigger a new generation of growth.
The market appears to have a fairly neutral view, based on Sainsbury’s share price action this year:
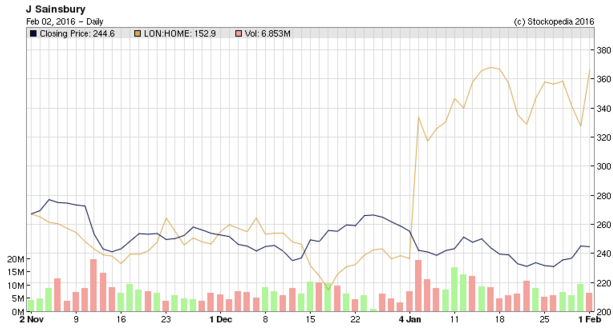
I share this view, but this is clearly a DYOR situation, so as always please share your thoughts below.
I’ll track Sainsbury’s shares from the day this article is published, and review the situation at the end of this year.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

11 comments
I see Steinhoff have this morning stated they will not increase their offer for Darty (LON:DRTY). Presumably they are offside under UK takeover rules for revisiting Home Retail (LON:HOME) until August/September at the earliest so unlikely to re-enter the fray unless the Sainsbury's bid falters. However, with cash burning a hole in their pocket and a desire to enter the UK (and expand further outside of South Africa), I wonder who might be next on the shopping list - I gather BHS might be available!?
Gus.
I've been following the whole saga, being a reasonably long term Home Retail (LON:HOME) holder. I ended up selling most of my holding today as I'm not sure that Sainsbury's will make another offer, and if they do I'm not very confident that it'll be much higher than what they have already proposed. There was a lot of convincing and pushing required to get the majority shareholder on board with the current offer, and they've said from the start that they are not willing to overpay (presumably their own valuation of what the HOME deal is worth). Will be very interesting to see what happens next.
Next week should be very interesting. Will SBRY come back with an improved offer? This is the CEO's big strategy and they have done a lot of work to get their big shareholders on board (and £1.60 is cheap IMO) so i feel that they will. I'm a SBRY and HOME shareholder so i'm in the position whereby I want HOME to be sold for as much as possible but I don't want SBRY to overpay! Steinhoff could be the answer! Having said that, I do think (unlike others) it makes strategic sense for Sainsbury to buy HOME for lots of reasons.
As a holder of both, I was quite happy with the original Sainsbury offer and could see the logic of putting the two together. Steinhoffer is a bit of a curve ball, but I note their market cap is roughly 2.5x that of Sainsbury (£13bn vs £5bn) so if it does get into a bidding war, they may well have deeper pockets and be prepared to dig deep into them. Coming late into the game, they must have a good idea of what higher offer they may ultimately be willing to make. Can only be good for Home Retail (LON:HOME) holders.
Gus.
Speaking as a Sainsburys shareholder I'm a bit miffed , I thought their offer was both well timed and well priced and fairly widely under appreciated , a sweetener looks necessary to get the deal over the line which is a pain.
I had been considering an investment in Sainsburys; reasonable valuation. reasonable financial strength, decent divi, and holding their own on the sales front pretty well while giving a slight quality feel and edge compared to the mainstream supermarkets. My inaction centred on the fact that the supermarket sector is going to be long fought battle, tho' I would have picked Sainsbury as a strong survivor, that Sainsbury was possibly tilted a bit too much towards big stores and had no clear strategy for growth outside the food sector. I agree with b sharman however that the Argos deal could be transformational by adding a lot of smaller sites and, by bringing in the Argos website giving a strong boost to their non-food side plus a tried and tested delivery system. Am now a likely buyer of the shares.
RT
Hi Roland.
As a shareholder in both Home Retail (LON:HOME) and J Sainsbury (LON:SBRY) I am quite positive about the transaction, especially if management can successfully integrate the Argos business and squeeze out the synergies as proposed. It is a bonus that Homebase has already been offloaded at a good price although like many commentators I was surprised how expensive splitting out the business seems to be.
With regards to the terms of the deal, I think the cash/debt position post acquisition is better than you suggest. Given Home Retail (LON:HOME) has estimated cash of c.£200m plus a retained earnings loan book of c. £550m (possibly more after seasonal spike due to Christmas credit sales), using Sainsbury's Bank to take this in using say 15% capital (c.£85m) would make available c.£660m, ie more than enough for the £447m cash payment and a fair chunk of the transaction/integration costs without ballooning the balance sheet.
One final thought, any chance of a spoiler coming in with a higher offer? Someone like Amazon or Ebay could buy this out of small change for the same logistics play while at the same time disrupting a potential competitor in the UK market.
Gus.
Hi Gus,
Thanks for your comment. You're right that the post-deal cash/debt situation may be better than I suggest, but we don't exactly know how much of the Home Retail (LON:HOME) cash balance will be left by the time two separate corporate deals have been negotiated and bills paid, etc. Nor do I know how the loan book will be accounted for. As a result, I decided to err on the side of caution here and focus on actual cash (I know, call me old fashioned!).
Personally I'd be very surprised if anyone tries to outbid Sainsbury. I don't see a very good fit for Amazon or eBay due to their focus on online transactions. Amazon is also well down the road to creating its own logistics operation in the UK, so trying to integrate what Argos has would be likely to cause the wrong kind of disruption, IMHO!
Cheers,
Roland
Home Retail (LON:HOME) just released an after hours RNS to the effect that they have been approached by Steinhoff Group with a competing offer valued at 175p per share (not clear whether all cash or cash and shares). Game on. Interesting to see terms of the offer and whether J Sainsbury (LON:SBRY) can/choose to sweeten their offer.
Gus.
http://www.investegate.co.uk/home-retail-grp-plc--...
Just re read the release. Looks as though it is all cash offer
Ditto Justifies my method of buying what is unpopular but has strong value metrics. Both holdings now in profit. No comment on the future. Others are expert.
I hold both J Sainsbury (LON:SBRY) and Home Retail (LON:HOME) - I think that this is a cracking deal for J Sainsbury (LON:SBRY) and seems quite cheap for what they are buying. This transaction allows them to compete against the likes of M&S and John Lewis in non food. It also gives them a load of new smaller shops, which they can transform into Sainsbury Local. They pick up fantastic website and mobile sites that Argos have been developing over the past two years and the hub and spoke delivery infrastructure across the UK. In my opinion it's a inspired and brave move by J Sainsbury (LON:SBRY) and I'm therefore pleased to be getting some more J Sainsbury (LON:SBRY) shares!