Stock in Focus: Why GlaxoSmithKline has hammered the market since 2011

If you’ve followed the investing press in recent years, you may be under the impression that GlaxoSmithKline is an underperforming laggard that’s fallen off a patent cliff.
The truth is rather different. Glaxo shares have delivered a total return (dividend plus capital gains) of 52.8% over the last five years. During the same period, I estimate that the FTSE 100 has delivered a total return of about 15%.
Perhaps this is why Glaxo is one of very few big cap stocks to qualify for several of Stockopedia’s more successful value and quality investing screens.
Isn’t it too big?
I can already sense suspicion from Stockopedia’s devoted band of small cap investors! Surely lumbering elephants like GlaxoSmithKline are doomed to underperform their smaller, nimbler siblings?
Apparently not. Here’s a summary of Glaxo’s returns since 2011:
- Closing price 4 Feb 2011: 1,171p
- Capital gain (@1,363p): 16.4%
- Dividends paid: 426p (36.4% return)
- Total return: 52.8%
If nothing else, this is a dramatic reminder of how dividends often form the bulk of investors’ returns. It also suggests that investing in good quality dividend stocks and then doing nothing can be a good way to beat the market.
On the other hand, many small and mid-cap investors have done much better than 52% over the last five years. A fair number of stocks have delivered gains of more than 100%. Ed Croft’s NAPS portfolio returned 43.4% last year alone.
Is GlaxoSmithKline worth considering as a buy, or is it simply too large to deliver market-beating returns?
Deceptively good value
Using Glaxo’s preferred measure of core earnings per share, the stock trades on a trailing P/E of 18. It certainly doesn’t look cheap and a ValueRank of 37 appears to confirm this view.
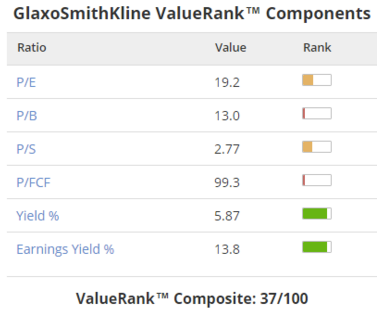
However, there are two value metrics on which Glaxo scores very highly. The stock has an earnings yield (EBIT/EV) of 13.8% and a trailing dividend yield of 5.9%. These are very attractive figures, without being outlandishly high.
Historically, another of Glaxo’s big strengths has been that its generous dividend has been covered by free cash flow. Last year wasn’t a great year for the firm and free cash flow was poor. The 80p dividend was not covered by adjusted earnings or free cash flow.
However, the Stockopedia figures show that over the last six years, free cash flow has totalled 450p per share. That’s almost an exact match for dividends during that period of 447p per share.
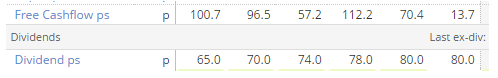
Cash-backed dividends such as these are a big attraction in value shares, in my view.
If you’re looking for further support for the idea GlaxoSmithKline is a value share, it’s worth noting that the stock qualifies for the James O’Shaugnessy Cornerstone Value Screen and the Richard Beddard Nifty Thrifty Screen. Both of these value screens have outperformed the FTSE 100 over the last two years.
A dose of quality
The reason that Glaxo’s cash generation has historically been so strong is that it enjoys consistently high profit margins and generates a high return on capital employed (ROCE). That’s one of the benefits of selling products that either have strong brands or are mostly protected by patents.
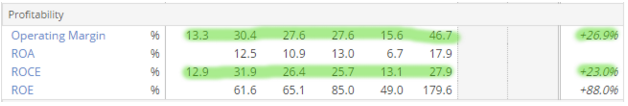
Glaxo’s ROCE has averaged 23% since 2010. During the same period the group’s operating margin has averaged 26.9%. These are outstanding figures and help explain why Glaxo has generated market-beating returns over this time.
Although the stock’s QualityRank of 69 is not outstandingly high, Glaxo scores very highly on Franchise Factors. These are ratios which suggest that a company has some kind of strong competitive advantage.
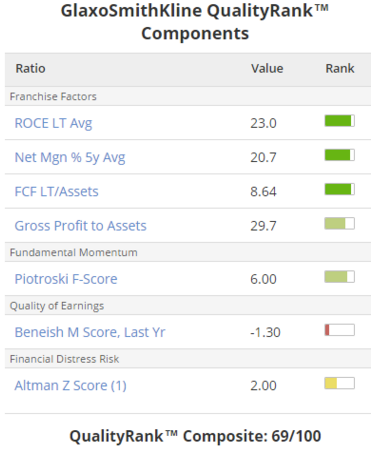
The main reason that Glaxo’s QualityRank isn’t higher is that the stock has a rather middling Piotroski F-Score of 6 out of a possible 9. Drilling down, the main reasons for this are last year’s poor cash generation and weaker profit margins.
I’m tempted to dismiss these as transient issues. Glaxo’s deal with Novartis has removed a chunk of debt and significantly reshaped its product portfolios. The City seems confident that performance will improve this year.
It’s also worth noting that GlaxoSmithKline is the only UK big cap which qualifies for the Greenblatt Magic Formula screen. This screen, which ranks stocks according to a blend of earnings yield and return on capital, is one of only two quality screens to deliver positive returns and beat the FTSE last year.
Very few large companies currently offer this combination of high returns and a high earnings yield. That’s why I believe Glaxo’s current valuation is very attractive.
Improving momentum
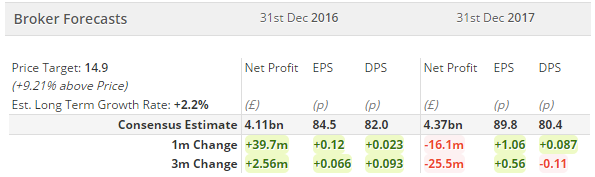
Indeed, I’d argue that this may be a good time to consider investing in GlaxoSmithKline. Net debt fell by almost £4bn to £10.7bn last year, and the 6% forecast dividend yield looks increasingly sustainable. A return to earnings per share growth is expected in 2016:
The Stockopedia computers also seem to back this upbeat view. GlaxoSmithKline has a Momentum Rank of 92, 14 points higher than 30 days ago.
Earnings forecasts have also been edging higher over the last few months, as you can see above. Price momentum also appears quite strong. Glaxo shares are less than 20% below their 52-week high. The share price chart also seems to suggest that the downward trend seen since last May may now have bottomed out and be turning into an uptrend:
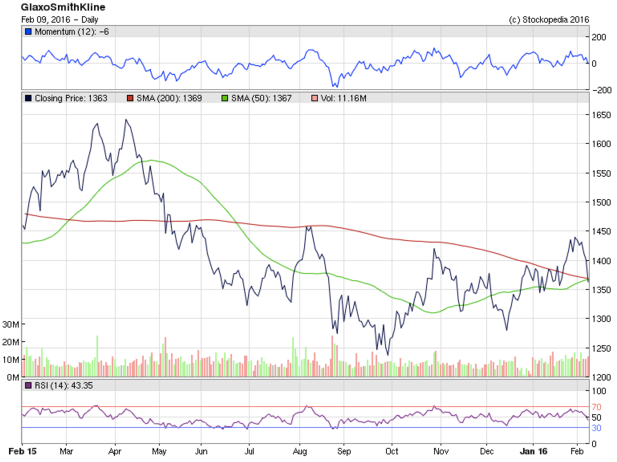
My view is that the firm has weathered the storm and that a return to growth is now likely.
Another view that’s worth considering is that if Glaxo underperforms for too long at any point in the future, the group could be profitably split into several standalone businesses. This possibility has had some press coverage in recent months, thanks to fund managers such as Neil Woodford.
It’s clear that Glaxo could be split into pharmaceutical, vaccine and consumer healthcare businesses, all of which would have scale. The firm’s board has also previously considered spinning off its HIV business, ViiV Healthcare, into a separate entity.
I recently added some more GlaxoSmithKline shares to my own long-term income portfolio. Let me know if you agree -- or if you side with the late Jim Slater and believe I am throwing away potential returns by investing in such a large company.
Disclosure: Roland owns shares of GlaxoSmithKline.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

34 comments
TMFMayn
Good work on GSK. have a look at AZN as well. Serial abusers of the "core" earnings fantasy. It's basically what Charlie Munger defined as "earnings before bad stuff". Unfortunately the bad stuff is often poor decisions by management in prior periods. I once took the First Group management team to task on this issue regarding their egregious (in my mind) use of exceptional so. There was a lot of squirming on the other side of the table!
good to spotnandmpoint out. many thanks
Hi Roland
Just for reference, here are Glaxo's 'core' adjustments for the last four years:
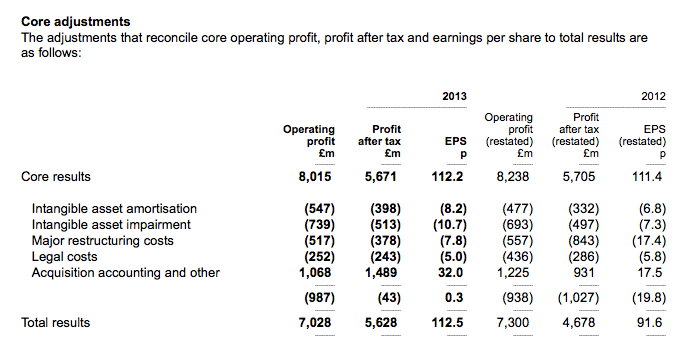
They are not insignificant.I would always caution against using data sites to calculate FCF etc as you never really know what is included or not.
Sure, the intangible amortisation and impairment charges are not cash costs, but they relate to an asset that was once acquired for cash. Terry Smith suggests that such ongoing intangible expenditure ought to be reflected in the P&L and so investors ought to at least consider the intangible accounting charges. The major restructuringand legal costs are presumably cash costs.
Anyway, it is up to Glaxo investors to take a view on these 'exceptionals' and work out FCF etc for themselves. I suspect that is what Terry Smith has done.
Hi Mayn,
Thanks for taking the time to post this. I agree that many of these exceptionals appear to be recurring, and should therefore be included in core earnings.
As always, my comments aren't advice. Investors should DYOR before hitting the buy (or sell) button!
Roland
Roland wrote in his article: "Historically, another of Glaxo’s big strengths has been that its generous dividend has been covered by free cash flow. Last year wasn’t a great year for the firm and free cash flow was poor. The 80p dividend was not covered by adjusted earnings or free cash flow. However, the Stockopedia figures show that over the last six years, free cash flow has totalled 450p per share. That’s almost an exact match for dividends during that period of 447p per share."
If a company pays out almost all of its cash profits as dividends, does that suggest it is not investing enough in capital expenditure and research and development to sustain future growth in the long term?
Hi pka,
Free cash flow is normally calculated after capital expenditure, so it's a measure of the cash that is surplus at the end of each year. In theory, it would be more prudent to retain some of this (for example to reduce debt) while paying a portion out as dividends.
In practice, low debt costs and a desire to keep shareholders happy have led to Glaxo paying virtually all of its free cash flow as dividends. The firm's profitability means I don't see this as a huge concern, although personally I would like to see debt come down further before any dividend increase is contemplated.
Regards,
Roland
Terry Smith is not a fan of GSK (or AZN).
https://www.fundsmith.co.uk/news/article/2015/09/2...
"One sector in which my Fundsmith Equity Fund does not own any stocks is pharmaceuticals...
One reason we don’t own them is that the sector has become rated on the basis of “underlying” earnings. Beginning in about 2010, many major pharmaceutical companies started a switch to reporting what they term “core” earnings. This switch was allegedly to smooth out exceptional items from reported earnings and make trends more recognisable."
He doesn't like the "doctored" P&L accounts.
He makes some interesting points but I think they would cut far more ice with me were it not for the similarities between all those pharma companies he lists. I just wonder if it is the case that we have to be careful before we apply identical criteria to non-identical industries? One of my constant concerns about Stockopedia is the way it seeks to simplify, perhaps all too glibly, the means by which we can compare different stocks. I'm not being critical; I just think it's tricky to judge a beagle against a terrier, let alone a beagle against a snake.
I note that the market seems unimpressed by GSK being fined for bribing competitors. Does that mean we assume it goes on anyway?
Hi Mayn,
Thanks for the comment. I agree that adjusted eps can hide a multitude of costs. The big pharma companies are hardly the only offenders in this regard, although they do seem to be at the more severe end of the spectrum.
As I see it, a good safeguard is to look at free cash flow, since if this is strong then earnings per share aren't that important anyway. Terry Smith also refers to the value of the cash flow statement in the article you link to.
As things stand, GlaxoSmithKline (LON:GSK) has a fairly decent track record of generating cash. GSK's average free cash flow for the last six years (using the Stockopedia/Reuters calculation of FCF) is 75p per share -- the same as 2015 'core eps'.
Whether the firm can return to higher levels of FCF this year remains to be seen.
Regards, Roland
How do look at a companies Value rank components like you did for Glaxo in your article? I can only see the whole sheet for a company.
Thanks
Hi Source,
Good question! The way to do this is to go to the sector page for the company. For example, click on 'Pharmaceuticals' at the top of the GlaxoSmithKline (LON:GSK) page.
http://www.stockopedia.com/sectors/pharmaceuticals-562010//
You'll then see a list of all the companies in that sector listed with their ranks. Just click on the rank number in order to see the components behind it.
Hope this makes sense!
Regards,
Roland
Thanks Roland! Got it.
Regards,
Source.
I'm sure things have tightened up considerably but what I'm talking about is a natural reluctance among prescribers to want to stay with the tried and tested, reinforced by patients who become very confused at times when their familiar meds look different one week to the next. The point being that the very conservative nature of the business means that the doom and gloom prognosticators about patents expiring and there being nothing to take their place is not borne out in reality. It would be a tough call to truly compete with the big boys.
that's the great thing about equity markets, you pay your money and you take your choice
Sorry, imperial Brands (it was renamed this week!)
Imperial tobacco would be my income nap at the movement
Has anyone questioned the dividend clover at glaxo?
That's to say the cash earnings compared to what they pay out? The cover has been declining as the Board has raised the dividend but earnings have actually declined both on a nornalised basis (ie pre all the bad stuff) from 142p in 2010 to c70 in FY15. The dividend at 80p / share is not covered either by earnings or free cash flow. Net debt is £10bn and has been rising.
I know the Board are aware of this and have it as a discussion item but feel handcuffed by income investors demanding yield. Unless there is tangible evidence soon of an upturn in earnings, there must be a risk that the dividend is cut.
Therefore you have done v well to own the shares until now. HoweverIf I were you doing your total return sums on a forward looking basis, I may prudently want to factor in the potential for a dividend cut?
VegPatch,
I did flag up the risks relating to dividend cover by earnings and free cash flow in my article and also mentioned net debt. But debt has actually been falling, not rising. The Novartis deal enabled GlaxoSmithKline (LON:GSK) to reduce net debt from c.£14bn to c.£10bn last year.
At 80p, the dividend remains a push, but not impossibly so if earnings recover as they are expected to. I agree that it's not a sure thing, but Glaxo is an unusually profitable company with a long track record. I'm happy to stay put.
Regards, Roland
P.S. I'm not sure I share your optimism about Imperial Brands (LON:IMB). Imperial's net debt really has been rising and is now over 12bn -- more than 7 times last year's profits. The equivalent multiple for Glaxo is about 4, if you ignore last year's divestment profits.
I'd argue that Imperial may eventually need to reduce dividend payments in order to pay down some of its debt. After all, it's a declining business -- stripping out the recent acquisition of Reynolds American, today's results show that volumes fell by 9% during the final quarter of last year. This is a long-running trend.
John Kingham did a good piece on this recently: http://www.ukvalueinvestor.com/2015/11/imperial-tobacco-plc-debt-fuelled-dividend-growth.html/
Roland,
Not sure how the Amundi bit got into that comment - must have been the 5000 pounds of investment!
Andrew
Roland,
Appreciate your feedback and agree timing/initial valuation are the key to a good long term return and we all get it wrong sometime - hopefully not all the time in order to stay solvent! My original purchase was at £18.75 so the current yield is a healthy 4.3% and I did buy a few more in mid 2002 when they fell to around £14.50 lowering the average purchase price as you suggest. Unfortunately GlaxoSmithKline (LON:GSK) shares kept on going down (the dreaded falling knife) so whilst the yield is good the capital growth has been abysmal with the price still less than this lower level. Perhaps if a live long enough I may be able to sell without a capital loss sometime in the future but this is a bit like hoping England might win the Football World Cup twice in my lifetime!
Not sure I agree with you on gilts though. Had I bought (if only) the same amount (AMUNDI SP 500 ETF (LON:500)0) of 5% Treasury Stock 2025 at or close to par near issue in Sept 2001, ignoring accrued interest, I would have received £250 x 14 = £3500 in coupons and the gilts are currently trading at £131.45 so if sold would realise £6572.50 giving a total return over the period of £10072.50 - a return of over 100% vs. the 23% from the GlaxoSmithKline (LON:GSK) holding. I only if we had known back in 2000/2001 what we now know about the current chaos in the bond market.....!
Regards
Andrew
Andrew,
Thanks for your reply. You make a good point about the gilts -- I should have checked the figures before replying.
It's too easy to forget that interest rates and gilt yields were not always this low...
Regards,
Roland
Hi Roland,
Very thought provoking article. I hold GSK in my ISA.
I am tempted to add to my holding after studying all the points you have made.
On the subject of Pharma I would love to see an in depth study by you of Indivior a very highly rated share by Stockopedia which has tanked in the last 6 months.
Hi Tony,
Many thanks. I did cover Indivior (LON:INDV) when it was flying high last year, but this stock is on my shortlist to look at again after the full-year results are published later this month.
Regards, Roland
As a holder of GlaxoSmithKline (LON:GSK) since the start of 2001 I am less enthusiastic about the merits of the Company's capital growth (!?) and dividend record. Over the holding period of 15 years (a long term investment by most private investor standards) and including the prospective payout for Qtr 4 (inc. the special dividend) my simple Total Shareholder Return (TSR) is c. 23.2% (Capital loss per share of -27.7% + Dividend per share return of 50.88%). In terms of a CAGR% or annualised basis that amounts to 1.4% return per annum in nominal terms (excluding impact of inflation). My money would probably have been better invested in gilts or on deposit at a bank!
ACounsell,
Thanks for your comment, it's always good to have a different point of view.
Unfortunately, your experience demonstrates that even for long-term investments, the purchase valuation should be attractive. This isn't always easy to judge at the time as many Tesco shareholders (including me) can confirm...
However, I think you are underestimating the success of your investment. You have received a dividend return of 50% during that period. It sounds like you still own the shares, so assuming you paid around 2,000p you will still be earning an annual yield of 4%. That's not really a bad result. If you don't sell the capital loss is (arguably) not that important.
Not many shares, and certainly no gilts or deposit accounts, would have repaid 50% of your original investment in cash over the last fifteen years. As Glaxo's fortunes seem likely to improve (DYOR) then one option now might be to buy a few more. Doing this would lower your average purchase price and improve your dividend yield on cost.
It might even make it possible to sell without a capital loss at some point in the future.
Regards,
Roland
Hi Roland - Great article.
There is another reason why people should look closely at GSK. If you believe that we are at the start of a bear market, GSK proved to be highly resilient during the last crash.
During the 2008 stock market crash, FTSE100 fell from 6304 in May 2008 to 3531 in March 2009, a fall of 44%. GSK's corresponding fall was only 10%. And I believe it recovered pretty swiftly after that.
This stock has been in my SIPP for a while as a core component and I see no reason to doubt its resilience in today's choppy market.
Best. Ram
Two points that never seems to be considered in comparative reviews of companies (vs other companies or the market as a whole; capital gains are not gains until they are sold, and at that stage they may be protected from tax as in ISAs or capital gains tax is payable, as part of ones annual assessment. The other is that dividends are taxable and the net value of dividends will clearly be substantially lower thatn quoted say in the GSK calculation. Thoughts on how comparative figures should be quoted, or such caveats be referred to in comparing say high groiwth companies with high increases in SP versus low growth companies with high levels of dividends?
Hi ridavies,
Thanks for your comment. It's true that there are tax implications to both capital gains and dividends. The reason I almost always ignore these is that everyone's situation is different.
There are so many factors: SIPPs, ISA's, differing tax bands, spread betting accounts, offshore accounts, trusts -- all of these (and more) would affect the tax implications of an investment.
The other reason I ignore tax when writing about stocks is that as a general rule, I don't think it's likely to be (or should be) a deciding factor whether to buy a stock.
Hope this explains things from my point of view.
Regards,
Roland
I agree but tax should be taken into account when doing comparison. Capital gains are preferable to income for any tax payer. That apart another well research analysis. Thanks
I too am a very contented long term holder for all the same reasons. I am always fascinated to read, year on year, from analysts about the dangers of patents running out and no new drugs to take the places of the current high ticket earners. This fails to take into account two factors. One is the high level of R&D expenditure inherent in this business and the balance between that and the early returns on any successful drug. The other is that once a branded medication has found a niche, for a generic equivalent to dislodge it takes some doing. The profession is still sceptical about non-branded generic equivalents and rightly so. I see this entire sector as a long term growth industry in a world where standards of expectation of medical advances have yet to touch many areas.
"The profession is still sceptical about non-branded generic equivalents and rightly so."
Do you mean for the exact same molecule, or for different drugs for the same indication?
Both. For example, many years ago, a batch of supposedly penicillin V was found to be actually tetracycline, contra-indicated in children because of its effects on teeth and bones. In addition, you and I might start a company making a generic tablet containing an off patent money spinner but, although we did indeed incorporate the true dose of the real ingredient, by compressing it into acceptable tablet form, using substances known as "excipients" to make that a physical possibility, we might render the active ingredient useless. We could produce a tablet which passed through the entire digestive tract unavailable or which, by breaking up prematurely, become denatured by gastric acid. If we consider statins, it took a long while for there to be acceptance of a class effect for all statins as the proof, originally only related to simvastatin and signifiant doses at that. It's fashionable to sniff at "big-pharma" but the rules they have to abide by are amazingly stringent and I, for one have immense respect for them.
Aren't (onshore) generics pharma manufacturers following the very same stringent standards these days? I don't think I could easily start one (and this is a good thing!). Some of the generics are made by the very same companies which do on-patent drugs (e.g. Novartis is #2 on the generics market).
Good article. GSK have always been the biggest part of my portfolio as I am primarily interested in income and capital reservation. Seems to be a two horse race with GSK and AZN. When I started serious investing GSK were ahead, then focus switched to AZN and now GSK seem to be coming back.
Very good article and I agree, I have had GSK in my portfolio for years to raise my average yield in a long term portfolio. I don't have high hopes for capital growth. That said if we see the benefits of the re-invigourated R&D in the share price so much the better.
I get Jim slaters point that Elephants don't run, that said they don't get run over by Tom Winnifrith either.