Stockopedia StockSlam - June 2018

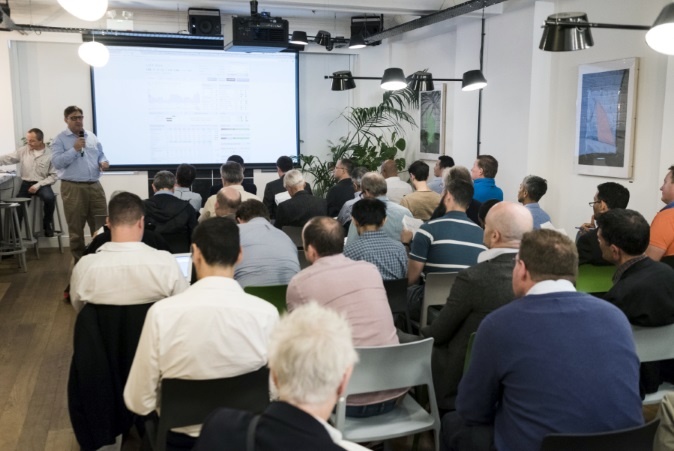
Last week I had the privilege of hosting the first Stockopedia StockSlam in Central London. The idea for this was born from a conversation that I had with Ed Croft, at the Mello Investor Show in April, where we lamented the lack of opportunity for the retail investor community to meet and share ideas with each other.
The StockSlam is an event where investors pitch share ideas to an audience of like-minded individuals, in a quick fire fashion. Each pitch is only 3 min long, and there are 10-15 pitches in all, so you get a lot of ideas delivered very quickly, and in quite a fun and unique format. Everyone then stays after the pitches and discusses the ideas while drinking beer and eating pizza.
For this first event we kept the numbers intentionally small with a venue large enough for 50 people - which is probably why tickets sold out so quickly! It was an enjoyable evening and I think everyone got a lot out of the event (judging by people's comments) and I'm not just talking about the free food and refreshments (generously provided by Stockopedia, thank you!). No it was the range of interesting new stock ideas and, for me, the new friends that I made during conversations afterwards which really made the night.
However, I know that not everyone who wanted to come was able to, so in order to share some of the value from the event with the rest of the community, I thought I'd write up some notes from the stocks that were pitched.
Please note: these are contemporaneous notes from the event and a pretty dodgy transcript courtesy of Ed's audio recording. So if I've misquoted anyone's pitch, I apologise in advance and please contact me so I can update the post!
In order of the pitches delivered (with the first being my pitch to get things rolling):
Clipper Logistics (LON:CLG)
- Boohoo engaged them to provide warehousing for PrettyLittleThing
- Been in logistics business for 25 years with an excellent client list (ASOS, Marks & Spencer, etc)
- Have a successful, growing exposure to online retailing with some unique services
- One of these is Boomerang which deals with the 25-40% of total online sales which the customer returns
- Works best when integrated into customer systems which makes their business quite sticky
- Open book system means that costs and benefits are shared with clients to the benefit of both sides
- This gives Clipper good visibility of earnings
- Founder still owns 25% of the business which is enough to remain keen but not so much that he has control
- Shares have multiplied by 4x in 4 years since flotation so they're not cheap but they do seem to be decent quality
Lok'n Store (LON:LOK)
- There is a massive tailwind for self storage as people have less spare room at home
- The industry is huge in the US where there are 50,000 facilities (out of 60,000 globally)
- In other words there are 165 facilities for every million Americans
- Australia is the next biggest market with the UK and then Europe following behind
- The big brands here are Safestore and Big Yellow
- Both have about 6.2m sq ft of storage space and achieve 85% occupancy
- Lok and Store have a lower occupancy of around 72% so the metrics aren't as great
- Business was built by an investment banker who saw it as money for old rope and he still owns 20% of the company
- Another 30% is owned by the management with other smart investors holding significant stakes
- Investment case is that Safestore is up by 25% in the last year and sits at 66% premium to NAV
- Similarly Big Yellow is up by 16% and sits at a 55% premium to NAV
- In contrast Lok and Store has fallen by 10% and is valued at no premium to its assets
- The upside is that Lok and Store could get re-rated and in the meantime you have some excellent management
DP Eurasia NV (LON:DPEU)
- This is the Domino's Pizza master franchisee in Turkey and Russia
- It has 643 stores, up from 80 ten years ago, and can double in next 8 years
- 80% of the stores are in Turkey, 20% are in Russia and 63% are franchised
- Market leader in Turkey and 3rd in Russia
- In these markets there remains a lot of potential growth runway
- Two types of stock: rebounders and compounders. The rebounders are those which are very cheap and might jump up in price. The compounders are able to reinvest at a high ROCE. DP Eurasia could actually be both - a rebounding compounder!
- The StockRank is 21 and the value rank is poor
- The P/E for 2019 is ~15 but the company is becoming more profitable as it grows
- Price is 22% off from the IPO as the Lira is down and there's political instability in Turkey
- Net debt to EBITDA is 1.1x and group can fund growth through cash flow so net debt should fall
- Founder been 21 years in business and still owns 5>#/li###
- Could lose your shirt, and everything else, but lots of space to growth and be a compounder
Versarien (LON:VRS)
- One of the most unique companies in the world
- It's an advanced materials company taking IP from universities and commercialising it
- There are lots of legacy companies in the business which they use to fund their new development
- Principally this is in the area of Graphene although there are other materials like Boron Nitride
- Graphene has unique benefits when you add it to other materials making them stronger/lighter/flexible/conductive
- It completely transforms polymers, plastics, resins etc and so it's the most disruptive material out there
- UK government is interested in the development and has invested billions into infrastructure so that production can scale up
- Big companies are talking to Versarien such as Unilever and Continental Tyres
- When you look at the stock ranks you're looking at the legacy businesses
- Versarien is on the cusp of monetising graphene at a commercially scalable level
- Currently the graphene business runs at 90% margin and costs £100 per gram
- For something like aerospace this price needs to come down to £10 a gram
- With just China looking for about 54,000 tons in 2021 alone this is like the fourth industrial revolution!
Direct Line Insurance (LON:DLG)
- It probably won't do exciting things but if you're interested in income it's worth a look
- Stockopedia only shows the regular dividends but DLG also regularly pays special dividends
- Recent total dividends and yields are 50.1p 14% (2015), 24.6p 7% (2016) and 35.4p which is 10% (2017)
- Key features are the strength of its brands with Direct Line not being on price comparison websites
- Also has Churchill and Privilege which are on those websites
- There's a secret sauce around how these special dividends occur and that requires knowing the insurance business
- You don’t know how long the claims will take to come in and so you have reserves to cover these claims
- But when claims come in that are lower than the reserves then remaining cash can be released for special dividends
- DLG used to be RDX and in those days it wasn't particularly prudent about its reserves
- But since floating it has been and generally its been able to release reserves every year
- Another characteristic is that it's weakly correlated with market cycles and the beta is 0.45
- So what's not to like if you're looking for income?
Beeks Financial Cloud (LON:BKS)
- This company presented in Derby and there's a great website video at PIWorld.
- They provide servers linked to trading computers which they rent out for algorithmic trading
- This covers FX, bonds, equities and now crypto-currency as well
- Their USP is that they have spent time getting capacity into the exchanges so latency is very low
- This is a competitive advantage, replicable, yes, but it’d take a competitor some time to copy it
- Very recent IPO with interim results in Feb and so Stockopedia is not up to date
- For example they actually have around £3.8m cash now
- The founder still owns 65>#/li###
- He thinks that there's scope for 10,000 clients and another USP for them is speed to market
- Since algorithms don't last for long you need to be able to deploy and use it very quickly
- With Beeks a trader can be up and running inside an hour (compared to weeks for installing your own server)
- One slight doubt is that this year’s numbers are pretty demanding with a P/E of 40 for 80p of earnings
- Still a high quality business
Marks and Spencer (LON:MKS)
- When I first looked at this company I assumed it was an absolute pile of crap!
- What I discovered is this is an interesting, highly cash generative business
- It's reported that M&S are closing 100 stores and this is a bad thing
- Actually if they are only closing loss making stores then the profits will go up
- Archie Norman, who turned around Asda and ITV, is now chairman of M&S
- If you ignore the press and read the last RNS it's very apologetic. They're doing everything wrong with terrible logistics and food which isn't sold online. This tells you that there's lots of potential upside!
- It has £1.8bn of debt but it's also stuffed full of freeholds although they deliberately obscure how many they have
- Menswear is getting there, everyone knows the clothing is terrible but demand is elastic so if you reduce prices by 30% then volume doubles
- The food sells itself even if it isn't online
- Just look at the cash flow statement; it's throwing off enough cash to sustain the 6.2% yield
- Ignore the journalists; this'll probably get sold to Amazon for twice its current price!
Harvey Nash (LON:HVN)
- This is a small-cap, £84m market cap, company in the recruitment sector
- Ed Croft will say that there are two types of stocks with QV (Quality Value) or VM (Value Momentum) being the two best pairs
- This is a VM pick
- I really hate the sector with low profit margins and it's very cyclical
- It is growing at the top and bottom line
- It's also profitable with a terrible operating margin but very good ROCE
- They have great asset turnover; it may be a rubbish business but they are making decent cash
- Cash flow has also been very strong with 10% cash flow yields, maybe 10% plus
- Geographically they are based in Northern Europe which are places with low unemployment. Companies are struggling to find techies for example as they'll just go down the road for twice the money.
- Harvey Nash actually specialise in techies which is a growth business
- Also Gervais Williams is in it and so there's half a chance of getting this right
- If it breaks 125p, it’ll probably go to 200p - fill your boots!
Inspired Energy (LON:INSE)
- This is a company that provides energy consultancy services. Advice to small or medium enterprises on their consumption of utilities. Very similar sector to Utilitywise!
- Stockopedia sees it as a neutral, an adventurous stock with high quality and a StockRank of 79
- Operating margin is 18% and ROE is in double digits
- This is a very high quality, very profitable business
- Momentum is a little bit weak at the moment as share price of this company does tend to only move on results this time of the year and June half-year
- They tend to put out some AGM statements and the AGM is on the 25th of June so we should have an information update in the next couple of weeks
- The forward P/E ratio is 10 and the growth ratio is just 0.3 on a consensus forecast for 1.6p in 2018 and 1.8p in 2019
- Pays a 3.7% yield
- There are two parts to the growth of this company: organic growth and acquisition growth
- Organic is very strongly correlated with the order book which is always reported on in the results
- Last few years the order book was £14m (2015), £24.5m (2016), £28m (2017) and £39m (2018)
- If you look at the EPS it really does follow the order book change very closely
- It also makes bolt on acquisitions with some modest recent ones (£2m and £4m) paid mainly in cash
- One takes them into the water business while the other was one of their software suppliers
- There are two downsides: a horrible LTIP with dreadful adjustments plus too much debt in the business
- Still high quality and cash generative
Allergy Therapeutics (LON:AGY)
- In my search for that elusive 10-bagger I've found this £160m AIM small cap biotech company
- People with allergies are the target market; 30% of Europeans have an allergy to grass so they are going after a colossal market
- There are many treatments but most of them treat the symptoms rather than curing the underlying problem
- They have a cure and a product which is in the marketplace - with 50,000 patients in Europe on a named patient basis
- For the US market they need to get full FDA licensing and are going through various trials
- Have good phase 2 results and phase 3 should occur in 2019
- The next phase is fully funded due to a fundraising last year for £25m
- So it’s a fully funded opportunity with the first cure for an allergy going into the US market
- Another little bit of information is that unlike treating symptoms, each allergy that you're suffering from is specific
- So once you've got the licensed product it's a massively defensible niche with other allergies to target
- It was generating profits before 2015, before it started to get FDA approval
- It did do £64m last year and is growing quarterly on a very constrained basis
Disclaimer: All of the information presented here is purely for educational and entertainment purposes and is not a recommendation of any of the shares mentioned.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
15 comments
Looking more closely at DP Eurasia NV (LON:DPEU) and the reality is that nearly all of its profit comes from Turkey at the moment. If there was a financial implosion in Turkey this would have a significant knock on effect. There are also currency risks given that some of the debt has been denominated in euro terms. The current leader of Turkey seems to be bonkers to me. So my best guess is that Turkey is heading towards a financial/economic crisis in the medium-term.
https://www.chathamhouse.org/expert/comment/turkey-road-severe-economic-crisis
Thanks for the write-up, it sounds like it was a great event. Would love to attend the next one - especially if there's beer and pizza!
Funny that you should say that - the next one is on 26th July: https://www.stockopedia.com/content/stockopedia-stockslam-on-26th-july-2018-381604/
Hope to see you there (beer and pizza included)!
In case of interest DP Eurasia NV (LON:DPEU) first half trading update out today. On face value it looks reasonable given issues in Turkey. The company remains on track for full year EBITDA profit but this is in Turkish Lira terms. The currency has slumped against sterling over the last year. However, the underlying business appears to be performing well with a strong like-for-like sales result in H1 2018.
Hi, I looked into Direct Line Insurance (LON:DLG) after reading this article and liked what I saw so I compared it to Aviva (LON:AV.) which is a very similar company. Direct Line Insurance (LON:DLG) has much higher quality ratios and a better dividend policy which justifies its slightly higher PER but Aviva (LON:AV.) has a -11bn enterprise value. Would an experienced investor be able to help a relative newbie by explaining why I wouldn't go for the dividend paying company with more cash reserves than the market cap?
Great idea, thanks for sharing, would be interested in attending in future.
How about next time you have to do the StockSlam after 5 beers!
DP Eurasia NV (LON:DPEU) - Perhaps worth pointing out that the forecast P/E for 2019 is now 16.4X. Looking at it and clearly the slumping Turkish lira is having a big impact. Probably worth using a rough P/E of 18X for 2019 to factor in disruption from the Turkish election this month etc.
Out of all the stocks I am not sure which I would go for. Clipper Logistics (LON:CLG) doesn't look to bad and is a reasonable quality business. That and DP Eurasia NV (LON:DPEU) might be my picks. The other stocks could be good but would need some more work to figure out. DP Eurasia NV (LON:DPEU) I would look to be cautious on though.
thanks Damian and Stockopedia for organising the event. It was my first attendance to such meeting and is a great learning experience.Now that I met in person, I can put a face to a name.
Great format and length is absolutely bang on... Eagerly looking forward for future events and happy to volunteer for any activities.
BTW - is it possible to share the names of the presenters ? reason being spoke to couple of them but missed their id's. Would be great to connect with them offline.
also posting a snap with Ed and Paul.
Thanks tripuram. Great photos and I'm glad that you enjoyed the evening. I would have shared the presenters names but apparently we said that we'd keep them private. That said I'm happy to add any presenter name to the article if they let me know that this is ok.
Great post Damian, thanks for sharing for those who could not attend.
hmmm, I think I will try and attend a future one. Not London based though, so a little tricksy but do-able.
Great writeup thanks Damien. I note you got the good points and the bad points that people highlighted for the stocks. This is great as I am not a fan of just highlighting the positives. Every stock has lots of things that could go well and usually some positives. I think drawing an overall balanced view is much better and has more credibility. Will be interesting to see how these stocks perform. I guess the only thing that might be adde is the share price on the day they were pitched. Just so people have a reference point. However, I can see that this might create a bit of pressure for the pitchers and could give the impression that these are recommendations. I don't see them like that. They are really just ideas for possible further research.
Thanks ratioinvestor. We asked the presenters to cover both the positive and negative aspects of their choice for exactly the reasons that you mention. I think that there would be no harm in putting the share price into the follow-up report (I'll edit this one shortly) but it's probably not necessary for the presentations themselves since they really are a starting point rather than a conclusion!
Damian
@damian - I thought it was a great event - both for the ideas but also for the networking. There were a lot of links made between different investors. Great to see people like Ed Shing and Paul Scott connecting in the real world. I counted about 40 there on the night, which was probably about right. It might be worth us trying a larger number and seeing if it still feels intimate.
I actually think the 3 minute format was absolutely spot on. I know some presenters wanted 2 more minutes, but 3 minutes was perfect for keeping the audience attention. Another 2 minutes each would extend the length of the presentations by 66% - and people's minds might wander off. It felt very bang, bang, bang !
Thanks Ed. I think that the format worked very well for a first event. Thanks so much for kindly sponsoring it - I'm looking forward to the next one now!
OK that's weird - got a double post.
Thx Damian ..they’re all interesting & I appreciate the write up