StockRank Movers - Feb 17: End of the house party?

Is the party coming to an end for UK house builders? House prices are still increasing, but recent figures from the Office for National Statistics suggest that the pace of increases could be starting to decline. This trend could be influenced by several factors, including stricter mortgage rules, as well as expectations that interest rates could rise after the general election. This could be bad news, but the market sometimes overreacts to bad news, thereby causing good quality stocks to become undervalued. Is this happening to stocks in the house building sector? Lets take a look at their StockRanks to explore further.
Barratt Developments (BDEV)
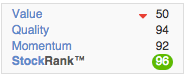 Barratt Developments (BDEV) has a StockRank of 96, compared to 87 in September. However, cyclical companies like house builders tend to slow down when they start to compete for land, labour and materials - pushing costs up and profit margins down. Indeed, Barratt's annual report noted that build costs have ticked upwards. The firm 'saw some upward price pressure on materials, in particular for bricks and timber.' Furthermore, a 'shortage of skilled labour did increase costs, with bricklaying the most affected area.' It is also important to note that although earnings did grow by more than 100% in 2014, Barratt's ValueRank has fallen to 50 - suggesting that the earnings growth may be factored into the share price.
That being said, Barratt's operating profit margins have actually increased from 6.3% (2013) to 13% (2014), while the Return on Capital Employed (ROCE) has more than doubled, from 4.5% (2014) to 10.3% (2014). Furthermore, Barratt plans to build over 2000 new homes in Scotland in order to meet strong demand, while brokers expect earnings to grow by another 25% over the next twelve months. To round it off, Barratt's recent trading statement noted that 'consumer demand across all of our regions has remained robust'. The management team insists that the company 'is on track to deliver a further significant improvement in performance in FY15.'
Persimmon (PSN)
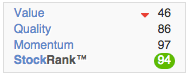 Persimmon (PSN) has a StockRank of of 94, although the ValueRank has fallen to 46. Interestingly, at the start of January Jefferies (the brokers group) issued a research note saying that 'we are no longer recommending that investors buy any of the UK residential-linked shares under our coverage'. Why? They believe that 'weak house price data and lower UK growth will lead to share price weakness in the UK residential sector.' How did the market respond to this note? Persimmon's share price has actually beaten the market by 8% over the last month and the EPS forecasts for 2014 have increased from £1.18 (December) to £1.20 (February).
So why is the market so optimistic? The company released a bullish trading statement last month, noting an 'increase of 17% in legal completions to 13,509 new homes', while 'full year revenues increased 23% over the prior year to £2.6bn'. Brokers expect earnings to grow by more than 20% over the next twelve months, while Persimmon retains a P/E ratio of 16. This would give the company a low PEG ratio (0.76) and could perhaps suggest that the company is still a solid growth stock trading at a reasonable price.
Persimmon's recent trading statement insisted that 'we remain confident of a further improvement in operating margins for the second half of the year which will underpin significant growth in pre-tax profits and excellent cash generation for the year ended 31 December 2014.'
What does the future hold?
So interest rates may rise after the election. However, it is important to remember that interest rates could rise as a result of sustained economic growth, which would of course drive demand for new homes. Furthermore, house builders may also benefit if the Government decides to address the housing shortage in the country. As always - these are not share tips and should not be read as investment advice. Please do your own research before investing.
If you want to track the companies that are moving up, or down, in the StockRanks, do please feel free to test our StockRank Portal, here: http://www.stockopedia.com/stockranks/
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
18 comments
Yes good results but I think that was already in the sp, it has gone up a bit today, I'm still holding but have sold some others recently. I think you are right but there are several other negatives, house prices are not rising so much now esp. London so growth will not be so fast, als labour costs have increased considerably recently, so profits will be squeezed. Yes I think you are wise to take some profits, Im holding on for special divi but if sp hits 550 I may bail out.
Very good results today from Barratt Developments (LON:BDEV) with EPS for last 6 calendar months of 2014 up 79% compared with same period in 2013. Yet the share price is going down. I have just sold my holding because I think the following factors are affecting the share price:
1) Worries that interest rate rises are on the horizon and this will increase mortgage payments and reduce sales of new houses.
2) Uncertainty about the general election and who will be in control of a likely hung parliament.
3) We are getting rather late into the economic cycle to be buying (or maybe even holding) shares in the Consumer Cyclical sector. (For some reason Barratt Developments is listed as being in the
Financials / Real Estate Operations for sector / industry, whereas all the other house builders are shown in the
Consumer Cyclicals / Homebuilding & Construction Supplies sector / industry.)
Yes good results but I think that was already in the sp, it has gone up a bit today, I'm still holding but have sold some others recently. I think you are right but there are several other negatives, house prices are not rising so much now esp. London so growth will not be so fast, als labour costs have increased considerably recently, so profits will be squeezed. Yes I think you are wise to take some profits, Im holding on for special divi but if sp hits 550 I may bail out. - See more at: http://www.stockopedia.com/content/stockrank-movers-feb-17-end-of-the-house-party-92346/?submitted=17#17
Thanks for the article and comments. All very helpful. As a newbie to Stockopedia,could I ask you Ed to elaborate on your comment re BDEV: "The momentum is strong and while I certainly wouldn't want to initiate a position at these levels"? To me, looking at BDEV's Stock Report in isolation, based on all the "green" lights, scores, broker recommendations etc, does it not suggest it might be a good time to "initiate"?
I understand the need for deeper research, also the Value ranking hints at potential overvaluation, but it would be useful if Ed's conclusion was somehow more apparent from the Stock Report. This begs the question as to whether I am missing something from my interpretation of the stock report?
I think he means the value is not so good now, if you have the shares then hold but for buying more then no. As for brokers quite a few have gone negative on valuation grounds. I feel momentum is losing steam and I would not be surprised if there is a fall soon. As I said before there are a few things going against housebuilders at the moment.
In results I think profits will be up, but rate of growth will be down, this has already been stated in trading statements which is why the sp fell a few weeks ago.
I have read that the best quarter for housebuilders in terms of sp going up is December - February, has gone up average of 8% over last 5 years, only 1 year it went down, this year looks like being the same. So Im reducing my holdings as feel Im overweight in that sector, just sold PSN and BVS, will sell TW and maybe BDEV, then have a look at them after the election. But I don't think housebuilders are bad, profits still growing but maybe not so fast, there is plenty of demand for houses, but future less certain, maybe interest rates will rise at year end and labour costs are rising.
Motley Fool suggested there was short interest in Berkeley (BKG), but I could find no evidence t back this up.
Thanks Ed, I mention it as short interest in the London exposed house-builders is growing.
"I mention it as short interest in the London exposed house-builders is growing."
That's funny as I have just called up the latest FCA short report and there is not a house builder on it apart from Galliford Try which also has a construction arm. So not sure what the basis for your above statement is?
Hi Jjis, thanks for highlighting, I shouldn't believe all I read on the internet. In my amateur state I did not even know about the FCA disclosure list! Berkley Group is on the list.
Oh yes quite right I missed it the first time I scanned the list sorry - makes sense as London seems quite frothy I guess and Odey is bearish.
Galliford Try (LON:GFRD) reported today...
"Record results and excellent progress on our disciplined growth strategy to 2018.
Interim dividend up 47%, reflecting our strong performance."
Despite all the management speak in the reports of these builders there is a common theme of self-belief. Putting aside our natural prejudices against any further development in "our neck of the woods" there does appear to be furjter growth and comfortable dividends to be had from several of these companies.
Hi Ed, are there any good empirical studies looking at share price change in relation to short interest in a stock? So percentage of cases where price increases/decreases, whether those outcomes differ by QVM factors etc.
Hi underscored - we've read all the research we could gather on short interest in stocks. We are still working on our Smart Money add-on to the site which is going to be awesome, but it's still infuriatingly delayed. You can read the Short selling chapter in our ebook which may help and offer references www.stockopedia.com/books/smartmoney/
Shanklin - Yes if the earnings and cashflow of the historic numbers that constitute the ValueRank rise then the P/E and P/CF will 'fall' accordingly. So the stock may look cheaper on that basis - just remember during results season all companies are reporting, and ranks are relative rather than absolute - so overall ranking changes depend on the rest of the market.
We've argued a lot internally about whether to add forward looking (forecast) numbers into the ValueRank. While the overall ValueRank could perform better on a standalone basis if we did, the correlation with the momentum rank would increase. We're currently comfortable with the blend of the backward looking Value Rank and the forward looking Momentum Rank in the overall StockRank - nothing is sacred though!
Hi Ed
BDEV and PSN are both just about to report results and forecasts suggest earnings will have grown strongly. Given the V metric is backward looking, presumably it is likely to improve significantly, certainly on the P/E component?
I have the same issue with BVS so would appreciate your thoughts.
Cheers, Martin
I think the housebuilder stock journey has been a classic example of how the style of a trade can change over the course of several years. Back in 2011 these stocks were flagged as Ben Graham bargains in a great article by Ben Hobson on this site - coming up on early versions of the Stockopedia screens. Barratt Developments (LON:BDEV) was trading at £1 per share back then - it's since more than quadrupled in price with strong rises across the board in the other stocks.
Back then these were pure play contrarian value stocks with much negativity about the outlook and rock bottom valuations. These days they are looking more and more like momentum trades - with brokers constantly upping numbers as can be seen in Persimmon's broker trend below. The valuations today, while not stretched versus the rest of the market, are certainly at a premium versus the long term trends for these kinds of cyclical stocks which is something to bear in mind.
Personally I am long of £PSN , £BDEV and £TEF . I highlighted the sector back in the October Investor shows as some of the highest ranked on the Stockopedia StockRanks. Since then the housebuilders have added 15-20% almost across the board. The momentum is strong and while I certainly wouldn't want to initiate a position at these levels I will continue to run the holdings until I see a marked change in sentiment and fall in the ranks. As Jesse Livermore once said "it was never the thinking that made the big money for me, it was always the sitting" - or something along those lines.
I dare you to take a look around SW8, particularly Nine Elms Road? According to this FT article from January (http://www.ft.com/cms/s/0/79196466-a576-11e4-ad35-00144feab7de.html?siteedition=intl#axzz3S1omlicc,) there is currently 10 YEARS of "luxury-prime" supply currently in construction within London! Whilst I do not believe the future to be predictable I am expecting exposed home builders share-prices to produce the classic Turkey before Xmas weight distribution. UK Housebuilders are on my bargepole list along with their booming suppliers such as Energy Technique (LON:ETQ).