The Week Ahead (25 – 29 May): US GDP, UK House Prices, Pets at Home, Hollywood Bowl

An uneventful week for the major indices, most of which rose by one or two per cent, but if my portfolio is any guide, it does feel like some of the animal spirits have returned to UK small caps, at least with companies that are performing well in difficult market conditions.
Ed published an update to his popular clear trends strategy. This has the benefit of both a strong academic backing and now two sets of stocks that have materially outperformed. As Ed pointed out in the article:
The May 2024 "Didn't buy Warpaint?" portfolio is up 71% against the FTSE All Share's 22%. The June 2025 "Didn't buy Rolls-Royce?" list did it again - +30% in just eleven months vs +15% for the FTSE.
This doesn't mean that the current set will generate similar returns, but several stocks on the list have got off to a good start with positive news this week:
- Luceco (LON:LUCE) upgraded expectations following a strong Q1;
- Keller (LON:KLR) reported a strong start to the year in its key North American business; and
- Goldplat (LON:GDP) reported higher PBT for the first three quarters than their broker is forecasting for the Full Year, despite having upgraded expectations a couple of months ago.
It's not been all plain sailing, though, as the list contained two Palm oil producers, M P Evans (LON:MPE) and AEP Plantations (LON:AEP). These have trended higher over the last year due to a large rise in Palm Oil Kernel prices and multiple expansion, as investors re-rated previously modestly-priced stocks. However, the news this week that Indonesia is considering centralising control of commodity exports to boost state revenues and improve oversight of the country's natural resources has taken 25% out of the share prices and broken those previously smooth upward trends.
These moves highlight that with these sorts of strategies, holding a basket of stocks is the way to get exposure to these effects. It also avoids suffering too much from company or sector bad news, which no chart pattern can consistently predict.
Here's what we can look forward to next week:
Economic Calendar
Monday 25 May |
UK/US Holiday |
|
Tuesday 26 May |
||
14:00 |
United States |
Case-Shiller Home Price |
15:00 |
United States |
Consumer Confidence |
Wednesday 27 May |
||
12:00 |
United States |
MBA Mortgage Rate |
15:30 |
United States |
Crude Oil Inventories |
Thursday 28 May |
||
10:00 |
Euro Area |
Economic Sentiment |
13:30 |
United States |
Continuing Claims |
15:00 |
United States |
New Home Sales |
Friday 29 May |
||
06:00 |
Japan |
Consumer Confidence |
07:00 |
UK |
Nationwide House Prices |
13:00 |
Germany |
Inflation Rate |
US GDP
When investors read about GDP figures, they often treat them as definite numbers, just as a company's balance sheet typically contains final, certain values. However, GDP is calculated from census and survey data from government entities, trade groups and economic organisations. The key components of the estimate are Consumer Spending, Business Investment, Government Spending, and Net Exports. Given the necessary trade-off between speed of reporting and accuracy, multiple revisions of the GDP figures are released.
The initial "Advance" GDP estimate relies heavily on tracking surveys for the first two months of a quarter, then uses statistical modelling to project the third month. Despite this uncertainty, the market typically puts more weight on the initial estimate. So, unless next week's Second Estimate for US GDP comes in significantly different to the first, this is unlikely to be market-moving. The first snapshot reported US Q1 GDP growth at 2.0% annualised. Expectations are for this to be nudged up to 2.2% annualised in the second estimate. However, a few specific factors make this particular revision much more unpredictable than usual. The biggest is, of course, a massive escalation in geopolitical tensions in the Middle East, which sent crude oil prices swinging wildly. This introduces two major blind spots into the initial GDP calculation: the Trade Balance and Inventory Accounting. The market may not be forgiving of a large revision, especially if it is downwards.
UK House Prices
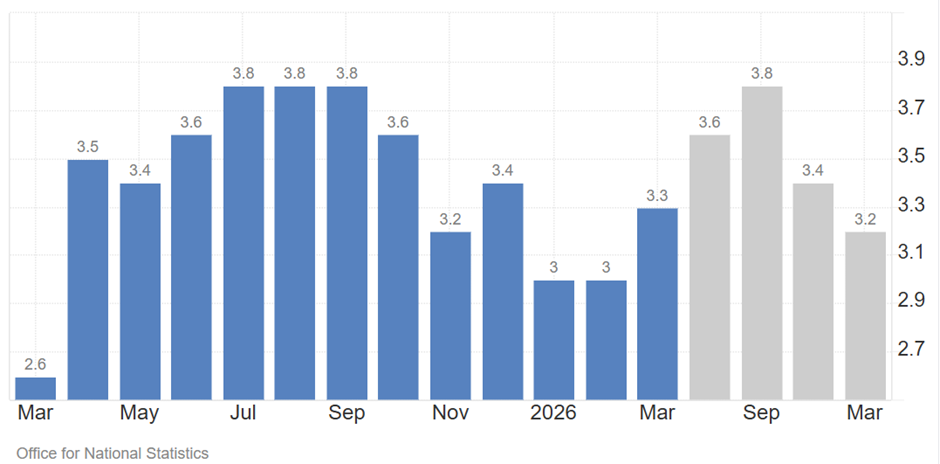
Given all the market doom and gloom for UK housebuilders and the whole building sector, when I previewed the Nationwide House Price Index last month, I thought the forecast 2.2% number for April looked optimistic. When the figure was released, it actually came in at 3.0%, beating expectations. There goes my burgeoning career as a macro forecaster!
However, even this number is below forecast inflation:
[All charts in this section: Trading Economics]
And like any good macro forecaster, I'm not going to be put off by past failures; I'll have another go at making the same prediction. The market's rather sanguine view of the impact of current interest rates on house prices seems incongruous to me. For example, the UK 5-Yr (from which 5-yr fixed mortgage rates will be priced) is hitting a level that contributed to negative house price changes in 2023:
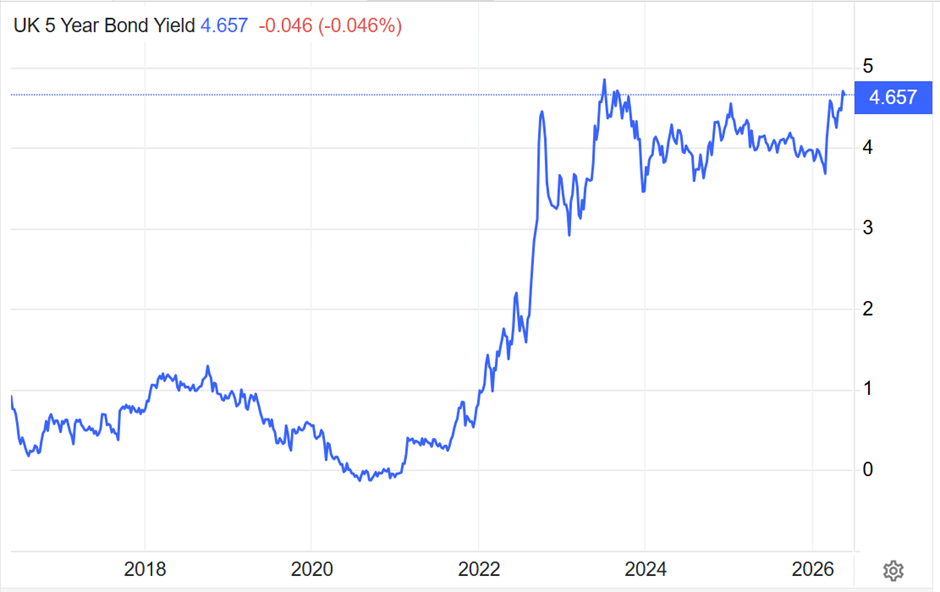
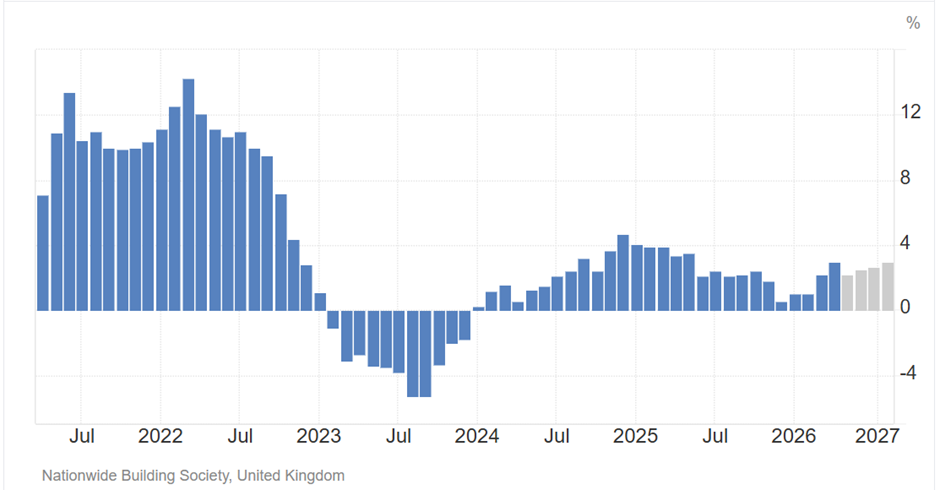
Either way, it seems to me that either the market forecasts for house prices are wrong, or the stock market pricing of the impact of higher rates on the likes of housebuilders is wrong. This is what makes these data points particularly interesting at the moment.
Companies Reporting
| Date | UK Trading Updates & AGMS | UK Financial Results | International Financial Results |
|---|---|---|---|
Monday 25 May |
UK Bank Holiday |
US Memorial Day |
|
Tuesday 26 May |
88 Energy (LON:88E) (AGM) Alt Resources (LON:ALTR) (AGM) Alt Resources (LON:ALTR) (AGM) DCI Advisors (LON:DCI) (AGM) |
Atalaya Mining Copper SA (LON:ATYM) (Q1) Clorox Co (NYQ:CLX) (Finals) Diaceutics (LON:DXRX) (Finals) Kingfisher (LON:KGF) (Q1) Nostrum Oil & Gas (LON:NOG) (Q1) |
Modine Manufacturing Co (NYQ:MOD) Zscaler (NSQ:ZS) |
Wednesday 27 May |
accesso Technology (LON:ACSO) (AGM) Aptitude Software (LON:APTD) (AGM) Baillie Gifford China Growth Trust (LON:BGCG) (AGM) Bodycote (LON:BOY) (AGM) WAG Payment Solutions (LON:EWG) (AGM) GreenRoc Strategic Materials (LON:GROC) (AGM) Princes (LON:PRN) (AGM) Red Capital (LON:REDC) (AGM) RTC (LON:RTC) (AGM) Xaar (LON:XAR) (AGM) Zotefoams (LON:ZTF) (AGM) |
Hollywood Bowl (LON:BOWL) (Interims) B.P. Marsh & Partners (LON:BPM) (Finals) Greencore (LON:GNC) (Interims) HICL Infrastructure (LON:HICL) (Finals) Pets at Home (LON:PETS) (Finals) Watkin Jones (LON:WJG) (Interims) |
Agilent Technologies (NYQ:A) Best Buy Co (NYQ:BBY) Salesforce (NYQ:CRM) Dicks Sporting Goods (NYQ:DKS) Dycom Industries (NYQ:DY) Heico (NYQ:HEI) Hudson Pacific Properties (NYQ:HPP) PDD Holdings (NSQ:PDD) Synopsys (NSQ:SNPS) Williams-Sonoma (NYQ:WSM) |
Thursday 28 May |
Air Astana AO (LON:AIRA) (AGM) Air China (LON:AIRC) (AGM) CT Private Equity Trust (LON:CTPE) (AGM) Ebiquity (LON:EBQ) (AGM) Glencore (LON:GLEN) (AGM) Petro Matad (LON:MATD) (AGM) Pagegroup (LON:PAGE) (AGM) Pulsar (LON:PULS) (AGM) Roebuck Food (LON:RFG) (AGM) Property Franchise (LON:TPFG) (AGM) Vesuvius (LON:VSVS) (AGM) |
Harbourvest Global Private Equity (LON:HVPE) (Finals) Iqe (LON:IQE) (Finals) Johnson Matthey (LON:JMAT) (Finals) SSE (LON:SSE) (Finals) |
Autodesk (NSQ:ADSK) Burlington Stores (NYQ:BURL) Dell Technologies (NYQ:DELL) Dollar Tree (NSQ:DLTR) Hormel Foods (NYQ:HRL) NetApp (NSQ:NTAP) Okta (NSQ:OKTA) |
Friday 29 May |
Ariana Resources (LON:AAU) (AGM) Aseana Properties (LON:ASPL) (AGM) Blackrock Latin American Investment Trust (LON:BRLA) (AGM) Canal+ SA (LON:CAN) (AGM) Churchill China (LON:CHH) (AGM) European Metals Holdings (LON:EMH) (AGM) |
Beowulf Mining (LON:BEM) (Q1) |
With bank holidays in both the UK and the US on Monday, it is a pretty quiet week for planned results on both sides of the pond. The UK newsflow continues to be dominated by AGMs, which often have accompanying trading statements.
As usual, let us know via the comments if you think we've missed anything of note.
Pets at Home (LON:PETS)
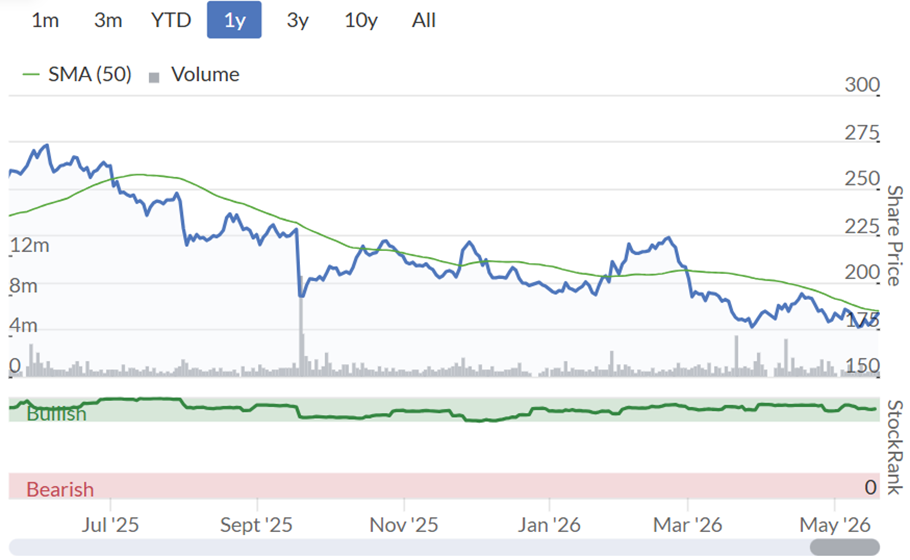
Pets at Home will release its Full-Year Results on Wednesday. The key metrics are already known, as they provided a highly detailed pre-close trading update. Overall, the market views this as a business that is struggling to make headway:
Underlying PBT is expected to come in around £92m, down significantly from the £133m reported in FY25. Net Debt is anticipated to sit at around £20m, following £85m returned to shareholders via buybacks and dividends over the year.
The group's performance this year highlights a widening gap between its retail shops and its veterinary division:
- Retail is expected to deliver £30m PBT, less than half of 2025's £72.9m. The business invested heavily in price reductions across 1,000+ food products and achieved £20 million in overhead cost savings. However, the retail arm returned to positive volume growth in the second half of the year, with Q4 like-for-like (LFL) sales improving sequentially over Q3.
- The Vet Group continues to be the star player and is expected to grow PBT to around £83m from £75.9m last year. Performance remains incredibly resilient, driven by higher average transaction values and sticky, predictable subscription Care Plan revenue.
Pets at Home is rebalancing its capital allocation. They are rebasing their dividend to a 50% payout ratio and putting the rest into an expanded, aggressive share buyback program. The explicit size and timeline of this new buyback tranche could move the market.
Investors should also keep an eye out for management commentary regarding the CMA investigation into the UK veterinary services market. In their pre-close update, Pets at Home welcomed the final decision report and firmly stated they expect zero adverse impact on their growth strategy. Any further reassurance here will be a relief.
For FY27, management has already signalled comfort with consensus expectations for underlying PBT of £99m, supported by an 80% hedge of their energy and foreign exchange requirements. No doubt, a walking down of expectations by brokers over the last 18months contributes to that comfort:
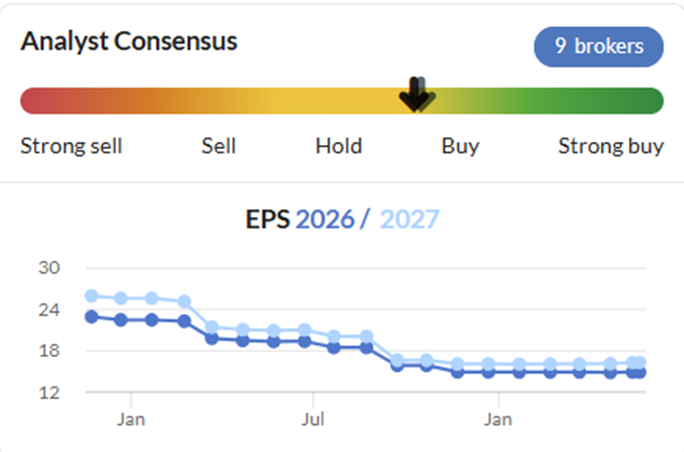
As usual, outlook may matter more than the specific results, which have been heavily trailed.
Hollywood Bowl (LON:BOWL)
Hollywood Bowl also releases results on Wednesday. In this case, their interims. Much like Pets at Home, the company has already provided a detailed first-half trading update showing revenue up 9.5% to £141.5m, and net cash of £26m.
The business is proving resilient amid broader consumer slowdowns, benefiting from the "affordable luxury" factor as families swap international travel or theme parks for a night out at the bowling alley. However, profitability has not escaped pressures on costs:
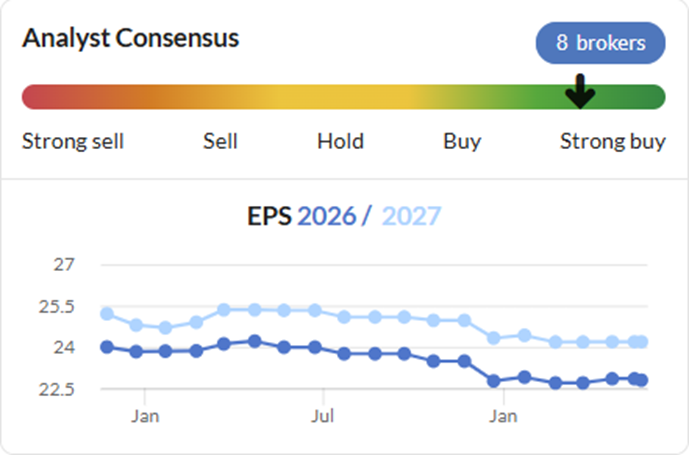
In these interims, the market is likely to focus on profit margins, international rollouts, and the upcoming peak summer season.
- Margins: 76% of the company's energy needs are hedged until 2029 (with 12% generated directly from on-site solar panels). However, rising statutory minimum wage costs hit UK leisure operators this spring, and investors will be keen to see what actions have been taken to offset these cost rises.
- International: Canada is the primary growth market, and Canadian revenue jumped 12.8% on a constant-currency basis. However, LFL growth was much more modest at +0.5%. With revenue growth driven entirely by new centre openings rather than existing locations, investors will want to hear whether older Canadian locations can return to growth.
- Summer: The first half of the company's financial year covers the winter and Easter holidays. The second half relies on the notoriously unpredictable British summer. Unlike many companies, Hollywood Bowl benefits from poor weather that encourages indoor activities. Early Q3 trading may be strong, but with a UK heatwave predicted in the next few weeks, expect management to be cautious.
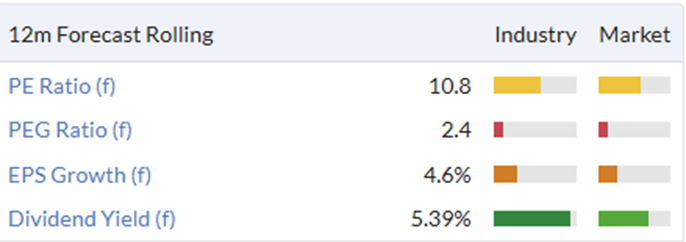
Overall, weather effects tend to normalise, so if the company can work through the period of cost inflation, investors are left with a growing business on a relatively modest rating:
[Disclosure: Mark owns shares in Goldplat (LON:GDP) ]
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

1 comment
Hi Mark, like you I have seen my relatively concentrated portfolio of 26 small caps tick up of late. Not specifically sure why, although with one exception I have avoided profit warnings.
I have decent size holdings in Hollywood Bowl (LON:BOWL) and Zotefoams (LON:ZTF) so fingers crossed my good fortune regarding the absence of profit warnings continues.