Three recovering QM stocks - Games Workshop, YouGov, and Volex

The more I look at various share price charts, the more I see March 19th seems to have been when everything got really cheap. Since then, we have actually seen quite an encouraging rally. Is this based on an improving outlook, or are people just tired of worrying?
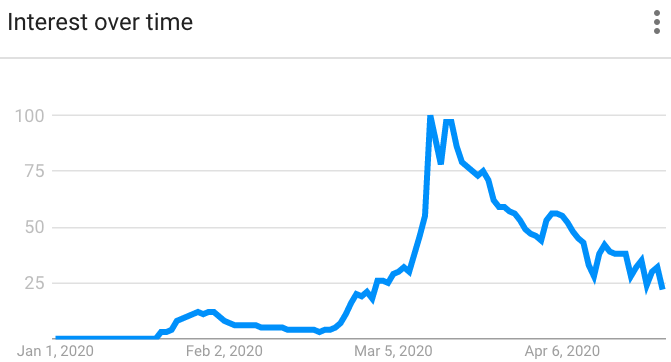
“Panic” is an exhausting state of mind. It can’t be maintained for long because it burns up so much fuel. A quick look at the charts below shows an interesting link between google search terms for “Coronavirus” and the year-to-date FTSE All-Share performance.
Correlation does not equal causation, and I’m not drawing any strong conclusions from the below. It is a surface level comparison, but it does fit the idea that people have got tired of worrying.
Google trends for “Corona”:
FTSE All-Share year-to-date performance:
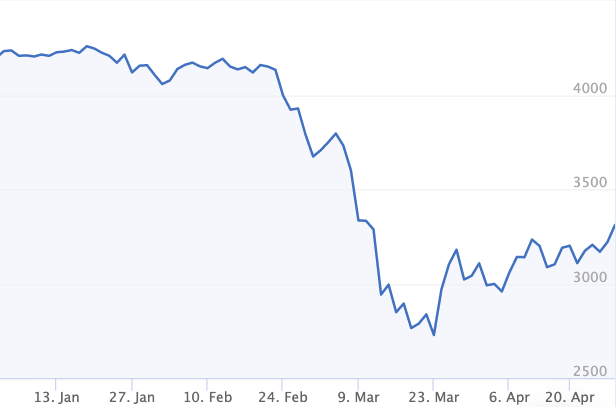
It does seem like Corona panic and market selling both peaked in mid to late March. That kind of high pressure environment can lead to all kinds of unfortunate behavioural biases. While those conditions have passed for now, it is worth considering your plan of action for when/if another Corona-inspired bout of panic hits the market again.
The longer term your outlook, the easier it becomes to see a path through all of this. In the short term though I wonder if we are being complacent - or at least, betting on quite a favourable outcome. Markets are forward-looking, but are they too forward-looking right now?
The risks still remain, and a lot of economic damage has been wrought during this lockdown. There is more poor economic data to come and a tricky normalisation period which, according to some operators, will be even more treacherous to navigate than a full on lockdown. Millions of people are also out of work.
This aside, I do see companies that should be able to survive and even thrive in current conditions.
My (pretty vague) macro view remains something like “on a 10-year view, I believe stock markets will go up therefore I am overweight equities.” Your own investment horizon is a key consideration, obviously.
However, I also feel that the current market conditions are assuming a quite positive outcome and are undervaluing the downside scenarios. That tells me to be prepared for volatility, and to continue prioritising balance sheet health, liquidity, and companies that display a miserly approach to equity dilution. In other words, safe, profitable companies that look out for their shareholders.
Some recent trading updates from promising companies are worth revisiting. In order of release date, we have:
- Games Workshop
- Volex
- YouGov
Games Workshop breaks 6,000p with reassuring update
(Please note that I have a long position in Games Workshop (LON:GAW) )
- Three month relative strength: +13.8%
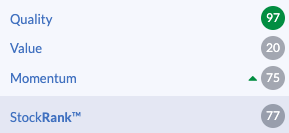
- QM Rank: 95
- Market cap: £2bn
Trading Update - 28 April 2020
Framing is important, isn’t it? “Games Workshop reopens some stores” sounds much better than “the majority of Games Workshop stores remain closed”. There was not much information in this update but the market found it reassuring, with shares up c10% on the day as a result.
Operational update
To recap, GAW closed down its operations on 24 March 2020.
It will now start making trade sales in Europe and North American and online orders will recommence at the start of May.
The majority of stores remain closed but a small number have re-opened in China, the Netherlands and Scandinavia, subject to local social distancing measures.
Financial update
Trading in the nine months to the end of February was in line with expectations. Then, of course, the whole world shut down.
It is now cautiously resuming some operations and expects profit before tax for the year to 31 May 2020 to be no less than £70m. That includes one week of closed down operations. FY21 will therefore bear the brunt of lockdown disruption so I am assuming a hit to profits in the coming financial year.
Valuation
Taking that £70m profit before tax figure and applying the same 19% tax rate as last year, we get profit after tax of around £56.7m. Shares in issue are stable at around 33 million, so that would make for £1.71 of earnings per share, meaning a PE ratio of 34 times. That’s quite punchy.
I’m personally happy to keep holding but I understand if that type of valuation puts others off. If GAW can grow at anything close to its five-year compound annual growth rates (below), then that PE rating will come down in short order. GAW maintains a strong balance sheet with lots of liquidity. Although the group’s recent rates of growth can’t last forever, I think it can take advantage of quite a sizeable IP opportunity.
5Y CAGR (%) | |
Total revenue | 15.7 |
Operating profit | 45.9 |
Net profit | 52.4 |
EPS reported | 51.6 |
I’m not going to pretend these are ideal conditions for Games Workshop. I imagine next year’s results will bear the brunt of lockdown disruption. GAW is highly operationally geared, meaning profits can shoot up and down, so volatility is to be expected.
In the long run though, I think there is a strong growth story here backed up by a literal library of intellectual property that is popular, distinctive, monetizable, and growing all the time.
YouGov - expensive or a world class data insights brand?
- Three month relative strength: +30.9%
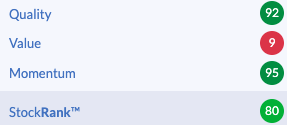
- QM Rank: 98
- Market cap: £734m
Half year results - 22 April 2020
YouGov, like a lot of High Flyers, is always “expensive”. But a high quality candidate can look expensive because the market struggles to price in its ability to generate high returns over a long period of time.
Some of these companies are on their way to being many times bigger than they are today. Is YouGov one such company?
The group published some of this data in a March 24th update. It is reporting the types of double digit gains that you would expect from a stock on a PE rating of 36.7:
- Revenue up 16% to £76.9m
- Adjusted operating profit up 35% to £11.4m
- Statutory operating profit up 13% to £9.5m
- Adjusted earnings per share up 35% to 8.7p
- Cash conversion of 93%
- Cash balances of £27.2m
YouGov’s cash generation and uses of cash are quite encouraging. Net cash from operations has nearly doubled to £15.5m and £15.6m was spent on investing activities. Of this £15.6m:
- £7.4m was spent on acquisitions,
- £4.2m was spent on panel growth and
- £3.5m was spent on technology development
but it’s the outlook statement in these results that is most of interest.
Current trading and outlook
Trading during H2 (1 February to 31 July 2020) “has started positively and is in line with Board expectations for the full year”
Confusingly, the group “has not yet seen any material impact” from the COVID-19 pandemic, but a few clients are requesting payment deferrals or cancellations. So there has been some impact, albeit small - something to be monitored.
That said, the group’s pipeline of sales opportunities for its syndicated Data Products remains strong, it is cash generative, and it continues to roll out its products across geographies.
Responding to COVID-19 and supporting our stakeholders
Being an online company, YOU has an established culture of remote and flexible working. This is one company that should be able to continue operating quite well.
Valuation might be an issue but, as with GAW, its compound annual growth rates are impressive:
5y CAGR (%) | |
Revenue | 15.2 |
Operating profit | 80.3 |
Net profit | 103 |
EPS reported | 99.5 |
And the rate of growth in profits is outstripping revenue growth, which suggests to me this group’s products are valuable and YouGov has some pricing power.
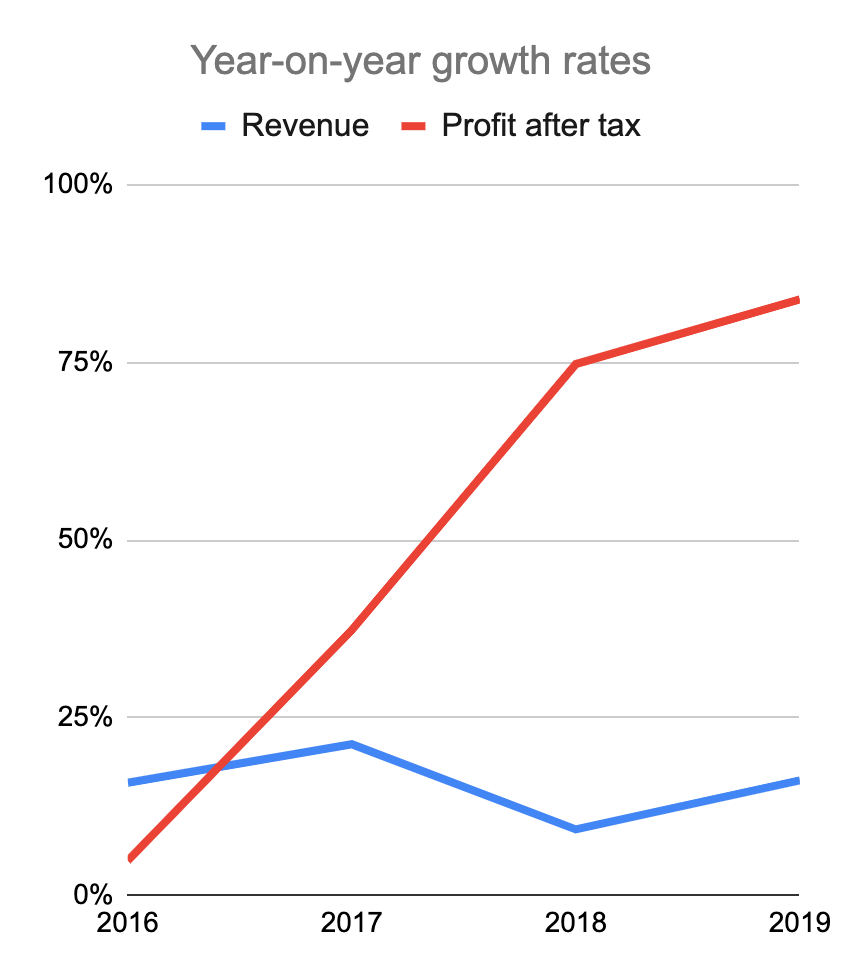
I think this is one to look into further. YouGov’s products and brand might be quite valuable, meaning scope for outsized profits.
To illustrate YouGov’s value, two initiatives stick out. One is its project with the Institute of Global Health Innovation at Imperial College London to gather global insights on people's behaviours and opinions in response to COVID-19 and the other is its YouGov COVID-19 Monitor for commercial clients.
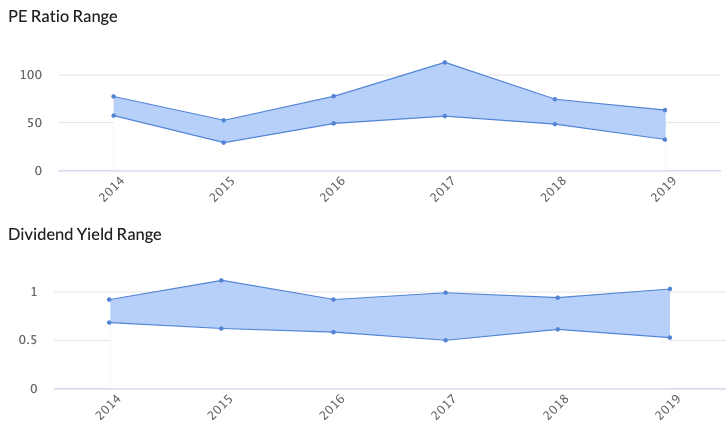
Like many High Flyers, YouGove has always been “expensive”. Right now, it is very much within its historic valuation range. I want to take a closer look at this business. There could be long term value here.
Volex - resilient update from a moderately rated growth stock
(Please note that I have a long position in Volex (LON:VLX) )
- Three month relative strength: 4.9%
- QM Rank: 91
- Market cap: £213m
Trading Update - 16 April 2020
Funny how quickly two stocks with significant manufacturing bases in China -Strix and Volex - have both bounced back with a vengeance in recent weeks.
Volex is a global provider of complex assemblies for performance critical applications and power products will announce its full year results on 18 June 2020. In the meantime, this trading update is very reassuring.
The group reiterates current guidance for the year, with FY20 sales up more than 5% to more than $392m (FY2019: $372m). Encouragingly, combined sales for February and March (the period since the outbreak of the COVID-19 virus) were up nearly 8% to $68m (FY19: $63m). This is despite a 3 week lockdown during February.
Volex appears to have handled the immediate effects of lockdown well. With operations back up and running, perhaps we can consider this stock broadly de-risked?
Management says:
“Looking ahead, it appears likely that economic activity and consequently trading will be impacted by restrictive governmental measures put in place to contain the spread of Covid-19.
However, the quantum and precise impact will depend on the length of time such measures are in place and their severity, offset against our defensive exposure to medical devices and data-centre products, which make up approximately two-thirds of our complex assemblies division”
A closer look
Volex has two segments: cable assemblies and power cords. The former is growing quickly, while the latter has a more challenging outlook. Last time I looked, complex assemblies division represented more than 50% of group profits and this proportion was growing quickly. Two thirds of this division’s revenue comes from medical and data centres, which strike me as attractive markets in which to build a reputation for quality.
Net cash has increased handily from $7.9m at the half year to $31.7m, and a final dividend of 2p per share based makes for a 1.45% yield. This dividend could grow quite quickly over the next few years - in fact I can see from the Financial Summary of the StockReport that we are expecting it to more than double next year by around 50% to c3p. On the other hand if the group finds promising acquisition opportunities then that might take precedence.
The group’s sites are operational and are deemed to be “essential” by the relevant governments.
Nat Rothschild, Executive Chairman of Volex and c25% shareholder, commented:
However, despite this 'perfect storm', Volex's business has proved remarkably resilient, continuing to produce a solid performance in both sales and operating margins. Our strategy to diversify our products, customers and geographic footprint, together with our exposure to medical devices (and high-speed data centre products, which are in even greater demand as much of the world's population works from home), has resulted in continued growth and strong cash generation, despite significant headwinds.
… Current headroom under our existing facility, combined with our cash balances, provides the group with circa $60 million of liquidity and, in line with our strategy, our team continues to actively look for new opportunities to grow our business and technical capabilities.
Operationally, there remain substantial identifiable opportunities for both divisions to improve sales and margin performance through disciplined execution of our strategy, in both the short and longer term.
Valuation
A forecast PE multiple of 8.7 is a good price to pay for a company that has turned around, restructured, and is now firmly in growth mode in my opinion.
As with any acquisitive growth stock, there is execution risk, but the business has so far proven to be remarkably resilient in the face of current macroeconomic challenges. It has a diverse customer base and multiple product lines selling across a broad range of geographical markets.
To go from $7.9m to $31.7m of cash, with $60m of total liquidity, suggests some strong cash generation potential. This is one company not just safe in the present conditions but actively looking to grow.
I’ve set out some extremely simple assumptions below using the adjusted figures:
- Power cords revenues to fall 10% per year, with profit margins frozen at FY19’s 6.65%, and
- Cable assemblies revenue to increase 10% per year, with profit margins also frozen at FY19’s 7.78% level
18 | 19 | 20 | 21 | 22 | |
Revenue | 322.38 | 372.10 | 369.54 | 370.69 | 375.54 |
Profit | 15.63 | 26.70 | 26.73 | 27.02 | 27.58 |
Profit margin | 4.85% | 7.18% | 7.23% | 7.29% | 7.34% |
Weighted average shares | 140.00 | 140.00 | 140.00 | 140.00 | |
Adjusted EPS | 19.07 | 19.09 | 19.30 | 19.70 | |
Share price | 137.70 | 137.70 | 137.70 | 137.70 | |
Adjusted PE ratio | 7.22 | 7.21 | 7.13 | 6.99 |
These assumptions are quite conservative and allow for a margin of error. It is quite possible revenue growth rates will be higher or that we should expect some margin expansion. Given its growth prospects, I think Volex is cheap
I have to stop there for now, but I think these three high QM company updates are worth flagging. I'd be interested to hear what others think.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

11 comments
Nice article on Games Workshop (LON:GAW)
https://www.theguardian.com/li...
(I hold and also happen to know the original founders)
I remember Jim Slater many years ago when Volex was a poor wee thing recommending a successful future for this Company
Michael
Very helpful on Volex (LON:VLX), please keep it coming. Management seems thinly spread though. Rothschild no doubt the highly ambitious driving force (along with impressive CFO) but with some history of his own... Can management really handle acquisitions that give them scale? One of their main competitors looks about ripe for plucking fairly soon, if they want it.
Frontier Dev PLC (FDEV) signs an IP Licence with Games Workshop Group PLC
Hi Jack
Timely piece but one quibble
Games Workshop (LON:GAW) results are ‘at least’ £70m for y/e 31 May ..that’s pretty much including 3 months of Covid 19....so arguably 2021 will see a strong bounce as things normalise...hopefully
.so arguably 2021 will see a strong bounce as things normalise...hopefully
Re: Games Workshop (LON:GAW)
Not sure I'm reading this correctly but last year PBT at the full year was about double that at the interims. Assuming that's the normal situation you'd have expected around £117m in the full year and as they were tracking normally up until the final quarter they'd have been at around £88m at the end of Q3.
At this years interims PBT was £58.6m and their current estimate for the full year is at least £70m - let's be generous and say £75m. So they've "lost"about £42m in pre-tax profits in three months and, by the look of things, will have actually made a loss of around £10m to £15m in the quarter. That's operational gearing kicking into reverse.
It's a great company and I assume there are a number of one off effects involved in this but at this price things need to normalise fast. Of course, they're not alone in this - there are an awful lot of businesses out there priced to see a rapid bounceback.
timarr
YouGov (LON:YOU), I would read Paul Scott's reports on this company, there does seem to be some accounting issues.
In that case I'll have a look at Paul's comments to see what he's found. Thanks for flagging, herbie.
and psin - that does sound familiar! Cheers for your comments, very helpful.
Thank you for your hard work, Jack. I appreciate how time-consuming it is to put together an article like this without coming across as biased.
GAW: my grandson, a twenty-five year old man with a degree, is an expert on this company having supported it for many years. He knows the manager of the store that he frequents very well and has nothing but praise for the way the store, and by extension, the company, is run. It is not for me to comment any further, but I can say that he has recently bought shares in the company, his only investment in the market. Declaration: I have a holding. Further declaration: Oh, how I wish I had kept the shares when I originally bought them @ £6. Does that sound familiar?
General comment. Bought and sold VLX many times. Always liked the company for what it does and the market that it works in. Steady and one that should 'hold up' when times get rough.
Loved your comments about YouGov and I agree that if it seems expensive now, it won't be when the economy recovers. Declaration: I hold.
I agree with the sentiment on GAW. It is a fabulous business that has developed a fan base over decades, that is loyal to its products. I believe over time the GAW brand will only strengthen and successfully expand into more markets. It is also a very well run business. Buy shares and hold for decades in my opinion. On a personal front, Games Workshop delivered so much magic to me and my friends during my teen age years in the 80s, and I'm happy to see how successful they've become.
No time like the present to get back in Stuart! I'm almost 40, and got back in to minis gaming over the last 12 months after a 20-year lay-off.
I also hold £GAW. Will look to add more in any economic downturn. Could be the British Marvel studios in 10-15 years if they play their IP right.