SIF Folio: Rethinking my approach to stop loss rules

This year has forced most of us to accept massive drawdowns in the valuations of our stock portfolios. Although some of these losses have now been reversed, I feel that we’re currently in a holding pattern. Until we see how the COVID-19 pandemic evolves and how much damage has been done to the real economy, it’s hard to know where the market might go next.
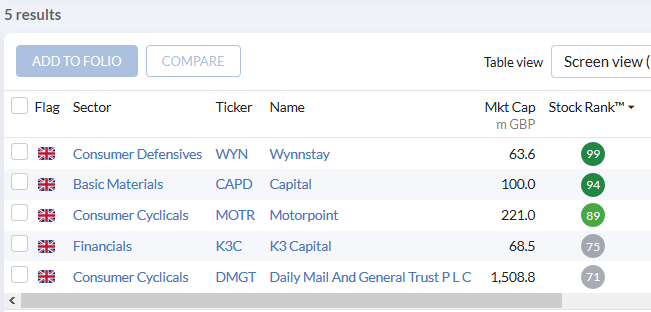
There are no new stocks for me to consider in my Stock in Focus (SIF) screen results this week. All five of the companies that qualify for the screen are already in the portfolio:
Instead, I’ve decided to grasp the thorny topic of how to limit my losses on losing positions in my rules-based SIF portfolio.
During the stock market crash earlier this year, I suspended my usual rules on selling and allowed positions to run. I saw no point in selling anything when the market was pricing in armageddon.
That moment has passed and I returned to business as usual in May. But I’m painfully aware of the adage that we should look after the losers and let the winners look after themselves. Have I accepted drawdowns on individual stocks too readily in the past?
The story so far
When I launched the portfolio in April 2016, I didn’t have any rules for selling other than at the end of a predefined holding period.
In April 2019 I modified my rules to add a requirement to sell any stock that issued a profit warning. Stockopedia’s excellent Profit Warning Survival Guide makes it clear that the weight of statistical evidence supports a quick exit from stocks which warn on profits. This reflects my own experiences, too. As Warren Buffett says, there’s rarely just one cockroach in the kitchen.
In 2019, I dismissed the idea of adding a stop-loss rule to sell on price action alone. I’ve always been against stop-losses, for two reasons:
Personal experience - when I’ve tried to use stop-losses, I’ve usually found that they’re triggered too easily or not soon enough.
Although the SIF Folio is a fairly short-term portfolio (typical holding nine months), most of my personal investments are over much longer periods. Selling based on price action alone doesn’t make sense for long-term investments, in my opinion.
I think that it’s fair to say my personal views and experiences may have biased my approach to handling losing positions in SIF. However, this year’s events have prompted me to revisit the rationale behind my investing decisions.
In May, I took a closer look at the statistical basis for my nine-month holding period.
This week I’m going to revisit the subject of stop losses with an open mind.
Why SIF could benefit from a stop-loss rule
It’s a well-known statistical truism that you need a 100% gain to break even after a 50% loss. So it follows that one of the best ways to improve your portfolio returns is to limit the losses you incur on your holdings. Smaller losses mean that profits from winning positions won’t be so heavily diluted by drawdowns.
Having looked at the historical results from the SIF Folio, I found that seven of the 86 closed positions I’ve held since the portfolio was launched resulted in losses of more than 25%. A little spreadsheet work suggests that if I’d been able to cap these seven losses at 25%, my average gain per position would have risen from 8.1% to 10.5%.
I should point out that this excludes dividends, costs and current open positions. Also, it doesn’t exclude positions that fell by more than 25% and then recovered to close out above this level.
Despite the limitations of my data, I think it’s fair to conclude that a stop-loss at 25% would probably have improved my portfolio return to date. Perhaps this is a useful reminder to myself that SIF is ultimately a momentum strategy, at least in part.
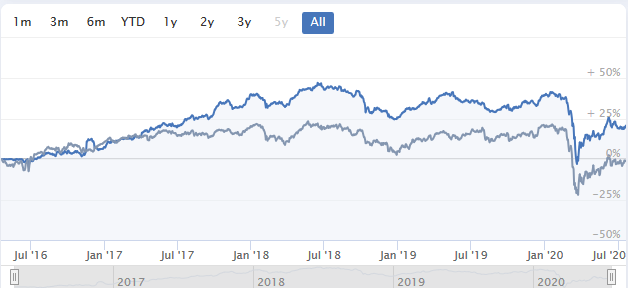
SIF folio (blue line) vs FTSE All-Share since April 2016
I’m going to add a stop-loss rule
Based on my experience to date, I’ve decided to add a stop-loss rule to the SIF Folio. As I’ll explain, there are certain practical limitations to how it will work. These reflect my need for transparency and the fact that I’m not able to automate the management of this portfolio.
Here’s how the SIF stop-loss rule will work:
What? I will close positions showing a price loss of more than 25>#/p###
How? I will review the portfolio weekly. If there are any stocks to be sold, I will include details of this in that week’s article. As always, I will make any virtual (SIF) trades and real money personal trades after the article has been published. This is to ensure full transparency and avoid any appearance of front-running.
Obviously the way in which I’m executing this stop-loss rule means that it won’t be exact. Sometimes stocks will recover or fall further before I’m able to sell. For small caps, the dealing spread may affect share prices.
For these reasons, I’m going to make 25% a soft threshold. I may use some discretion when deciding whether to hold or sell stocks running losses in a range between 20% and 30%.
Why 25%? As above, I think a fall of 25% represents a level that separates normal market movements from more serious, stock-specific problems. I accept that this is both subjective and a generalisation, but this is how I’ve decided to proceed. I would note that this rule is only intended to apply to profitable companies with a market cap over £50m. Blue-sky stocks and micro caps can be far more volatile.
Reducing the stop-loss threshold to 20% added a further 0.5% to my modelled average historical return. However, I feel that in this situation, a 20% stop loss would also be likely to result in an unacceptable increase in the number of false positives. I’m keen to avoid this.
On the other hand, I think that a 30% stop loss runs the risk of allowing stocks to fall beyond the point at which it becomes reasonably clear that a problem exists.
Profit warnings: I will continue to sell stocks on profit warnings, as I think the evidence supporting this is quite strong.
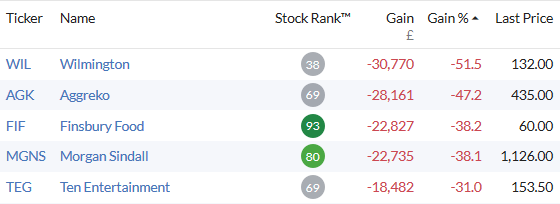
Retrospective application: I will not be applying my stop-loss rule to existing positions, most of which are coronavirus casualties anyway. I’ve listed these below. All will be allowed to run to maturity at nine months unless they issue profit warnings not attributable to coronavirus:
Am I right to do this?
I’d be very interested to hear your thoughts on this topic. From comments I’ve received in the past, I know that many Stockopedia subscribers do use stop-loss rules.
On the other hand, I think that for true long-term investors, the idea of a mechanical selling rule based on price movements is not far short of heresy. So I’m hoping for a robust debate (!) in the comments.
Finally, I want to emphasise that this change to my rules is - as always - an experiment. It’s certainly not intended to be a one-size-fits-all approach that will work for everyone. Please DYOR.
I’ll be back next week with my usual month-end review of the SIF folio.
Disclosure: Roland owns shares of all stocks listed
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

30 comments
For me, the absolute cut off is 20%. From a mathematical perspective, a loss of 20% will require a 25% return to recover from the losses. At 25% this widens to a little over 33%. The maths starts to work against you the larger the loss you accept. For growth shares, the stop the absolute stop is tighter at 15%.
When thinking about stop losses, it is very important to have portfolio management rules in place. Even with a 20-25% loss accepted on one company, you can still materially lower the risk of loss on the entire portfolio to something around 15%. A 15% loss on the portfolio can be recovered within a few years of average returns. By making sure you have taken steps to minimise losses, you naturally improve your returns long term.
My book "The Equity Edge" outlines the use of stops and a set of simple, robust portfolio rules that protect the portfolio in downturns. What is unique about these management rules is that they naturally underweight equity exposure in the portfolio in downturns and get back to fully invested quickly, at the right time.
There is also a section on using a dynamic trend following system for setting good entry and exit points for investments.
Hope this helps.
Mark.
Thank you Roland,
Great article. I read everything I can about stop losses! I`ve been investing for just 3 years now and find stop losses the single biggest conundrum. Articles/books/blogs seem about 50:50 for and against for the medium to long term investor[`like driving without brakes` v `should be called `make losses``] and I change my mind about them on a roughly weekly basis. I have no problem with cutting losses and have been in the habit of cutting anything which is down 20% with an automated stop loss. The problem, which cannot be anticipated, is a big market fall which would potentially stop you out of everything - and then when to buy back in? Having said that, I rather wish I had been stopped out of my reasonably large positions in DART and TEG in the recent downturn as I wouldn`t then have to look at horrendous drawdowns and would have plenty of cash to buy them back at what I think[and hope] are bargain basement levels! I am left with the nagging suspicion that stop losses are both good and bad and which one depends on your investment philosophy, time frame, which strategy the market is favouring, market volatility etc etc - so many variables that you will only know how useful or otherwise they have been in retrospect!
Thanks for your article Roland. Thought you may like this article on stop losses that I was sent not that long ago (can't recall where from!):
http://www.quant-investing.com/blogs/general/2015/02/16/truths-about-stop-losses-that-nobody-wants-to-believe
Summary of findings:
Haven't applied these findings to my own portfolio (yet) as a test bed, so can't comment from personal experience on efficacy.
Hi gregatr0n,
I agree that a trailing stop loss could work better than a static stop loss, but I don't have any means of automating this at the moment (in Stocko folios). Although I don't mind a bit of record-keeping, I think the price-tracking activity needed to implement a manual trailing stop loss would be excessive.
However, it's something I'd consider if the tech was there!
Regards,
Roland
Hi Roland
Thank you for taking the time to do the article. I had put an question on Stop Loss's myself in the discussion section back in June when I had a whole reflection of I think there is going to be a second downward lurch and the need to protect capital, and slowly learning more about my own emotion, trading and holding strategy (still evolving). I now realize that the majority of losses across three portfolios was actually in two positions Card Factory (LON:CARD) (your note on profit warnings and just exiting and swallowing pride) and Reach (LON:RCH) (an income holding which cancelled its dividend), and three poorly executed trades with oversize positions and too much going on in my head, all three would have made gains if I had held for ~30 days more.
As a result I set up stops on the majority of the portfolios. There were a number of the stops executed, they were automated with Halifax. Looking back now I found they trigger in early morning trade and you get lower than your designated stop value. The majority happened on two days where the overall market lurched downward (e.g. bad evening in the US triggers London selling at 08:00).
I had the whole was I a genius and exited correctly, or was I a numpty and should have just stuck with the courage of my original conviction debate, and still in part I am now! So I created a shadow portfolio which I deleted at the weekend as it was just a way to either pat myself on the back or beat my head against the wall (again). In conclusion of the ~10 positions, three had bounced back to the original purchase or better Unilever (LON:ULVR) Sage (LON:SGE) and Fevertree Drinks (LON:FEVR) the others Aviva (LON:AV.) and Legal & General (LON:LGEN) were somewhere between the stop loss sell point and purchase and others like Bp (LON:BP.) and Revolution Bars (LON:RBG) had continued down. So really the conclusion was ambiguous at best...
I think that the best conclusion I have, and this is probably taken from one of @Michael Taylor books, is you have to be able to articulate why are you going to sell a share when you first buy it - so why are you buying it in the first place and what are you hoping to achieve from the share. Many of us articulate this is a buy and forget or hold forever, but the reality is we all live a finite time so we are going to sell so is it a situation like @Graham Neary and buying a house, retirement or other major life event. Is it taking a better opportunity, so like your 9 month time-frame, does the stock still meet the rules of your original investment criteria if not exit. Or is there also an element of the stock is not doing what you thought it would e.g. increase in value or pay a dividend and do you continue to hold and think maybe it will turn out ok but remembering that you need a 100% gain to recover a 50% loss... but this does bring in the whole exit at a Y% loss as a blanket, but potentially miss a bounce back (and beyond) or keep hoping and watching the X% become 5xY% if I knew the answer I would only be here as a hobby as I would have long ago had the retirement event, which I haven't.
Tommy
' Looking back now I found they trigger in early morning trade and you get lower than your designated stop value'
This is the case even in more normal times than the present. Many share prices swing wildly when the market opens. After repurchasing a share which had fallen below my automated stop loss for a few minutes at opening time, I decided to maintain a spread sheet which is updated daily with the closing price so that I can apply any stop losses myself, seeing the price that I am getting.
I once read a book a long time ago (over 10yrs) which laid out the 3 golden rules of investing. They were printed on different pages, to add tension I think.
There were:-
No.1. Cut your losses
.
.
No 2. CUT YOUR LOSSES!
.
.
No.3. Run your profits
.
.
My stop loss system is as follows
I have a very strict stop loss system.
I make running stop-loss between 10% and 20%, on almost every purchase.
When I buy a share I look it up on Sharescope and bring the 1-year chart up. I then run a 10% stop loss line under the share price. If it does not fit, I try up to 20% and to get the best fit.
In my spreadsheet, I make a column that checks if the share price moves up, if it does, then I move the stop up too. (running stops)
This works for me. As it takes all the agony out of, "shall I sell or not".
It is a bit more complicated than that, but that the basics.
I am a midterm investor, and on average my profitable trades last 62 days, and the nonprofitable trades last 27 days.
Hi Roland,
I’m sure you are aware that I am something of a nerd, with a big database!
Hence, I could not resist running the SIF folio through the ringer of one of my stop-loss testers.
There were 13 positions where data quality issues meant that I could not test them. Of the remaining 80 , 26 (33%) would have been culled prematurely by a 25% stop loss.
Of these 26 triggered stops 15 (58%) produced an adverse result. In aggregate the SIF folio sold* these 26 positions for £1.108m; with a stop loss in place the result was £1.042m - £1.087m (I will explain further down why I quote a range) , that is -2% to -6% realised from these positions.
This looks very similar to the position I have seen when running similar models on portfolios like NAPS.
A Tale of two “halves”
But there is actually more to it. Perhaps unsurprisingly half of the stops triggered happened this calendar year. Thus far, these do not look successful. These 13 positions in SIF would be valued at (or have been sold at) £639k, whereas the stop losses would have yielded £554k - £581k with 8 of 13 stops disappointing.
The counter-point to this, however, is that prior to this year the stops have done a reasonable job, in more “normal” market times. Sure, 7 out of 13 of the stops produced adverse results, but overall holding to term yielded £469k whereas the stops returned £488k -£507k (a 4-8% improvement).
So on the one hand it looks like there might be some value in the stops in “normal” market conditions. On the other hand three years of good work were wiped out in a short period of market volatility. Could you judge when to turn the strategy on or off? I doubt it.
Outsized Returns.
It is also worth noting that nearly 250% of the Stop Loss improvement pre-2020 was delivered through two positions.
Bilby (LON:BILB) stopped out in September 2018 at a price in the range 91-95p vs SIF eventually selling at 40p.
Staffline (LON:STAF) stopped out in January 2019 at 945p, compared with the eventual SIF close @ 324p.
Did either of these issue a profits warning, that would have made you sell even without a Stop-Loss?
The Cost of Friction.
I should explain that I have modelled this using the daily market opening price (as this is when the gaps occur).
I have quoted two returns for the stop losses, one being the stop target and the other being the actual opening price. In reality the higher target level is unattainable, even if you were using Spread Bet Guaranteed stops, you pay a premium for the privilege.
It is also worth noting, that might prices therefore take no account of the spread, whereas the sales recorded in the fantasy folio do. This is potentially enough to wipe out most of the gains delivered prior to this year.
Overall, therefore, it is hard for me to conclude that stop losses are going to improve your performance; but perhaps you can consider them a relatively inexpensive insurance policy?
Here’s the data
Hi Gromley,
Thanks for your comments. I agree that the benefits of a stop loss aren't necessarily clear cut in real life market conditions.
My aim with the stop losses is not to sell out in exceptional events like this year's crash. However, history suggests this is a once-in-a-decade type of market dislocation. My aim is to cut losses in more normal markets, as you suggest.
I'm fairly sure that both the big losses you mention (Bilby (LON:BILB) and Staffline (LON:STAF)) predated my policy of selling on a profit warning. I think this should help avoid such big losses in the future.
As always, my SIF rules are experimental and won't all improve results. Modelling the different 'what if' scenarios isn't always straightforward and is sometimes not possible. But I'll aim to muddle on and see what I learn.
Regards,
Roland
Thanks Roland,
In terms of : "My aim with the stop losses is not to sell out in exceptional events like this year's crash." I would just wryly observe that whilst not selling out as the wider market went down 30% seems to have been the wise move on his occasion , less so in 2008! But as you say these dislocations are perhaps a once in a decade or so experience, so for SF to experience this in its 4th year is 'unfortunate'.
I do agree though that experiment and tweak are what we really have to do.
In that respect it was interesting to read jumbowanabee's thoughts on hedging vs. a FTSE short.
As I wrote about a couple of years ago, my approach has been to hedge against a dogfolio of shorts.
My initial thoughts on this were that it would be a low cost insurance policy, it has actually proven better than that - a negative cost insurance policy. It's quite hard work and it's not proven that I'll be able to scale up sufficiently when I bring more funds under direct management in a couple of years, but for now it works for me. My initial plan was to be perpetually market neutral (ie shorts = longs) but like jumbo I am now thinking (and moving) towards tweaking the balance.
A thorny question Roland. Like many contributors to this thread I also struggle with stop losses. I find it very difficult to sell on price movement alone. Robbie Burns has very successfully mastered the art of killing losses. At one point I tried to emulate him, but it didn't work. The stocks I sold at a 10% to 15% loss bounced back significantly.
As often said prices tend to over shoot on the downside and upside. As a consequence I sold very little during the pandemic melt down. I continue to hold a few leisure orientated stocks to my detriment, because I feel that the price does not reflect the intrinsic value of the business, a view that has not changed, although I have been very tempted to hit the sell button. The principal culprits are Itv (LON:ITV) and £FSTA. I suspect I may be guilty of a little confirmation bias. If and when these stocks recover depends very much on how things pan out over the next few years.
Thank you the thought provoking narrative.
Stop loss.
Agree find it very hard to stick to a system. I set support and resistance lines and study it hard if breaks either. But Galliford Try Holdings (LON:GFRD) has fallen through several of my 'support lines' and could not bring myself to take the loss. StockRank and Quality says it's not 'junk' so have taken the long view and ride it out, but only as cannot bring myself to take the hit. Cash flow could run out however, but hopefully survive to 2021. Trouble with that is when it does rise then everyone and their dog will have got bored and sell off. So perhaps a system to get out earlier would have been more sensible to protect my capital.
I think that stop losses don't make much sense from a value investing perspective. If you bought a stock it must be because you have estimated that its intrinsic value is much lower than the current price. If the price falls even further, you want to buy MORE shares, not sell what you have already bought. Markets are hysterical, which means that they will make the prices fluctuate in a chaotic manner. A good trading strategy cannot involve any automatic trigger that unloads an entire position based on such erratic behaviour. Most of the stocks in my portfolio have experienced a crazy downside of even 10-15% over the course of a few days, just to recover immediately afterwards and often even starting a rally. If I had used a stop-loss approach, I would have systematically sold each and everyone of them at a loss.
Hi Francesco,
I agree with you completely from a value perspective.
The reason why I'm introducing a stop loss policy is because I have a limited holding period (usually nine months) for stocks in the SIF folio. One element of this strategy relies on momentum. If this breaks down, there's often not enough time for it to recover. Hence I think that it makes sense to cut losers earlier.
In my own long-term portfolio, I would not ever consider using stop losses. Like you, I've often had stocks fall sharply and subsequently recover.
Regards,
Roland
I agree that applying stop loss rules are a good thing to do in normal times. But this simply begs the question, 'What are normal times?'.
Some say the normal rules of thumb for stop losses are designed for Volatility (VIX practically) under 30. Beyond this threshold the market behaviour becomes un-investable using conventional stop losses. Volatility (as measured by VIX) is now well below 30, so you might think that normal times are here again? That may depend on what you are investing in and when you are invested, Specifically Small-caps in the low volume weeks of high summer: beware!
For your existing positions you could try applying Chandelier Exits based on a volatility threshold (as expressed by a multiple of Average True Range linked to a Sliding Window anchor). Alternatively you could draw trend lines which when violated trigger an alert to Sell.
https://school.stockcharts.com...
Roland, I've just begun to set Stocko's Alerts on my high-flying shares so that when an alert is received I can run the ruler over the share in question to make an informed decision. There's no doubt one must carry forward one's convictions, I wanted to sell all my shares last January, warts and all, and couldn't bring myself to do it. It was a no-brainer really. As an example, an alert set to a fall of 17% on Mysale (LON:MYSL) triggered earlier this month, I sold, being nervous about the Australian economy and redirected the funds into a couple of gold miners. I've since been able to set up alerts on these. and may use your 25% figure for them. So there are benefits to be had in having some kind of prompter.
Thanks for your article!
Hi Roland, thank you for your article. You raise an interesting question to which, I feel, there is neither a quick nor absolute answer. There are many technical and personal factors at play. One matter that I feel is definitely worth consideration is position and portfolio size rather than a fixed percentage from the buy/entry point. On this basis you might argue therefore that stops should be triggered at say a loss of perhaps 1-3% of your portfolio. After all, you can always buy back.
Knowing when to exit a losing position is always difficult. Rather than setting a 25% or other stop loss on all holdings, is it not better to decide an appropriate loss based on the volatility of each stock at the time of making the investment/ As you know, many stocks are unlikely to drop more than 25% in normal (if there is a normal) and so a stop at 25% would keep one in the position. If there is a likely volatility of say 50% and that risk is too high for comfort, the don't invest. I have frequently been caught out by placing too short a stop loss, all stocks need space to breathe and have had more success tailoring my investment sizes and stop losses after carefully looking at the volatility before investing.
Hi Frap,
Thanks for your comment. Tailoring stop-losses to reflect expected volatility is an interesting approach and I can see how that might work. However, I'm not sure my processes and the data I use to select stocks would support this level of granularity. So a blanket rule - although imperfect - is probably the only option for SIF at the moment.
Regards,
Roland
Hi Roland,
You have probably seen the image below. If not, think it might be relevant to the stop loss issues you are considering.
Risk Rating maybe the key?
The more volatile or speculative and highly speculative shares may need extra due diligence before purchasing.
The 12.5% stop loss is the figure mentioned in the book. The art of execution.
Great question Roland. There is probably more than one way to skin a cat re stop losses, but its not good to feel like a rabbit in the headlights when a serious market crash is unfolding. You need a plan that feels right for you, and suits your attitude to risk.
With stop losses, I think that you need to decide if you are defending against losses in the overall market (or sector), or defending against a company that might be going to the wall.
Re the market as a whole, if you believe that the market will rise in the long term, and you hold index funds (or companies that closely correlate the market), and you have spare cash, then you should invest after (or during) a crash. "Buy when there is blood in the streets" - to use Ray Dalio's term. If, later on, you find yourself enjoying spectacular returns (ie you feel that you are comfortably satisfying your investment objectives), you should shift some funds into cash (in preparation for a rainy day) - dare I suggest you go out and spend some of it?
If large cash holdings aren't your thing, then diversification into defensives and precious metals can prove useful insurance measures that help to smooth out excessive volatility and reduce those sleepless nights.
Regarding specific companies, getting out as soon as there is a profits warning is sensible. Unfortunately, retail traders are often the last to know. So in the absence of a profits warning, (or any other explained event) a sharp fall in share price relative to the company's sector is sometimes the only alert we have to help us. Here a blanket percentage figure, whilst simple to apply, might not appropriately factor a company's share price volatility, its sector, individual circumstances and overall long-term value. Setting a figure is tricky, but it is certainly sensible to have a level tailored to each company, at which you determine that the investment was a mistake and its time to get out.
Oh, and another thing. People don't think straight after market crashes. But if you can keep your head........etc, etc
Back in February my concern, like so many, was the fallout from Covid, the FTSE 100 was trading between 7100 and 7600, my portfolio was up over 8% by 21st February and certainly outperforming the FTSE benchmark. Now what if I had started the year with a FTSE 100 short in order to hedge my portfolio. At the beginning of the year the FTSE 100 was trading at 7560, if the value of my portfolio was £75,600 then for each £1 per point short I would be hedging 10% of my portfolio. At £10 the portfolio would be fully hedged. Now I accept my portfolio will not accurately track the FTSE but I have found it tends to followo the ups and downs.
When the evens of February / March unfolded, like most, I saw a significant drop, but my portfolio was still outperforming the FTSE, it is currently up 11.5% YTD while the FTSE remains nearly 20% down. A 100% short on the FTSE would have generated a 31% profit on the position, any losses on the portfolio were more then covered, indeed had the short position been closed the tax free proceeds could have been reinvested into selected companies with the portfolio value remaining unchanged. I would have time to evaluate and allow the market to settle before deciding which companies to keep or cut. This hedge acts as an overall market stop loss, it can be varied in according to the FTSE value and the “fear factor” back in February there was little upside against the larger risk created by Covid. An increase in the short to 60-70% may have been appropriate. Of course today there is still downside but the FTSE is already trading 20% down so a smaller short position might be more appropriate.
Sounds sensible to me - and like you - I am holding onto £MGNS One of the frustrations I have found is that having set a SL figure - the price plummets far below, and by the time you get a chance to sell - its not 25% down but much more.......
Hi bohenie,
The delay between triggering a manual stop loss and executing the trade is definitely a risk. I'm not sure how it will pan out for SIF.
Obviously in a market crash nothing works normally, but in more normal times I think this should be more manageable for most stocks, especially larger ones.
Regards,Roland
Hi Roland
As we all know selling is much harder than buying. Behavioural biases make it doubly difficult.
As HumourMe mentions 'The Art of Execution' by Lee Freeman-Shor is an interesting and relatively quick read and tackles this question.
He analysed the investing habits and returns of 45 top investors (over 1800 investments and over 30000 trades). Despite their experience and skill less than 50% of their investments made money. The key to the most successful was to cut their losses quickly and dispassionately and to top slice their winners as they rose in value rather than sell too early.
The most effective way to cut your losses was to have a stop-loss set somewhere between 20 and 33% (the range used by the best investors he analysed). To be clear this was not a soft stop-loss, each investor had his or her preference.
To avoid all behavioural biases this stop-loss was set at the time the share was bought. So a suggestion would be that for your SIF folio and to maintain full transparency you buy the share as you state and at the same time set a stated percentage stop-loss.
I suspect this would improve your returns but of course only time would tell :-)
Many thanks for your regular SIF folio updates.
Regards
Iron
With stops you need to answer "what are you guarding against?".
As crashes tend to cause all shares to correlate downwards (and continue) an alternative to consider (to lock in gains and sit in safety) is to sell everything when the portfolio is down X%. You need a rule to get back in though.
"The Art of Execution: How the world's best investors get it wrong and still make millions in the markets" makes for interesting reading on losses. If they come into play the market is disagreeing with your assessment, as if you expected a fall to occur that breaks any threshold, surely you would have waited to buy? I can see for value investors (with a portfolio) stops make less sense. If a strategy relies on momentum as a component then lots of shares triggering stops is a sign that the portfolio isn't doing what was expected.
My conclusion is that if you are timing entry then they can be tighter. If they are for capital preservation they can be position based (i.e. per share) or portfolio based. Or both. If position based 10%-25% trailing, based on volatility may be necessary. If portfolio based it could be a lot less. Portfolio based might also be easier to manage.
Hi HumourMe,
Thanks for your comment, you make a good point about the purpose of stops. In this case my main aim is to protect against stocks/companies that underperform, rather than against market crashes.
Obviously there's some overlap, but as in March/April, I won't sell the whole portfolio just because the market has crashed. I think it's worth saying that while this year's crash is still fresh in our minds, history suggests this kind of crash only happens once every 10 years or so.
In reality, most stock losses are achieved without the aid of a crash! My goal is to reduce these 'normal' losses.
Regards,
Roland
P.S. The Art of Execution has been on my reading list for a while, I must get a copy.
Hi Roland,
I've really enjoyed all your articles this year and found it very useful to see you run the SIFfolio.
As a 'long term investor' (typically holding stocks from 3-8 years). I find it difficult to apply stop losses on price action. If the investment thesis has not changed I would probably add to the position at the low price. I am more likely to sell out if and when the investment thesis is found to be incorrect or changed substantially.
I would agree with you though if one is using a rules-based systemic way to build the SIF folio then a stop loss should help performance rather then hinder it.
Is it possible to post a year to date view of the performance of the portfolio?
Many thanks
BSV
Hi BSV,
Thanks for your comment. I agree that stop losses aren't necessarily useful for longer-term positions. I certainly don't use them in my own long-term portfolio. As you do, I'm more likely to average down during a market correction.
Re. SIF: I publish a review of the portfolio at the end of each month. In June's review I included a summary of performance versus the market so far this year:
https://www.stockopedia.com/co...
Regards,
Roland
Thanks, Roland
BSV