SIF Folio: Should I back owner-management at Motorpoint?

Anyone invested in UK-focused cyclical stocks has done well since December’s general election. Indeed, we might speculate that if Neil Woodford had maintained his focus on FTSE 350 dividend stocks, he’d now be enjoying the adulation due to a successful contrarian.
Mr Woodford ran out of time, but the main reason this happened is that he didn’t stay true to his system. If he had, I’d be willing to bet that investors would have continued to trust his stock-picking instincts.
The Stockopedia ethos is all about focusing on quantitative factors that are proven to work. Not every stock with good stats will be a winner. But in aggregate, a balanced selection should perform well, as Ed Croft’s NAPS portfolio has demonstrated.
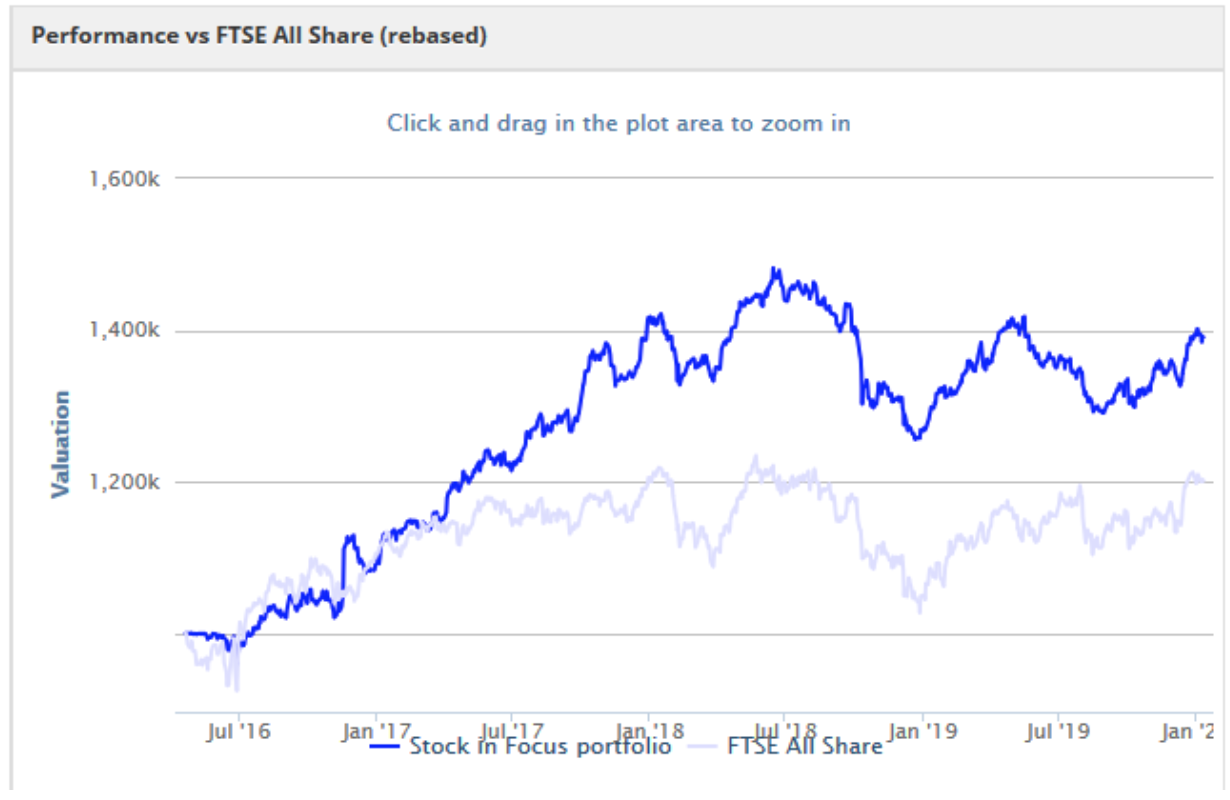
Staying true to my system has been a key goal for me since I launched the Stock in Focus (SIF) folio in April 2016 (this link will only work on the old Stockopedia site). The challenge I agreed with Ed at that time was to see if I could beat the market with a portfolio where the stocks are selected using a screen. So far, I’ve succeeded:
But sticking to the rules isn’t always easy. Sometimes the stocks which qualify for my screen just seem like poor businesses. Other times, I like the business, but it feels like the wrong time to buy.
Right stock, wrong time?
This week’s stock is a good example of this dilemma. I admire car supermarket Motorpoint Group (LON: MOTR) as a business. But buying now seems like an all-or-nothing bet on the UK economy.
To give you a bit of history, the SIF folio has previously owned this stock, from December 2017 to January 2019. My timing was poor. I bought too late to enjoy the 2017 gains, watched the 2018 gains slip away and then sold before the rise seen in the second half of 2019!
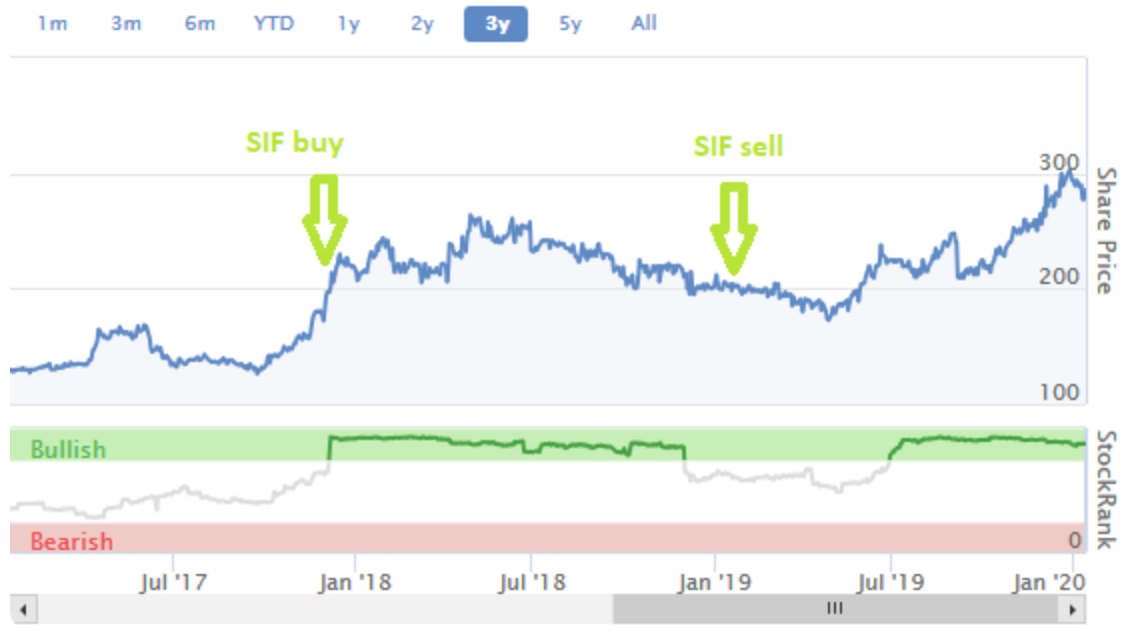
C’est la vie - the holding did at least log a small profit above its costs.
In my view, it’s not hard to imagine the same thing happening again in 2020. Motorpoint shares have risen on Brexit/election euphoria, but of course nothing has actually changed in the real economy. And the hard work on Brexit must still be done.
Of course, I may be wrong. Paul’s SCVR on Monday highlighted some interesting economic data which suggest the outlook may be quite positive.
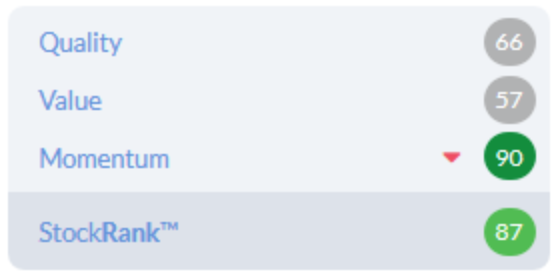
More importantly, my SIF screen tells me that Motorpoint is a qualifying stock. It’s pretty much the only one I can choose that I don’t already own. So this week I’m going to be taking a fresh look at this £250m group and deciding whether to add it to the SIF folio. As usual, I’ll explore the stock through its three factor scores for Value, Quality and Momentum.
If you’re not familiar with Motorpoint, you might want to check out some of my previous coverage of this group, which is the UK’s largest used car supermarket. Here’s my original buy report, and here’s a discussion of the group’s very high operating leverage.
Cash value
Motorpoint’s ValueRank of 57 seems a little underwhelming. But I think there are some attractive qualities here, which I’ve circled in green:
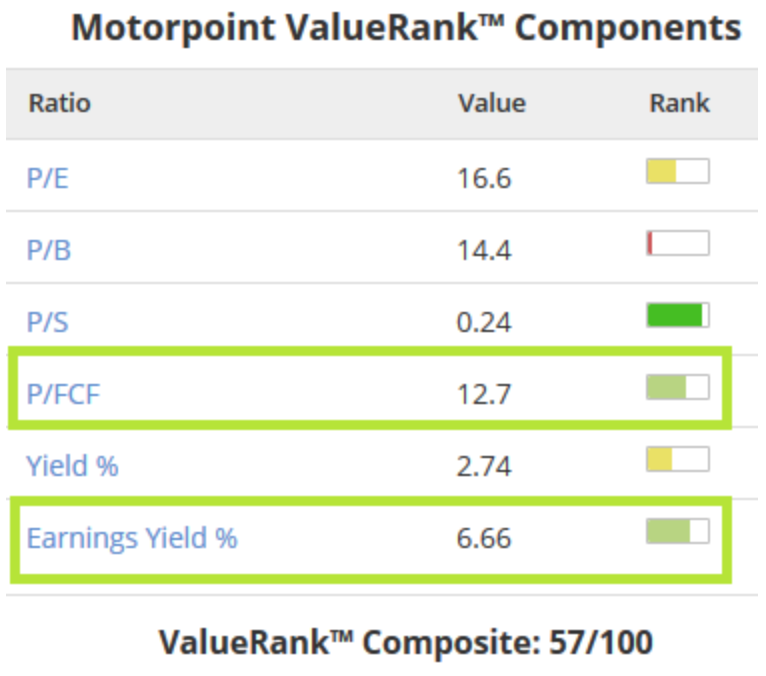
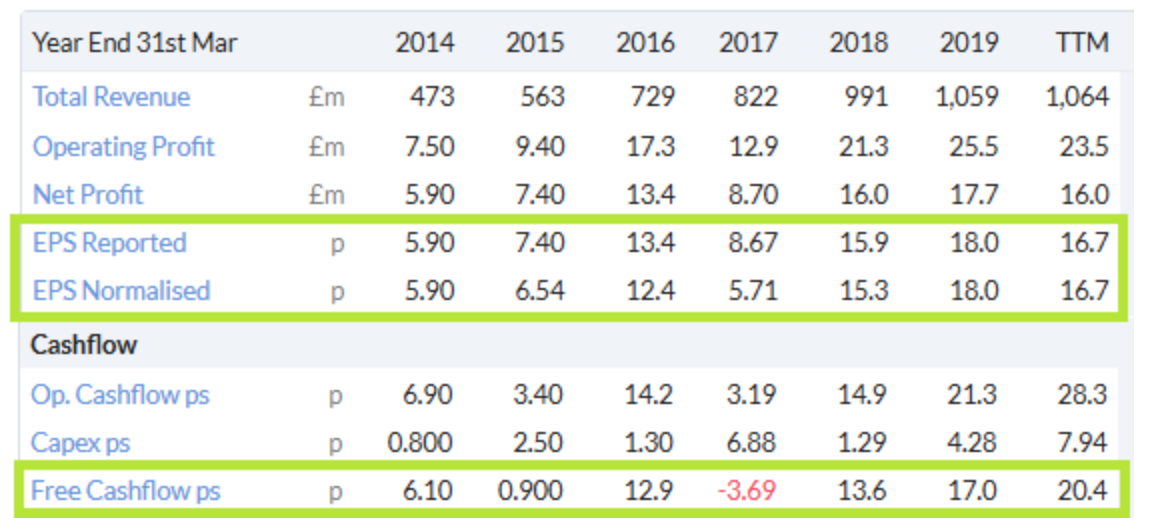
Motorpoint’s high returns on capital lend themselves to excellent cash generation. This is reflected in the price/free cash flow ratio, which is lower than the stock’s trailing P/E ratio. This tells us that free cash flow was greater than accounting earnings last year.
A glance at the StockReport tells us that free cash flow has generally matched accounting earnings. This is a big attraction for me:
I’ve no serious concerns with the current valuation. The only risk, in my mind, revolves around future performance.
Quality: skin in the game
If you’re not familiar with Motorpoint, then the main selling point of this business is that it only sells cars under three years old and with less than 25,000 miles on the clock. Most cars are under two years/15,000 miles. I suspect many come from rental fleets, although I don’t know this for sure.
In any case, the company offers keen, fixed pricing, convenient credit and a good range of stock. It’s a formula that works, with almost 30% of sales to repeat customers. From a financial perspective, fast stock turnover means that despite only generating an operating margin of about 2%, this business enjoys strong cash generation and generates very high returns on capital.
I’ll return to these quantitative factors in a moment, but first I want to highlight a qualitative attraction I’ve not previously mentioned: insider ownership.
According to Stockopedia’s excellent new major shareholders feature, chairman Mark Morris and CEO Mark Carpenter each own about 9.5% of the business:
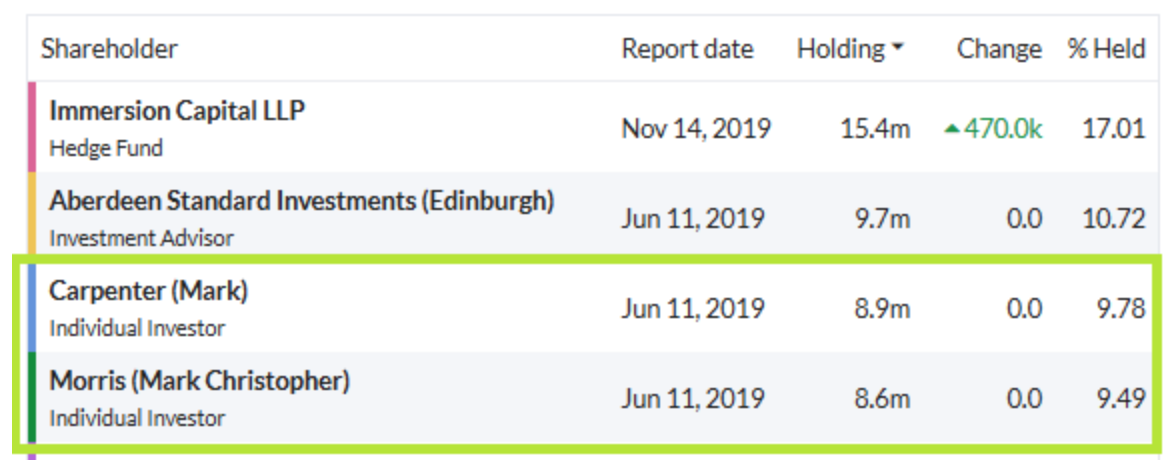
I think that having the firm’s two top directors as major (but not controlling) shareholders has got to be good news for outside investors.
Getting back to the numbers, I note that Motorpoint’s QualityRank of 66 seems relatively low for a company that’s generated an average return on capital employed of 48% since 2014:
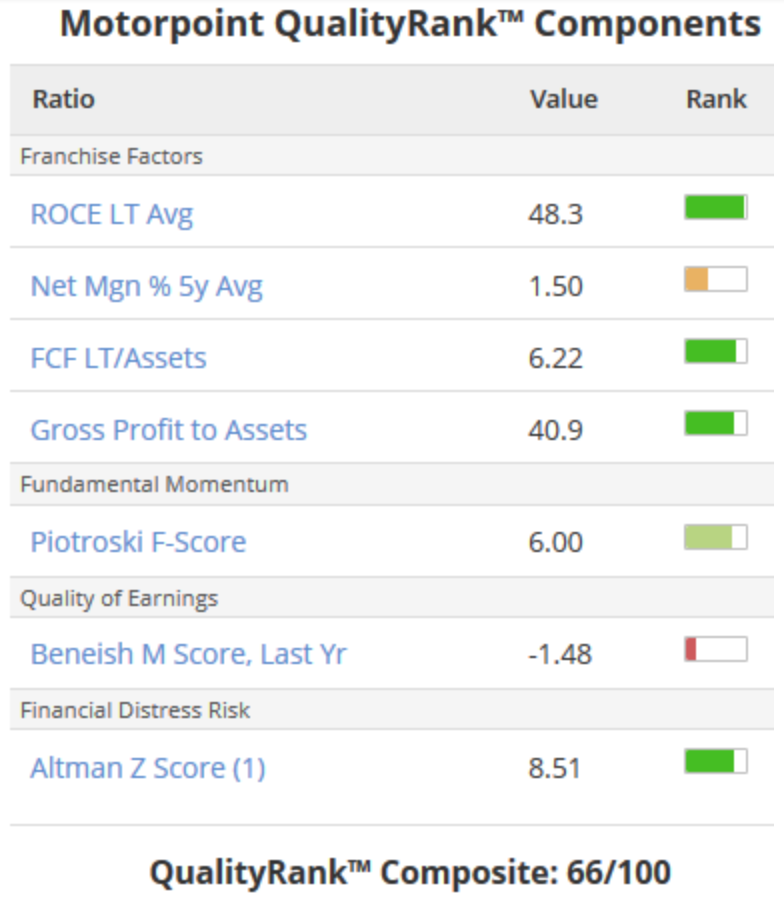
I suspect the stock’s Piotroski F-Score of 6/9 is the main factor dragging down its QualityRank. The F-Score is being held back by a reduction in profitability over the last year.
Despite a 1% rise in revenue during the first half of the year, rising costs caused pre-tax profit to fall by 18% to £9.4m. The company also warned of an H2-weighting, which is often code for a profit warning yet to come.
This is my main concern with this stock, but I note that full-year guidance has been maintained and that forecasts for the year ahead are improving.
Improving momentum into 2020/21?
The analyst consensus trend chart on the StockReport page is a feature I use a lot. Although analysts’ forecasts aren’t infallible, they tend to provide a reasonable idea of trends. In this case it seems that the City expects a significant increase in profits next year:
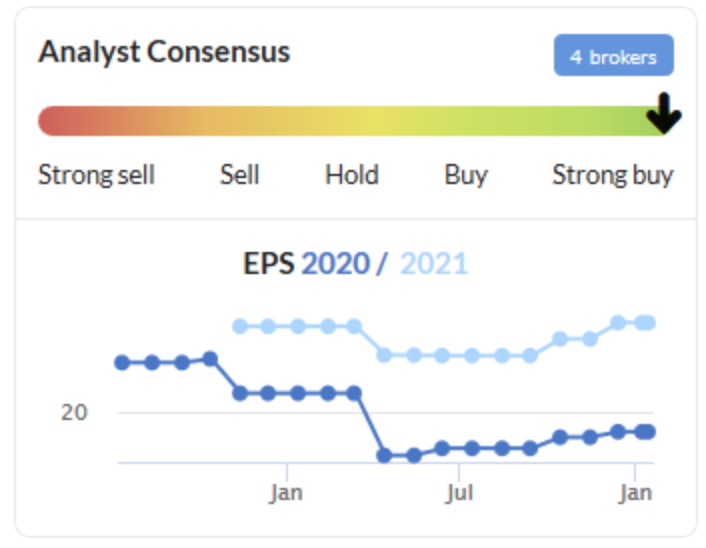
Looking at the numbers behind these forecasts, underlying earnings are expected to rise by 15% from 19.5p to 22.3p per share. That puts the stock on a FY21 forecast P/E of 12.4, which doesn’t seem excessive to me.
For me, the big question is whether Motorpoint will hit FY20 forecasts. It’s now nearly two months since November’s interim results, and there’s been no further update. But the group’s financial year doesn’t end until 31 March, so there’s still a lot of room for uncertainty.
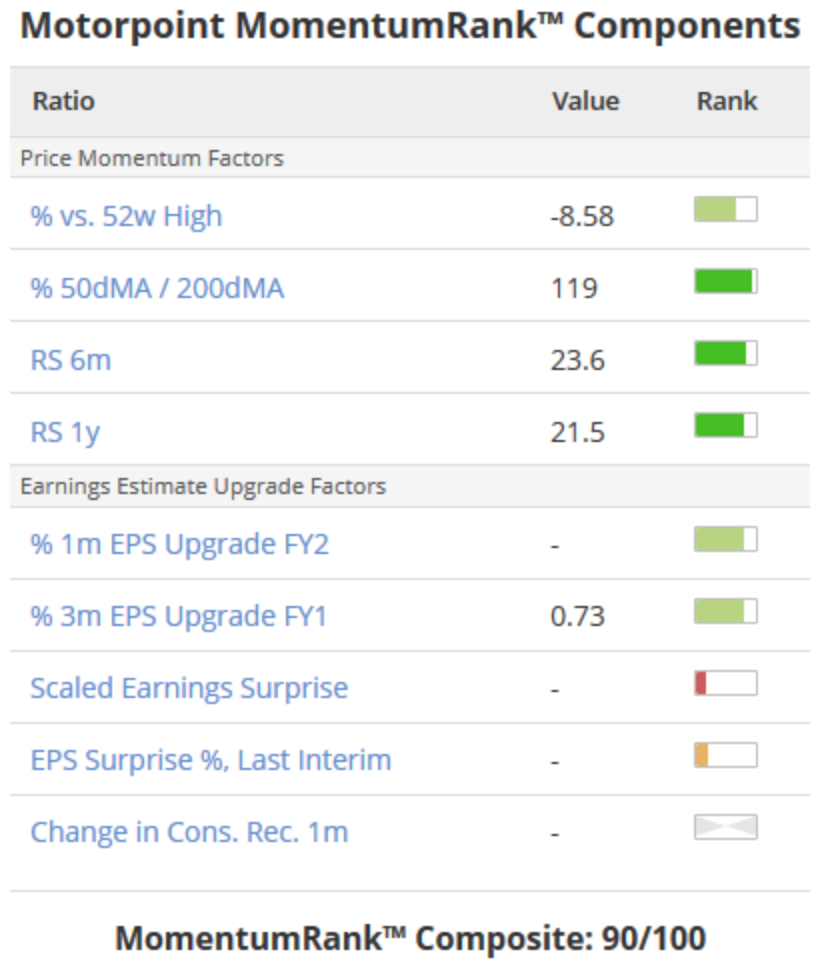
Stockopedia’s algorithms are confident, awarding the stock a MomentumRank of 90:
My verdict
I’m still a little uneasy about taking such a cyclical bet on the UK consumer economy. But I rate Motorpoint’s management highly and am reassured by their skin in the game. I’m also pleased that the rollout of new branches seems to be proceeding slowly. This is a competitive, mature market, not a land grab - I’d rather see cautious growth with good execution and tight financial controls.
I’ve decided to give Motorpoint a second chance and buy the shares back for the SIF folio this week. As always, I’ll buy the shares for SIF and for my personal portfolio after this article has been published.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

1 comment
One must wonder if Motorpoint will be a winner or loser due to COVID?
Loser as its big car supermarkets have been closed. And consumer big-ticket spending is likely to be pressured for a while as long as there are furloughs, redundancies, and uncertainty.
Winner has lots of rental fleets and cars on PCF leases flood the market, which is what Motorpoint specialises in (less than 3 year cars). More supply means they have pricing power, and hopefully can maintain a good margin when they flip them to consumers.