SIF Portfolio July review: Profits from Miton, McColl’s and Wincanton

As I flagged up in my year-end review, I’m shifting the portfolio’s minimum holding period from six months to nine months. To avoid too long a time without adding new stocks, I’m making this change gradually.
In May I looked at seven-month old stocks. This month it’s time to review the portfolio holdings that are eight months old. Three stocks qualify:
Small-cap fund manager Miton Group
Convenience store chain McColl’s Retail
Logistics firm Wincanton
A quick look at the SIF portfolio suggests that it’s been a successful eight months for all three firms, with an average total return of 29.6% on each stock. Let’s take a closer look.
Miton Group
Miton’s fund management business is headed by small-cap expert Gervais Williams, who also has a 6.9% stake in the firm. Our own Ben Hobson interviewed Williams last year. If you haven’t read the interview, I’d recommend it.
Miton’s share price has risen by 43% since I added it to the portfolio in November. One reason for this is the above-average investment performance of the firm’s funds. Management say that 12 out of the company’s 15 funds have been first or second quartile performers from when their current managers took over, until 30 June 2016.
One of the reasons why I decided to extend the minimum holding period for each stock was to make sure that all companies published at least one set of accounts during their time in the portfolio.
In the case of Miton, this has worked to my advantage. The group’s 2016 results showed that average assets under management rose by 20% to £2,783m last year. Fee margins were maintained, and the group’s adjusted pre-tax profit rose by 70% to £5.1m. Strong cash generation allowed the board to increase the dividend by 49% to 1p per share.
Miton’s 12 July H1 trading statement was also well received by the market. The first half of the year saw average AuM rise by 13.4%, to £3,157m. Net cash was £18.2m at the end of June, despite a £2.6m share buyback.
Although Miton’s management don’t seem to have explicitly updated their guidance for the year, consensus forecasts for 2017 and 2018 have risen recently:
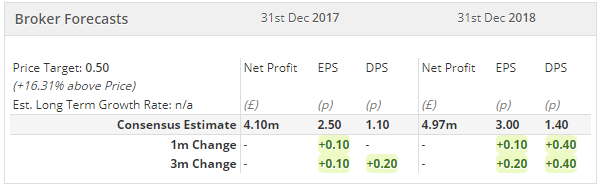
Miton now rates as a Super Stock under the StockRank Style system and has a StockRank of 98. The shares don’t look especially expensive, and could climb further. However, they no longer qualify for the SIF screen, so I will sell my holding from the portfolio this week.
Verdict: Sell
Total return: +46.3 percent
McColl’s Retail
When I added convenience store group McColl’s to the portfolio, I was relieved to add a defensive business. However, I noted that “opinions vary” about the business and commented that “a low-margin business like this shouldn’t have a high valuation”.
The shares have risen by almost 25% since then, so does McColl’s still look cheap enough to buy? As luck would have it, the group published its interim results on Monday. Graham Neary took at look at the figures here, so I won’t retread this ground.
Graham concluded that while the business is performing well, an increase in net debt means that “the market cap is not as cheap as it first appears”. He also noted that it’s unlikely to have any competitive advantage other than scale.
I share this view. The company has made good progress over the year, and gained useful wholesale purchasing power by acquiring 298 stores from the Co-Op. But I’m not sure the financial quality of the business or its valuation are as attractive as they were back in November.
McColl’s now fails to pass my screening test on three counts:
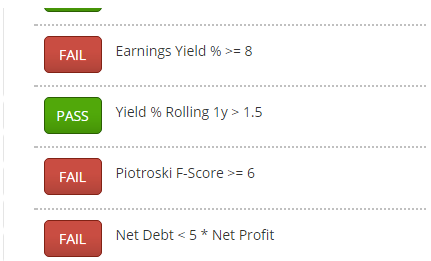
Supporters of the stock will probably argue that net debt should fall again once the integration of the Co-Op stores is complete. That may well be true, as free cash flow generation has been strong in the past. But net debt of £110m is now more than five times forecast net profit of £20m. That’s a level I find uncomfortable.
The valuation is also less appealing than it was. Rising debt and the higher share price mean that McColl’s earnings yield (EBIT/EV) has fallen from 10.1% to 5% during its time in the portfolio. Its Piotroski F-Score, a useful measure of financial health, has also fallen from six to five.
I also note that McColl’s QualityRank has fallen from 75 to 55 since 1 July.
Although this stock still has a StockRank of 94, I’m quite happy to take profits at this point.
Verdict: Sell
Total return: +28.6 percent
Wincanton
My newly-extended holding period meant that the portfolio’s shareholding in Wincanton suffered from the logistic group’s recent profit warning, which knocked 15% off the share price.
As Paul Scott commented at the time, it was “a very mild profit warning”. In fact, management guidance is still for pre-tax profit to be “broadly in line with expectations”. My reading of this is that profits are likely to be slightly below expectations. The analyst community seems to agree. Consensus forecasts for 2017/18 have fallen from 28.4p in June to 27.9p today. Next year’s forecasts have also been shaved slightly:
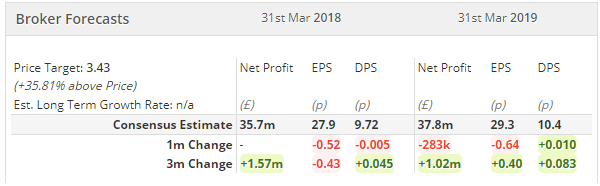
Despite this, Wincanton still seems to be a fairly strong business. An operating margin of 5% is a good result for this sector, and the group has managed to repay debt at a good rate over the last few years. The main concern, in financial terms, is the £78m pension deficit.
Given that this deficit fell by around 25% last year, it probably wouldn’t be enough to stop me investing in the future. But the increasingly uncertain outlook for earnings means that this stock no longer passes my screening tests. It’s now time to sell it from the portfolio.
The share price was knocked by June’s trading statement. But Wincanton has still kept pace with the market over the holding period, delivering a price gain of 10% and a dividend return of 4%.
Verdict: Sell
Total return: +14 percent
What’s next?
This week’s portfolio disposals will restore the SIF portfolio’s cash balance to a healthier level and reduce the number of holdings to 19, which is within my target range of 15-20.
I hope to be able to use some of this new cash to add a new stock to the portfolio next week.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

8 comments
the share price of McColls will probably shoot up, as this certainly puts McColls on the map now.
Hi Roland,
SREI was bought at 59p and the share price is now 57.25......shouldn't it show as a Loss rather a Gain of 14%?
Hi dpo1130,
What's happened here is an FX glitch. The buy price was for Sirius Real Estate (LON:SRE) was €0.59. So at about 57 pence the position is in profit.
This doesn't seem to be visible in the Fantasy Fund trading history, but in the personal Stockopedia Folio where I also track this fund it is shown clearly:
Regards,
Roland
Hi Roland,
Did you see McColls already? I notice news this morning that has sent the share higher.
Carey
Hi Carey,
At first glance it seems like a smart deal for McColl's Retail (LON:MCLS) and WM Morrison Supermarkets (LON:MRW). The market certainly seems to like it.
Regards, Roland
I have bought all three off them and I hope to make some money out off them. I will love to see your portfolio .I am not as clever like you .I have no investment qulification
thanks
Romman
Hi Romman,
Thanks for your comment. You can see the portfolio I discuss in my articles here:
http://www.stockopedia.com/fantasy-funds/stock-in-focus-portfolio-6449/
Just to be clear, this is a fantasy portfolio so doesn't use real cash, although I do own some of these stocks myself as well.
Regards,
Roland
Very good and very informative look forward to the next