SIF portfolio: Sirius Real Estate returns & 3 new foreign stocks

When following a rules-based investing strategy like the one I use for the SIF portfolio, the line between trading and investing can get blurred. In his recent interview with Ben Hobson (recommended reading), US trader Mark Minervini suggested that “an investor is someone who holds for long term capital gains; one year or more rather than weeks or months”.
By that definition, I guess the SIF portfolio’s minimum holding period of nine months means that it’s leaning towards being trading, rather than investment. Certainly this week’s choice of stock might suggest to many investors that I’m a trader!
Sirius is back!
Back in November, I sold the portfolio’s virtual holding in German commercial property firm Sirius Real Estate for a total return of 29%.
This company operates business parks in Germany, providing flexible workspace. It was a successful holding for the SIF portfolio. But forecasts for lower earnings in 2018 meant that it no longer satisfied my screening requirement for 1-year forecast earnings growth of at least 5%, so the shares were sold.
The passing of time means that 1-year forecast earnings are now weighted towards 2018/19, a year in which the company’s earnings are expected to rise by 25%, according to consensus forecasts:
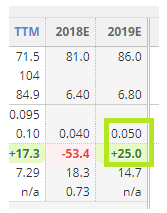
A strong set of H1 2017/18 results means that this stock now passes all of my screening rules.

Indeed, Sirius Real Estate is currently the only stock in my screening results that I’m able to add to the portfolio, once existing holdings and sector duplicates are excluded.
Is it still worth buying?
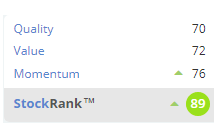
Sirius still scores highly across the board, with a StockRank of 89 and Super Stock status.
You can read my original write-up of Sirius Real Estate from March 2017 here. I’m not going to recap all of this, as not much has changed. The only thing that is different is the maturity of the group’s portfolio.
Over the last year, the firm has sold some of its more mature assets and bought a number of new sites, often with low occupancy. Management expect to create value for shareholders by updating and remarketing these, as they have done successfully in the past.
This process is expected to have a short-term hit on earnings, but should drive medium-term growth in both earnings and net asset value.
Despite this, the valuation has remained quite strong, thanks to market conditions and perhaps investor confidence in this business. When I first added Sirius to the portfolio, it was trading at a 5% premium to net asset value (NAV). That premium has increased:
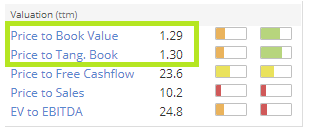
I would prefer to buy at a lower valuation. But I’m willing to go ahead here for two reasons:
Most companies in the managed workspace sector are currently valued at a premium to book value. As with UK housebuilders, this shouldn’t be a major risk while the German economy remains stable.
I think Sirius has a fairly good track record of execution. So I’m hoping for a repeat performance.
The right time to buy?
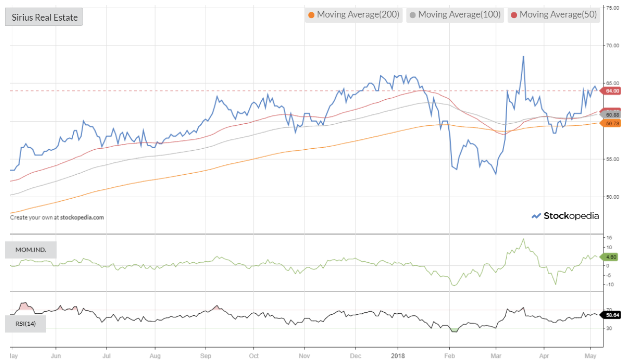
I don’t dwell too heavily on technical factors when adding stocks to the SIF portfolio. But in this case I think the chart setup looks reasonably good. The stock looks like it could be positioned for another leg up:
My decision: I will be adding Sirius Real Estate to the SIF portfolio and to my own real-money portfolio this week.
3 new International SIF stocks
The international version of my SIF portfolio has now reached 18 stocks out of a target of 24. I add three new stocks each month to this virtual portfolio, which I launched in November.
Here’s how the portfolio looked at the end of April (apologies for the small print):
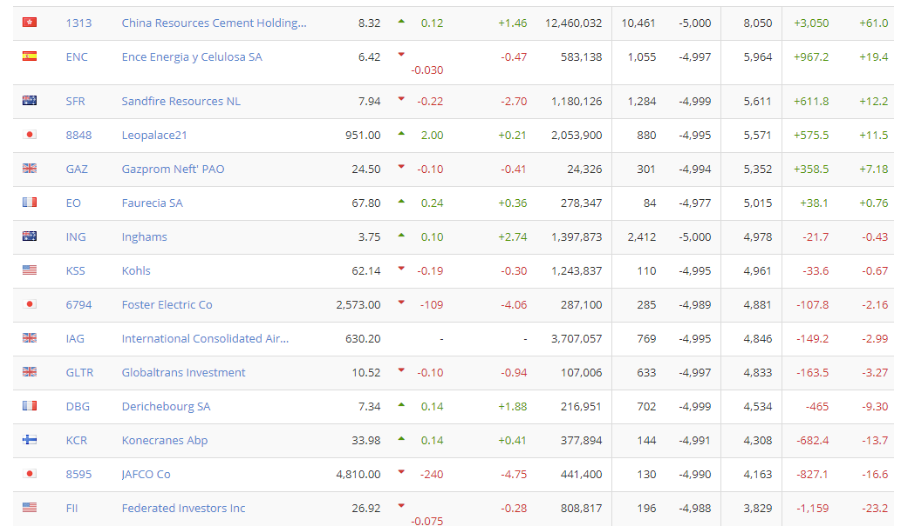
I think it’s fair to say that the screening results for this portfolio pose some interesting questions. As UK investors, perhaps the most relevant issue is whether we’re missing out by not looking at more EU companies. There seem to be a lot of attractively-priced, mid/large cap European stocks available at the moment.
Looking further afield, the same can be said of China (under Hong Kong listings). The risk here may be ‘differing’ standards of corporate governance and accounting presentation.
As it happens, my International SIF selections for April included one Chinese firm, one EU company and one UK stock. See what you think.
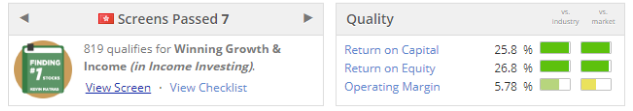
Tianneng Power International (HKG:819)
This £1.2bn company makes lead-acid and lithium rechargeable batteries. These are used for electric bicycles and tricycles, as well as cars. It’s a growth market for sure and right now I think I’d rather own shares of this firm than I would of Tesla.
Stockopedia’s computers are also impressed. Tianneng has a Super Stock classification, a StockRank of 99 and passes no fewer than seven Guru Screens. These include Winning Growth & Income, which has delivered an annualised return of 21.6% in the UK since the end of 2011.
Earnings per share are expected to grow by 15%-20% per year over the next couple of years, making the forecast P/E of 7.6 looks very reasonable. Return on capital employed rose to 25% in 2017 and cash generation appears strong. If these figures can be maintained it could be a rewarding buy.
Mytilineos Holdings SA (ATH:MYTIL)
This is a Greek industrial conglomerate with interests in aluminium and zinc production, plus gas-fired and renewable electricity. The group also owns a large engineering, procurement and construction business that specialises in building power plants.
This £1.3bn enterprise currently trades on a forecast P/E of 7.7, and at 1.5 times its tangible book value. Both figures look modest to me. There’s also a well-covered 3.8% yield, and debt levels look acceptable.
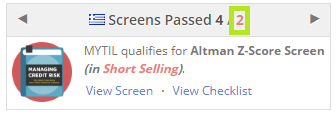
Perhaps my biggest concern is that this stock passes two of Stockopedia’s short-selling screens, the James Montier Trinity of Risk screen and the Altman Z-Score screen. Why is this?
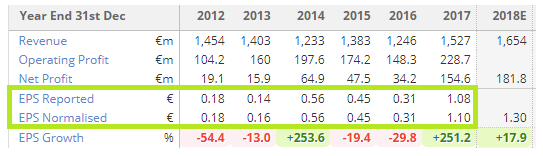
Looking more closely, the stock fails the James Montier screen because earnings have grown very rapidly over the last six years:
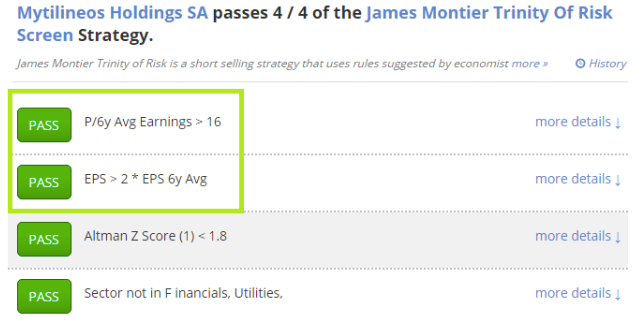
I’m not sure what to make of this without further investigation, which isn’t part of this portfolio process. Earnings growth over the last six years doesn’t look that suspicious to me, given that Mytilineos is exposed to the cyclicality of both the mining and energy sectors:
We will see.
Keller Group (LON:KLR)
The third stock to join the International SIF in April was FTSE 250 geotechnical contractor Keller Group. This business is effectively a high-end groundworks specialist whose portfolio includes oil refineries and providing the foundations for Australia’s tallest building.
It’s a company with which I’m already familiar, as it joined the main SIF portfolio in January. You can read my original write-up of Keller here. The comments section includes some interesting feedback from member muckshifter, who has industry experience.
Muckshifter’s comments confirmed my view that this is a genuine specialist business, not a commoditised construction business. This means that margins and pricing power should generally be stronger and more defensible than elsewhere in this sector.
I remain a bullish on this stock, which I own myself. Stockopedia also likes the shares -- Keller scores a StockRank of 99 and a status of Super Stock.
Disclosure: Roland owns shares of Keller Group
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

7 comments
looks like you called the SRE sale perfectly as it drifts down to 55p now, well done.
Hi Roland,
i would be interested to hear how you are getting on buying the stocks from the international screen, and how easy or hard is it for a UK based investor to participate practically?
Regards
Jim
Hi Jim,
The international version of the SIF portfolio is strictly a virtual portfolio, which I'm developing as an experiment. I don't own any of the stocks unless disclosed otherwise (at present only one or two of the UK stocks).
I don't have much experience of investing internationally. My impression is that for mid/large caps it's easy enough to invest in EU and US stocks. I know some brokers also cover the main Asian markets. The big spread betting firms also provide a good choice of markets - at least IG does.
Regards,
Roland
Hi
Have started buying the SIF portfolio and SIF international portfolio. But for the international will limit it to Asian and UK quoted as thats what I have paid screens on.
Looking forward to the next article.
PS trying to keep some cash as believe its been along time since a bear market which is only a matter of time away. Currently at 20%. Be good to have an article on just how much cash one should have. My feeling is the same analysis can go into that cash balance level as the SIF stock picks. So surely over time there is a cash % level thats right to have x years after a bear market has ended? I sleep well knowing I have both camps covered.
Hi Oaktree,
Thanks for your comment. I should emphasise that my articles represent my opinion only and are not advice to buy and sell stocks. Although I own most of the stocks in the UK SIF portfolio, the international version is a virtual portfolio only.
As for cash, I agree that it can be difficult to find a balance between decent opportunities today and the potential for better opportunities in the future. I don't think there's a single right answer. In my view, the correct amount of cash depends on an investors' personal strategy.
In my experience, some trial and error is required to find the right balance between cash and stocks.
Regards,
Roland
Hi oaktree,
One other thought on cash balances. In the case of the SIF portfolio, where stocks are bought/sold according to a fixed schedule and screening rules, there's no need to build up a cash balance. The aim is to stay invested without trying to time the market.
Although the portfolio does have some spare cash at the moment (https://www.stockopedia.com/fantasy-funds/stock-in-focus-portfolio-6449/), this is the result of capital gains over the last two years. I've actually increased the Fantasy Fund's allocation to each new stock from £50k to £55k this year, to try and reduce the cash balance.
Cheers,
Roland
Thanks Roland. I used to be of the mindset that one should be fully invested as over the long term thats the only way to make money ie the market over time goes up. But things are so volatile I do like a bit of cash especially now we are 9 years after a bear market. Jim Slater opened by eyes to this when he wrote about it in the Zulu principle.
Thanks for all your posts.