SIF Portfolio: Why Ferguson's US focus could warm up my returns

Market conditions have remained uncertain in recent weeks, with profit warnings and poor trading updates punished severely. We’ve also seen shareholder wealth permanently destroyed at Conviviality and (I suspect) Mothercare, as Graham discussed on Monday.
The SIF portfolio has managed to avoid this kind of distressed situation so far. Performance against the FTSE All Share benchmark has remained satisfactory, in my opinion:
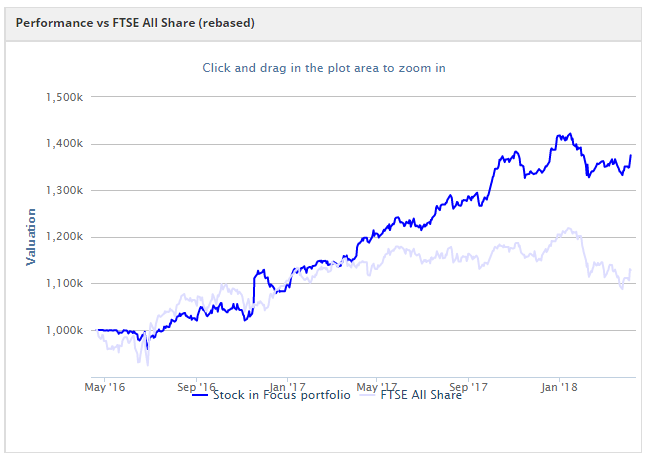
However, I haven’t felt able to add many new stocks recently. Although companies have continued to qualify for my own Stock in Focus screen, very few of these are new. And many are in sectors already covered by existing portfolio stocks.
Here’s a list of the companies which currently qualify for the screen. I’ve highlighted them using the colour code below so you can see how few new stocks are available for consideration at the moment.
Already in SIF (green)
Previous SIF stock that has qualified again for the screen (blue)
Direct overlap with a SIF stock or not eligible for some other reason (red)
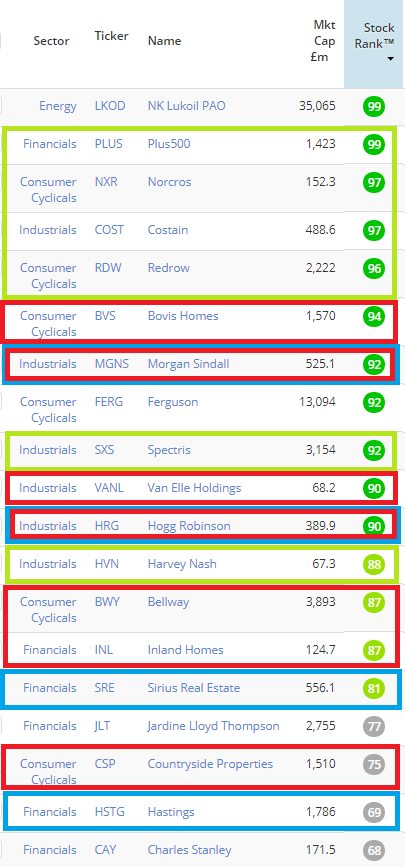
The graphic above shows that there are seven stocks I could consider adding to the portfolio:
- Russian oil and gas group NK Lukoil
- US-focused plumbing and heating supplier Ferguson
- German commercial property firm Sirius Real Estate
- Specialist insurance and employee benefits group Jardine Lloyd Thompson
- UK motor and home insurer Hastings
- Investment manager Charles Stanley
My rules specify that I should consider stocks with the highest StockRanks first.
Starting at the top, I’m going to rule out NK Lukoil despite a StockRank of 99. My previous experiment with Russian stocks delivered mixed results. The imposition of US sanctions against a number of oligarchs makes me even less keen on investing in such firms.
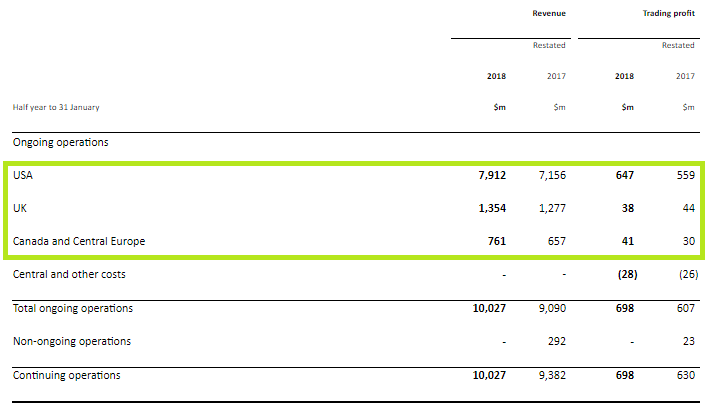
The next qualifying stock on the list is FTSE 100 plumbing and heating supplier Ferguson. Although this is a UK-listed company, about 90% of trading profit now comes from the USA. A further 5% or so comes from Canada and Central Europe. The UK accounts for the remainder.
I think it’s fair to view Ferguson as a play on the US economy. In contrast, the portfolio’s other property-related stocks (Redrow, Norcros and Costain) are mainly focused on the UK. So I don’t think there’s too much overlap with Ferguson, which I’m going to consider adding to the portfolio this week.
Heating and plumbing US homes
Ferguson describes itself as “the world’s leading specialist distributor of plumbing and heating products”. The group was formerly known as Wolseley and still operates under this name in the UK, where it has more than 600 branches.
Ferguson is the name of the company’s main US business, hence the name change. As in the UK, this operation is focused on the Repair, Maintenance and Improvement (RMI) market. Most business comes from the residential and commercial sectors. Industrial property generated just 7% of US revenue last year.
This focus on RMI means that the firm has a fragmented and highly local customer base of tradesmen and local firms. Ferguson’s website says that “the majority” of its customers operate within 20 miles of one of its 2,310 branches.
The segmental figures from the recent interim results show how the group’s business is skewed to the North American market:
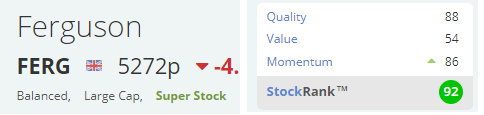
The shares have been largely flat so far this year, but have attracted the attention of Stockopedia’s computers, which have awarded them Super Stock status and a StockRank of 92
A growth valuation
Ferguson’s ValueRank of 54 is the lowest of its three factor scores. Do we need to be worried by this, given the looming possibility of a market correction? Let’s take a closer look:
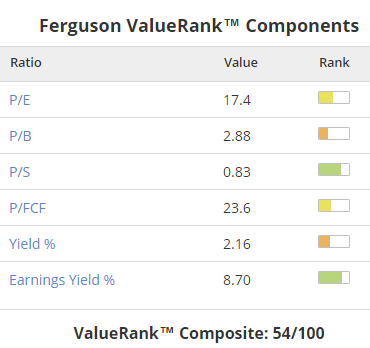
There doesn’t seem to be anything alarming here. Although free cash flow lags earnings, I suspect this is probably down to regular small acquisitions and wider investment in growth. The earnings yield of 8.7% is above my threshold of 8%, suggesting that the business as a whole is reasonably valued, despite a trailing P/E of 17.
According to Stockopedia, normalised earnings per share and the dividend have risen by an average of about 11% per year since 2012. This seems to confirm the group’s credentials as a big cap growth stock:
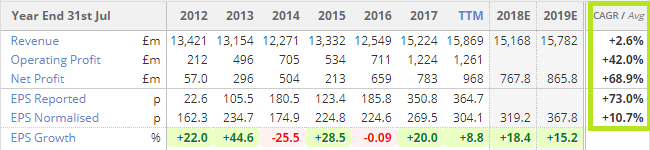
This growth rate is well above the FTSE 100 average. As profits have also risen much faster than sales, we can assume that margins have improved too.
Can this performance be maintained?
Watertight quality?
A QualityRank of 88 suggests that the group’s finances are in good shape.
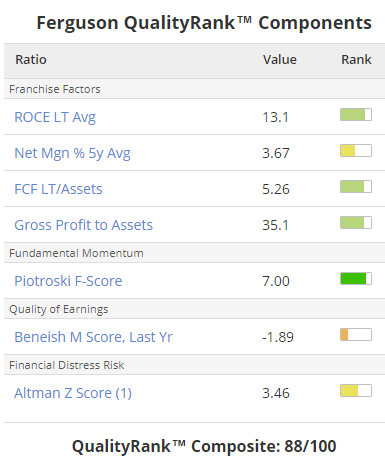
These figures provide more reassurance than the ValueRank, in my view. Although the Beneish and Altman scores are relatively low, neither are low enough to trigger warning flags on the StockReport page.
I’m also encouraged by the Piotroski F-score of 7/9. This confirms the group is delivering cash-generative growth, even though cash generation is lagging profits:
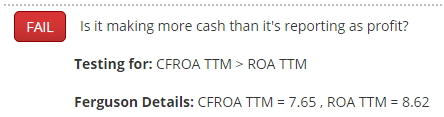
I think it’s worth monitoring the group’s results for evidence of falling returns or weaker cash flow, but I don’t think this is a concern at present.
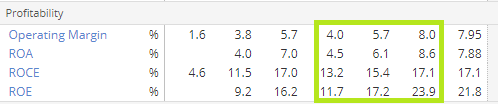
Looking at the yearly figures from the StockReport, it’s clear that margins and ROCE risen over the last few years. I’m going to wait for this year’s FY figures before making any further judgement:
Rising momentum
The final ingredient of a successful SIF stock is momentum.
Ferguson scores highly in this area, with a MomentumRank of 86. This figure has risen by 12 points over the last 30 days, presumably since the interim results were published on 27 March.
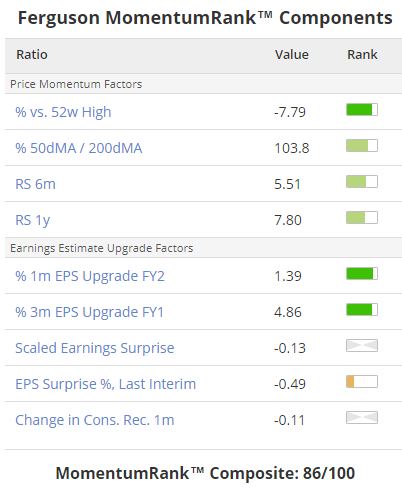
The shares are showing good price momentum, with green bars on all four measures of technical strength. The earnings picture is slightly less confident, but broker estimates for the current year (FY1) and next year (FY2) have edged higher over the last few months:
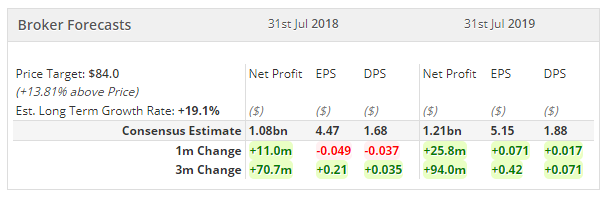
This continues an upward trend that’s delivered a 10% upgrade to 2017/18 earnings since last July:
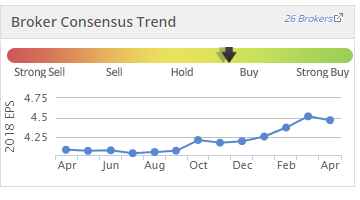
Although consensus forecasts dipped slightly following the recent interims, this was only a 1% drop. As this consensus view represents the average of 26 broker forecasts ranging from $3.89 per share to $5.97 per share, I’d argue this is no more than a rounding error (using forecasts published by Reuters).
Is this story still unfolding?
I don’t normally buy shares in the hope of corporate action, but I can’t help wondering if Ferguson’s evolution into a US business could still have further to go.
The group recently sold its Nordic business. The European and UK businesses are also starting to look like non-core activities to me. I wonder if these might be sold too, and the proceeds used to further expand its US footprint?
My decision
I’m going to add Ferguson to the SIF portfolio this week. I will also buy the shares myself, after this article has been published.
Disclosure: Roland owns shares of Redrow, Norcros, Costain, Harvey Nash, Plus500 & Spectris.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

No comments yet
No one has commented here yet! Why not be the first one?