Small Cap Value Report (Mon 9 Apr 2018) - CVR, FCCN, MTC, KWS

Good morning, folks.
Apparently, there has been a technical fault with the company announcements RNS feed this morning. Let's hope they fix it soon!
8:45 AM update: there was a large release of announcements at 8:25, so I'm going to assume the backlog has been cleared. Some companies reporting which we follow here include Keywords Studios (LON:KWS), French Connection (LON:FCCN) and Hollywood Bowl (LON:BOWL).
Was anybody caught out by disorderly trading in shares whose news was delayed? There is a risk that some shareholders might have been disadvantaged by the delayed release, to them, of important information.
As an aside - I remain in favour of the US system, where news is announced after the market closes in the late afternoon/early evening. I can't see any downsides to doing it that way!
Conviviality (LON:CVR) (suspended)
A quick post-script on Conviviality, and the final outcome for its two divisions ("Direct" and "Retail").
The news has been positive for employees, customers and suppliers, as a series of deals are likely to have saved many jobs and will lead to the continuation of most of the group's activities, under new owners.
C&C (LON:CCR) (owner of Magners/Bulmers, Tennent's, and other drinks brands), with the support of the giant brewing company AB Inbev, has bought Conviviality Direct, including Matthew Clark and Bibendum.
Bestway, one of the UK's biggest food and drinks wholesalers, has picked up "the business and assets" of Conviviality Retail, but the sale proceeds won't be sufficient to pay off creditors:
It is with regret that the Board notes that the companies are not expected to have sufficient assets to satisfy all their liabilities.
PricewaterhouseCoopers will be in contact with creditors of Wine Rack Limited, Bargain Booze Limited and Conviviality Retail Logistics Limited. The Board also understand that the realisations will be insufficient to provide any return to shareholders.
The new owners are likely to have a more sober view (pun intended) of the true worth of Matthew Clark, Bibendum, Bargain Booze, Wine Rack, etc,, compared to Conviviality.
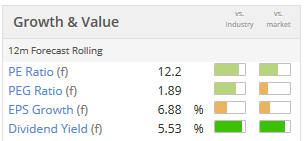
I hope that none of our readers were too heavily invested in CVR. The story continues now with C&C (LON:CCR), at least as far as the wholesaling activities are concerned. Here are its latest value metrics in case you might wish to investigate it further (it is beyond the market cap limits of this report):
With confirmation that shareholders will receive nothing, and the subsidiaries having been sold off, I intend to cease coverage of CVR now.
French Connection (LON:FCCN)
- Share price: 52p (+21%)
- No. of shares: 96.3 million
- Market cap: £50 million
Proposed Sale of Toast to BESTSELLER
Paul owns shares in French Connection, and writes for us:
"Interesting announcement from FCCN - disposal of Toast, for what looks like a good price.
I reckon Stephen Marks is tidying up the business, to maximise the value for ultimate sale of the whole business. He's in his 70s now, so must be looking for an exit at some point. Also, they mentioned in a recent results statement that they'd had an unsolicited takeover bid for the whole group, and had spent several months in negotiations in due diligence.
So it's clear the whole group is "in play" now, I reckon. Could be great upside, as it's moving into profit this year, due to disposal of loss-making shops. Also the balance sheet is bulletproof - market cap is similar to just its working capital, which seems crazy to me. I'm very long on this one, as risk:reward looks favourable to me."
My opinion
I agree with Paul that this is a good price - French Connection are getting paid 12.2x Toast's most recent EBITDA. It also means good things for French Connection's net cash position, which has been sliding for many years:
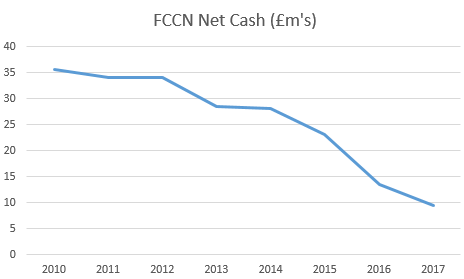
(Source: RNS announcements. Chart by GN.)
Net cash proceeds to FCCN will be £13.9 million, but this includes a £2 million special dividend from Toast which I believe should already be included within FCCN's net cash.
So taking that into account, I think FCCN's net cash will increase by about £12 million to £22 million, or a little over 40% of the current market cap.
Governance Issues
This is a share which I unsuccessfully attempted to trade back in 2015.
One of the issues which has nagged me about it is the impression I have of the Chairman's attitude to shareholders.
A fellow investor took the trouble of attending French Connection's poorly-attended AGM a few years ago, and was flatly refused the opportunity to ask any questions during the meeting.
Some might consider this to be a minor issue, but the Chairman's attitude to the City for many years has been one of disdain. And he continues to hold both the Chairman and CEO roles despite this being a very basic no-no as far as corporate governance is concerned. The UK corporate governance code states:
There should be a clear division of responsibilities at the head of the company between the running of the board and the executive responsibility for the running of the company's business. No one individual should have unfettered powers of decision.
Don't misunderstand me - as the major shareholder, he is perfectly within his legal rights.
Furthermore, having held a net cash position, albeit a shrinking one, the company has not needed any financial support from its minority shareholders. So it has been able to afford not to care very much about their views.
But I think this does need to be reflected in the share price. If it had not been for his major shareholding, the Chairman would have been removed from the position of CEO many years ago. The shares need to be discounted, to reflect this issue.
One way to approach it is to apply the "discount to tangible assets" test, which I applied to another loss-making retailer, GAME Digital (LON:GMD). (I own shares in GAME Digital (LON:GMD). It does not have any corporate governance issues that I am aware of.)
At the latest results, French Connection had net assets, excluding intangibles, of c. £46 million. This will be boosted by the Toast disposal to £50m+.
So French Connection shares are also trading at some discount to tangible assets, giving shareholders an opportunity to buy the value of the French Connection brand "for free".
Therefore, I can see the potential for this to be another profitable trading opportunity, if assets can be sold off and stores closed efficiently (there are about £33 million of currently off-balance sheet lease liabilities to be shown on the balance sheet, when new financial reporting rules are implemented).
It's quite possible that I am missing out on a fine opportunity, but I would need a 50% discount to tangible assets to want to get involved with this share again, due to my corporate governance concerns and my view that the Chairman has zero interest in minority shareholders.
The algorithms love it, again underlining the fact that I am probably missing out on the chance to buy a share with good prospects:
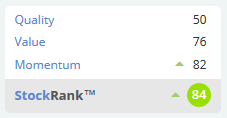
Strangely enough, Sports Direct owns a big chunk of shares in both French Connection and Game Digital. It will be fun to see how the Sport Direct share portfolio turns out in the long run!
Mothercare (LON:MTC)
- Share price: 16.8p (-14%)
- No. of shares: 170.9 million
- Market cap: £29 million
No RNS announcement from Mothercare today, but the papers reported over the weekend that it is considering the potential for a CVA to shut down 47 of its 143 stores, and change rent terms on the others. Well done to Paul for predicting that a CVA was on the cards.
Mothercare's share price started 2018 around 65p and continues to make rapid progress toward zero, as it approaches a resolution of its financial problems. Lenders agreed to defer financial covenant tests last month, and discussions with them are ongoing.
Instead of letting traders speculate on its future according to these newspapers stories, maybe the company should come out and confirm that it is doing a CVA, if true?
I agree with the general consensus that this share is uninvestable, as we don't know what steps will need to be taken to satisfy the company's lenders in the weeks and months ahead. The appointment of a new CEO is interesting, but it doesn't look like it's enough to salvage the value of existing shares.
Retail bloodbath?
The phrase "bloodbath" has already been applied by US commentators to conditions in the retail industry across the pond, and it's an increasingly apt description to conditions over here, too.
I've just quickly revised the retailer exposure in my own portfolio. Key characteristics I'm looking for in my own retail holdings are intellectual property/brand ownership (e.g. £BRBY) or else very valuable and liquid balance sheets, with strong cash positions (e.g. Next (LON:NXT), £GMD).
In a more competitive and rapidly changing marketplace, companies without their own great brands will be eaten up by Amazon or by cheaper alternatives. So we have to be very, very selective in this sector. But there could be some great bargains on offer at the moment, if we can identify those companies which will survive the ongoing transformation to online.
Keywords Studios (LON:KWS)
- Share price: 1605p (+1.5%)
- No. of shares: 61.7 million
- Market cap: £990 million
This support services provider to the video games industry continues to go from strength to strength. It is now well beyond our usual upper market cap limit for this report.
I've enjoyed watching the management presentation posted at piworld today. One of the most interesting quotes I thought was this one, from the CEO:
"I sometimes pinch myself when I look at these numbers. This market [video games] is $120 billion in size and yet it is still an absolute niche market by any sort of measure... the product itself is very unique being this kind of mashup of the very highest creative content with the very technical cradle that it sits in... The market for services is both highly fragmented and also pretty large, it's about $5 billion in size."
The overall games industry continues to grow at a rate of 6-8%, and Keywords benefits from the ongoing trend towards publishers outsourcing much of their work to service providers such as themselves.
The Keywords strategy is simple enough: buy up smaller players in this market, integrate them and cross-sell to their customers an expanding range of capabilities. Services include art production, audio, localisation and functional testing. There is a new engineering line and Keywords is now increasingly involved in full game development.
Thanks to continued sales growth, no client represents more than 10% of revenues. So nearly all of the top video games publishers are counted as clients, and concentration risk appears limited.
My opinion
It's a great story and I'm not surprised that this share is a popular one among investors. The share price is up 10x in three years:
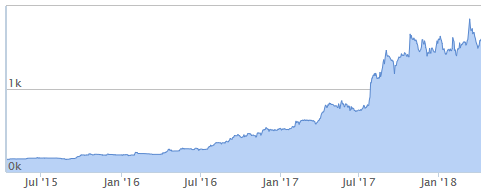
This is a successful company with a great track record of execution and favourable industry tailwinds behind it, so it deserves a strong rating.
Value metrics are as follows:
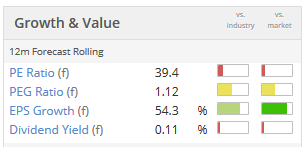
Note that the underlying revenue growth is 15%, which in my book is good but probably not enough to justify the 39x PE ratio reported above.
Two months ago, with the share price not far off the current level, I said:
It has performed brilliantly so far, but the risk of a mishap must surely be increasing, with the share price not leaving much margin for error.
I think I'll stick to my guns, and repeat this view today.
Games publishers themselves are trading more cheaply vs. earnings than Keywords, and they own the underlying brands, so I would instinctively prefer to own them rather than Keywords at current share prices. For example, Nintendo (TYO:7974) and Activision Blizzard (US:ATVI) are each trading at around 24x forecast earnings. Their EV/EBITDA ratings are less than half as expensive as Keywords, according to Stockopedia.
As customers of Keywords, they benefit from the opportunity to outsource their work. If it didn't benefit them, they could always in-source it again.
So I'm a fan of Keywords and I think it has a bright future, but I think the publishers are probably a better bet for investment at the moment.
That's it for today! Thanks for dropping by.
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

43 comments
I might be wrong but my understanding of insider trading is that anyone who trades with information not in the public domain is guilty of insider trading. If the official RNS service is down does this not make anyone who gets information from the company broker or Twitter for instance an insider. Are we supposed to ensure that information has been disseminated by RNS before acting or should bodies which receive embargoed information be obliged to check before emailing or twittering. I hope the FCA will look into this but I don't suppose they will.
Why do people on this thread keep bringing up Equity Development (ED)?
I've not seen the regulations but I'd imagine that a company like Keywords Studios (LON:KWS) has met all its legal obligations once it has filed with a regulatory information service (RIS) such as the London Stock Exchange's RNS.
Why should it not be permitted to report its profits etc. to shareholders just because the RIS provider has not got its act together? As for criticising Equity Development, it is likely that Keywords Studios (LON:KWS) and all the other companies reporting this morning had put their announcements on their own webpages anyway.
Don't blame companies, analysts, management, brokers or PR for their conduct this morning. Responsibilty lies firmly with the RIS provider for any false market created by their incompetence.
Asagi
Just posted the video of the Keywords Studios (LON:KWS) analyst presentation, this morning:
http://www.piworld.co.uk/2018/04/09/keywords-studios-kws-fy-results-presentation-9th-april-2018/
Andrew Day (CEO) & David Broderick (CFO) present the Group’s full year results to the 31st of December 2017.
KWS video overview – 00:21
Andrew Day, CEO
Introduction – 02:22
David Broderick, CFO
Financials – 16:53
Andrew Day
Strategy – 24:03
Q&A – 45:33
A request for Keywords Studios (LON:KWS) please. As usual the adjusted growth looks a lot better than the the basic, diluted version. But in this case it might make sense. Acquisitions are a fundamental part of the business model. And, based on the recent PI World presentation, they seem to be very good at choosing acquisition targets and integrating them well. Two larger than usual acquisitions during the year have brought higher than usual acquisition costs so maybe it makes sense to exclude at least these excessive acquisition costs. And they are building a leading position in a growing market with customers who, probably, find it easier to buy from the sort of one stop shop that Keywords Studios (LON:KWS) can offer.
Looking forward to reading your thoughts, Graham
Dislosure - I am long Keywords Studios (LON:KWS)
re: Keywords Studios (LON:KWS). Thanks for the suggestion, Julian. It's coming up next. G
Thanks, G. Much appreciated.
Thanks Sundaytrader Howard, Bruce & Matylda for your thoughts.
'- Its markets are defined entirely by government regulation. That is, they can only sell in those countries where the government has decreed that all polythene materials must be made with specific degradation characteristics.'
I'm not sure about this one though - with consumer sentiment running against non-biodegradables, surely one of their selling points is that oil companies & food companies don't really have to change their production methods too much, just add their additives to them. Ie that it's not a disruptor. I'd like to know if you've identified any serious competitors within plastic who might eat their shrink-wrapped lunch: there are plenty of non-plastic packaging startups waiting in the wings: https://www.theguardian.com/environment/shortcuts/2018/apr/09/the-edible-solutions-to-the-plastic-packaging-crisis Ta
I remember an article about edible plastic on the BBC's Tomorrow's World show. I reckon it was broadcast in the early Eighties. The presenter bit into a sandwich wrapped in an edible plastic film. I always wondered why anybody would want to eat a sandwich without unwrapping it first!
re Symphony Environmental Technologies
Sorry, I worded that badly. My understanding is that there are some purchasers of oxo-degradable plastics in the US and European markets, as there are also of other sorts of degradable plastics. But I think that there is limited scope for market expansion for any of the technologies without direction from the authorities (which is more or less what Symphony say in their own reporting).
A trading update this morning from Carclo (LON:CAR) – trading in line , but it’s what it doesn’t say that would worry me if I were a holder.
Discussed by Graham back in January and by Paul in November.
A brief recap, this is potentially an interesting growth stock on a modest valuation, but seems to slip up from time to time.
The HY results statement in November was imho slightly less than forthright – telling us that an
Except that EPS was down 20%, despite the previous expectation of c. 20% increase over the full year. “partially offsetting” was I think the phrase they were searching for.
On the underperforming Technical plastics division we were “reassured” that :
And that
HMM
Forward to a January Trading Update and we learned that
I bolded the second part there as I think it is very pertinent to today’s announcement.
(incidentally on the January announcement the price fell from the 120s to 80s)
Although it could be argued that these delayed orders now have nothing to do with the current year performance and the trading update purely related to the current year; I cannot help but think that if they had closed or made substantial progress on these orders, they would been at pains to tell us.
In this case I would conclude that no news is NOT good news.
The shares are largely unmoved this morning, as you might expect for an inline statement , but personally I wouldn’t want to be holding up the results statement in early June – it would seem to me that the outlook statement is more likely to disappoint that surprise to the upside.
Stockopedia rates Carclo (LON:CAR) as a ‘value trap’ and that seems about right, it would require momentum to become a 'turnaround' and at the moment earnings momentum is in the wrong direction.
Can someone please tell me what is the US version of the RNS service we have here in the UK ?
It's called EDGAR (an acronym for summat!) https://www.sec.gov/edgar.shtml
ah thanks, i just took a look, crikey its not very user friendly ,it doesnt seem at all like the FTSE RNS. The actual rns announcements arent great but at least we have investegate which does a great job of the formatting.
extra questions, do you know if US companies are obliged to release trading updates like FTSE stocks ? and do they have interims and prelims like over here ? ive heard in the US they have 'earnings season', do all companies have to report during a specific time of the year ? or if anyone else knows please let me know.
Symphony Environmental Technologies (LON:SYM)
Just my quick post-it note view...
Fundamentally...
Revenue up 20% or so, forecast for 10% next year.
EPS up over 100%, forecast for 50% next year. Revised up from 0.1 to 0.4 in the past 6 months.
Operating Margin OK at 5.8%.
ROCE a massive 30%.
Debt Free.
Where's the kicker going to come from? Probably needs to come from more take up by countries in the Middle East and the European and US markets - I believe they have recently announced some activity in Italy.
Technically...
From a Minervini point of view (or my view of his view), it's above the 50, 130 and 200 MA's which are all in trending up and in the appropriate order. It's also up over 50% from the 12 month low and within 25% of the 12 month high.
Summary...
Would have been nice to get the break-out at 19p so I am interested - It's a case of paying up or waiting for a retrace as all round it seems fine to me. I guess the only question mark would be the kicker.
As I say, just chipping in, with my quick post-it note view.
As somebody who has decided alarm clocks have absolutely no place in a civilised retirement, I wholeheartedly agree that RNS should be released after market close, especially results and trading updates. However, there are some companies that issue news mid-session. A recent example if this was Games Workshop (LON:GAW) who issued a trading update and dividend declaration because they held their board meeting during market hours.
The whole system needs reviewing in my opinion but I doubt that it will be.
One issue with making UK trading and results statements after market close would be for shares with dual UK/US listings - where the announcements would be made during market hours in the US.
Unless those announcements would be further delayed until the close of US trading (I doubt that would go down when for companies whose primary listing is UK)
Does anyone know how results are dealt with for stocks with a dual US/Asian listing?
What difference is that from 7am? If they were released at say 11pm for Dual listed US shares? Some dual listed ones are issued at odd London times. The US system you have all night to study them rather than just 1 hour before the market opens, this is often a time people are travelling to work or busy.
The likes of Equity Development should check that results are out and on the screen before twittering/tweeting about them.
A mention in the Sunday about Deltic and apparently the 6 mth takeover limitation on Revolution Bars (LON:RBG) is up by tomorrow. The story on Deltic was how they could list if the markets are reasonable shape (by next year, I think).
Encouraging for Revolution Bars (LON:RBG) that Deltic is still looking to get to a situation where their shares are publicly traded - that means they're probably still actively looking to merge/reverse into RBG to achieve the same public listing.
Yes I quite agree about the US system, would give everyone more time to read them. If they come out an hour or 2 late it’s still not an issue. My noticification service is not always on time either.
Update now done, nothing exciting mind you - Carclo (LON:CAR) and Hollywood Bowl (LON:BOWL).
Anyone with any idea what happened this morning, I mean why the news wasn't released at the usual time?
French Connection (LON:FCCN)
Agree to sell Toast brand for £23m, my initial view is that this was selling one of the best performing parts of the business. Then i looked at the growth of Toast and its nothing special (up 13% y/y for revenue), so this could represent a good deal.
Questions for me:
- was this the bid approach that was hinted at in the prelims?
- is French Connection better off breaking itself up into a sum-of-parts, where they sell off the wholesale business and the retail arm separately?
- will management be successful in using the cash effectively in turning around the business to be profitable - is this a good use of the capital?
In reply to mrrobistan
No - the bid approach was for the whole group. Re FCCN RSN "During the year we received an unsolicited approach about a potential offer for the Group from a third party in the US". Hopefully this indicates they seriously are in play.
The £13.9m proceeds highlights how low the £45m market cap of FCCN is.
With the sale of the Regent Street lease and now this is makes you wonder what else they have tucked down the back of the sofa.
Ah - Thanks guys - Just noticed the news coming in, alerted by Beginner on my thread (thanks for that). Working on an update now.
Hi matylda
Perhaps "false market" was the wrong description.
If we take the example of KWS:
- The market opened as usual at 08:00
- Equity Development tweeted a summary of the FY results at 08:09
- The FY results were issued via RNS at 08:25
So, the results were available to people who follow ED on twitter before it was to those people who just rely on the normal news feeds.
Very messy at best IMHO.
And insiders at Keywords Studios (LON:KWS) knew about the RNS at 8.00 and, presumably, could trade on it. Whereas the rest of us couldn't. If that's correct then I don't think "false market" is too wide of the mark.
timarr
Re Keywords Studios (LON:KWS) I think that ED releasing summary results ahead of the RNS release is sufficient to justify the term 'false market'; not that I mean to blame Equity Development particularly for that fiasco, rather than the London Stock Exchange. Though, in view of what happened this morning, perhaps ED (and others) ought to change its procedures such that they only release summary results/commentary AFTER they have confirmed the relevant RNSs have actually been published by the London Stock Exchange. (No position in Keywords Studios (LON:KWS) )
It's got nothing to do with ED: the point is that some people knew about the announcement and could trade on it, and some people couldn't. I'm not even sure what the rules would be in this situation if an insider traded at the opening on the assumption the information was in the public domain.
Disorderly market, perhaps, but certainly not a fair one.
timarr
Re Keywords Studios (LON:KWS) and disorderly markets, my view is that no-one should be allowed to trade on information until they have confirmed that the RNS has actually been published, similarly, no-one should be releasing privileged information until they have confirmed that the relevant RNS has actually been released and hence the information is no longer privileged. If the rules don't reflect this then I think the rules should be changed. I'd forgive ED this time. If it happened again I wouldn't be so forgiving and I would not agree that it's got nothing to do with ED; but I'm happy to agree that, this time round, it is the London Stock Exchange that needs to account for its actions.
EKF Diagnostics Holdings (LON:EKF) are really motoring as of late... perhaps due to this announcement today:
EKF Diagnostics Holdings plc (AIM: EKF), the AIM listed point-of-care business, announces US Food and Drug Administration 510(k) clearance and CLIA waiver by statute for the Company's hand-held reagent-free hemoglobin analyzer, the DiaSpect Tm, approving the product for use in point of care and Certificate of Waiver settings.
The DiaSpect Tm provides users with accurate hemoglobin measurements within two seconds of the microcuvette being placed into the analyzer. It is palm-sized, easy to transport and is battery operated for remote use
Fulcrum Utility Services (LON:FCRM) are also really picking up momentum now, up another 4% so far today.
Keywords Studios (LON:KWS) results are out today... everything up about 55%, with the usual plethora of acquisitions... but at 1550ish probably high enough...?
Does anyone here have any opinion on Symphony Environmental Technologies (LON:SYM) ? I was keeping an eye on it but let it get a bit high (PER now 52) while away. New exciting board member appointment Friday pushed price up 11%, hot sector (biodegradable plastics), making a greatly increasing profit, but some concerns it might be a lifestyle business.
EDIT: Just found this: https://www.stockopedia.com/co...
RNS announcement just released this morning
https://www.investegate.co.uk/symphony-environment--sym-/rns/remarks-delivered-at-2018-ecosoc-partnership-forum/201804090810342363K/
Looks an interesting one - some thoughts already in this thread:
https://www.stockopedia.com/content/symphony-environmental-technologies-ndash-under-the-radar-high-flyer-342793/
Hi runthejoules
I have recently bought Symphony Environmental Technologies (LON:SYM).
It passed all 19 of my Minervini styled tests (these test momentum, earnings, sales and profit growth, debt and trading volumes).
It's in clear bull territory according to Ichimoku screen http://www.ichimokutrader.com/ (my many thanks to PhilH for introducing this tool to me).
Its been in a positive buy status for 4 months according to my Trade Stops volatility assessment tool set, although it has a high risk volatility quotient (the proprietorial algorithm embedded in the tool).
According to Investors Chron. 15.92% of shares are held by 10 institutions. This is not that high but quite a positive for such a small company and volumes are noticeably heightened from early 2017. Again a positive sign in Minervini's book. I hope Symphony Environmental Technologies (LON:SYM) is moving into a new base camp and not a Phase three, but I'm willing to assess it's the former. We shall see.
In addition to the quants side of an investment case I also think the qual side has some merits as the plastic issue is now centre stage at a global level.
I am however entering it very cautiously and will apply a strict exit 50% if it drops or 100% if it really goes against expectations (Minervini rules). (this is a very small position in my portfolio though).
Regards
Howard
Looks like all we can discuss is the abject lack of RNSs, perhaps due to the incompetence of the LSE. Trust they won't allow the markets to open at 8 a.m. given the greatly increased potential for insider trading.
Working now. At what point is this not creating a false market?
timarr
Obviously a false market is not important to those people who decided how to deal with this problem!!
Think they should have delayed opening the market to say 09:25 this morning to allow the normal hour for RNSes to be read and digested.
All IMHO.
Cheers, Martin
I don't understand what you are saying here, do please add more.
I have heard of Symphony Environmental Technologies (LON:SYM) but never looked at it in detail. It's been around for more than a decade, so my question is how come their technology has not been widely adopted before? I agree plastics in the ocean is a problem (and getting worse) but I'm surprised that Symphony Environmental Technologies (LON:SYM) has not delivered better results, and wondered what has changed now?
Issues with Symphony as an investment are
- Low "moat" The degradation technology which they sell is well-established basic chemistry which can be and is replicated by anyone who cares to enter the market.
- Its markets are defined entirely by government regulation. That is, they can only sell in those countries where the government has decreed that all polythene materials must be made with specific degradation characteristics.
- To date, regulators in the US and EU have not deemed this the right way to go for dealing with polythene pollution. As with anything environmental, the issues are complex, and it is a reasonable argument that it is better to go with a simple and cost-effective solution, rather than for more "perfect" but less attainable solutions. Still, until that "reasonable argument" finds favour, Symphony's markets will remain limited.
All that said, so far as I can tell, Symphony's management look competent and making a good shot at the opportunities that are available.
A back to bed day - Perhaps!
I believe the technical term is 'a duvet day'...
If you have a hangover, feel free to call it a duvet day!