Small Cap Value Report (13 Mar 2015) - AFR, DTG

Good afternoon. Apologies again for being late today - I've not done very well this week, have I? Still, all reports have been completed in the afternoons or evenings, so I added some more comments on Cambridge Cognition Holdings (LON:COG) and Essenden (LON:ESS) to yesterday's report last night. Here is the link for yesterday's complete report.
Afren (LON:AFR)
Trading update & refinancing - I can't give a view on this share here, as I currently hold a short position in it, although my intention is to close that position soon, once my price target is hit (not far off now). However, for information I've prepared a summary of how the refinancing will work, which anyone interested can read on Google Drive, if you can read my handwriting! Hopefully people will find that useful info, whether you are long or short in these shares.
Also the company has prepared a useful presentation on its website, click here to download that, or the link is on the company's home page here (right hand column)
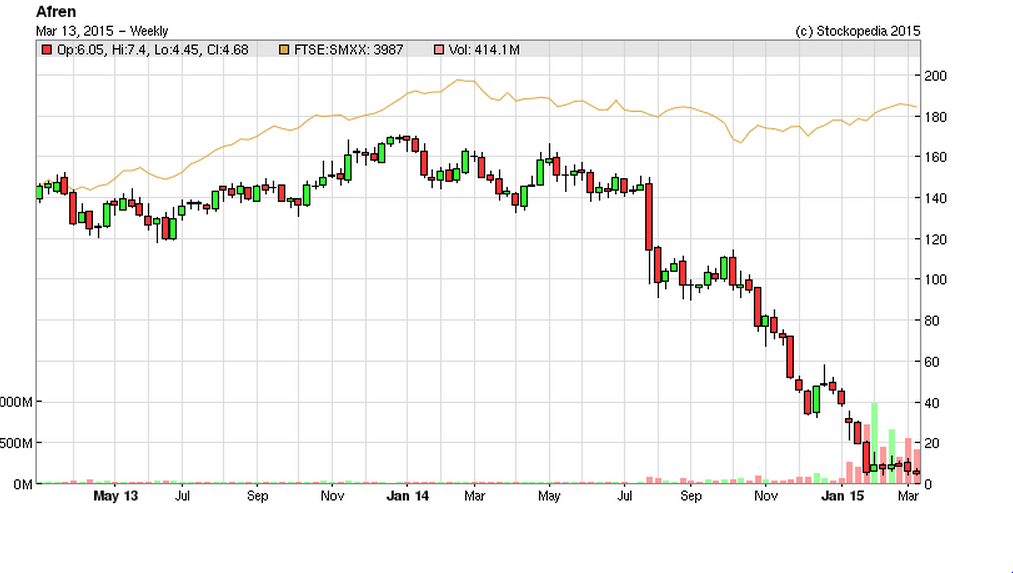
By my calculations today's restructuring deal is likely to lead to a 14-fold increase in the number of shares in issue from 1.1bn to about 15bn. So very nasty dilution for existing holders - this has been on the cards for a while, hence the collapse in share price.
Afren shareholders have certainly received a very painful education in how debt for equity swaps work, when a company is unable to meet the repayments or interest on its debt.
I worked in the insolvency department of a big firm of accountants in the 1990-92 economic downturn, so am quite familiar with this stuff. The key point in general, is that equity ranks behind creditors when things go wrong. So unless equity holders are prepared to refinance the company to a point where it can once again pay its creditors, then the situation can easily spiral out of control, with equity worth nothing potentially, once the company becomes formally insolvent. The assets are just then sold to satisfy the creditors, with shareholders getting nothing.
Afren has avoided insolvency by doing a deal with its creditors (the bond holders) which has ended up giving them the overwhelming majority of equity in the refinanced company. And it still has a mountain of debt too - so Afren is certainly not out of the woods yet, but it's immediate cash crisis has been dealt with. Shareholders have no choice but to approve the deal, in practice. A refusal to approve this deal would lead to a complete wipeout for shareholders.
Dart (LON:DTG)
Share price: 365p
No. shares: 146.9m
Market Cap: £536.2m
Trading statement - this has clearly delighted the market, with shares up 18% today. This seems a rather euphoric reaction, considering the company is only saying it will match last year's numbers (although it was expected to see a decline in profits);
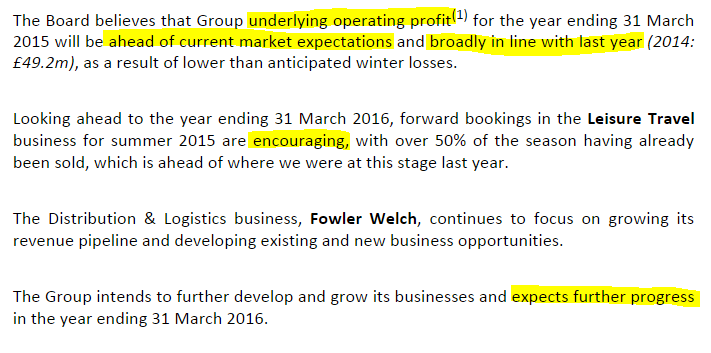
Valuation - Stockopedia shows current broker consensus forecast at 21.4p, but that now looks to be revised up to about 24.0p perhaps (since they did 24.3p last year). At 365p that drops out at a PER of 15.2, which is starting to look a little toppy for an airline in my view. easyJet (LON:EZJ) is on a PER of 12.4, for example, and pays a much better divi than Dart.
My opinion - if I held these shares, I'd probably be tempted to bank some gains on today's big move up.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

14 comments
On Afren I hold 25,000 shares at a cost of 9 pence each. Cannot decide whether to Hold or Sell at 3p and take a loss of £1,500.
Any advice appreciated.
Paul,have you taken full account of the cash in DTG ?
Looks like I miss out on Dart. A similar company GMAA used to be Hangar8 before merger, sp has fallen today, can't see any reason, I think Paul covered this under old name but can't find it now. Any views would be welcome.
Paul you absolutely gave a big thumbs up when it spiked down on the court claim case, which for me was almost an irrelevance being a one off. Core business fundamentally unchanged by this. Was not brave enough to up my holding though! For the 2015 y/e would expect eps about 25 so yes a pe of14.5 for 2016, well as I mentioned at the moment both macro and micro factors all going in their favour so operating profit north of 60 and eps 31 plus ,but heck what do I know ! The caa web site will tell you that they historically predict/insure to carry 1.2m passengers so if that moves .... Constraints are the amount of traffic and holidays you can sell in the north of England and can, will they move south,stanstead, Bristol, Cardiff ,Southampton ? Also founder/CEO holds about 40% of equity and is I believe 68 this year so clearly for him it's more then a job and this may constrain possible tie ups and M and A. You make an excellent point about current value and premium to market but in short to medium term growth prospects still look excellent. Completely agree your comments re momentum, and with that thought in mind will be assessing my horribly overweight position in dart over the next few weeks, thanks for your as ever thought provoking comments, in my business world they say " it's easier to review then to do" and you constantly " do it" by putting your view out there. Thanks
Thanks for the afren presentatiion link. At a quick glance, as others have said, it looks like the can has only been kicked down the road. Even post recapitilisation it will only just cover opex, capex and debt payments at current price of oil.
Sure if price of oil shoots back to over 100 then great but why take the gamble on Afren to take advantage of any price of oil upside.
Again echoing what others have already said elsewhere, i can see a repeat situation again in a years time.
Shaun
Paul appreciate your are really busy but fundamentally dart is a travel business not an "airline" that over simplifies the business. Plus they have the small but profitable distribution business, whose largest cost is fuel. So a sound business has the positive movements of fuel ( I accept they buy in dollars which isn't helping) and euros for the purchase of rooms and holidays, significantly helping all going the right way. Hedging flattens this years result but with increased sales and sensible future hedging your use of current numbers under players the business value, I think. Also macro factors, summer sun, more disposable income for UK employees, higher employment rates all move in favour of a developing market opportunity which in the north of England and Scotland they are a leading player to service. But hay what do I know I am just an accountant.! In case you hadn't guessed I am long!
Hi Tanglands,
Thanks for the comments. I held Dart a few years ago, and more recently bought at about 190p on the spike down on the profit warning, but like a fool didn't hold! Made a quick 20% or so, and moved on.
I appreciate everyone is feeling great, because the stock has shot up today, but surely it's now looking fully valued, whereas as I've pointed out in previous reports here, it's looked quite cheap in the past (PER typically 10 or less).
What EPS do you see as likely in future, and what PER are you happy to pay?
It operates in a very competitive sector, so I'm struggling to see why Dart should have a premium rating? Nice business, but probably the price is up with events now, in my view. BLASH as they say!
Regards, Paul.
P.S. please also note that I gave a strong thumbs up at 187p per share in my morning report to Dart (LON:DTG) when they warned on profits & the shares spiked down to 187p on 26 Jun 2014, so people who read that report & DTOR were firmly pointed towards the best recent buying opportunity!!
Ed and I like to discuss this conceptually! But it seems obvious to me that the buying opportunities on a share like Dart (LON:DTG) are when it spikes DOWN, so we can buy it cheap, as I suggested in the SCVR on Jun 2014 at 187p. Not theoretically, but actually, on the day. And actually on the intra-day spike down for the cheapest point you could have bought that share in the last year. Pretty good, I would say!
When to sell? Well how about when you've doubled your money in 9 months? That seems a pretty good time to bank the profits, as I said in the SCVR this week. I reckon if you decide to buy now, at double the price of 9 months ago, you're completely crackers! I thought it was all about buy low, and sell high! I don't look at the chart, at the peaks, and say, ooh I wish I'd bought there! I'd be certifiable! I want to buy at the lows on the chart. When everyone else is despondent, like when Dart (LON:DTG) put out a profit warning, not when people who like the share are celebrating that it has doubled. I want to be selling at that point! BLASH again.
OK, they don't all work out as well as this. But I reckon man has done a much better job here than machine!!!
Love the StockRanks, but astute readers of the SCVR would have done far better on DTG than following a mechanical strategy.
This is the BIG problem with momentum! It's fine as long as it continues. But it WON'T continue. So you need a strategy to get the hell out of over-valued stocks, which a momentum strategy will inevitably suck you into.
When ordinary stocks get to a PER of 20, and momentum says keep buying - you know what that is? It's a bubble! You know what happens when a bubble loses steam? A crash! I would say get into cash. Actually, it will probably be fine, if you're not geared, and you hold nice stocks on a sane valuation, then it should probably be alright.
People think they're terribly smart with momentum, until it suddenly collapses.
Asos on a PER of 80. Only a matter of time before it crashes.
Regards, Paul.
"Love the StockRanks, but astute readers of the SCVR would have done far better on DTG than following a mechanical strategy
This is the BIG problem with momentum! It's fine as long as it continues. But it WON'T continue. So you need a strategy to get the hell out of over-valued stocks, which a momentum strategy will inevitably suck you into"
As has been said on here before, only 1/6th of the StockRank score is based on price momentum so it is not accurate to call it a "momentum strategy". If a stock gets overvalued this will get factored into the StockRank so it DOES help in getting out of an overvalued stock.
Well I have a couple of issues with that statement:
1) Firstly as I indicated on the other thread a QVM approach using a price breakout would have got you in around 98p in late 2012 (without the downside risk of court cases etc which was the context of the price drop)
2) On the day of the downward price spike, you're assuming that:
a) punters can access the market at the time of the RNS. (I imagine most readers have day jobs which might not allow us to move quickly on price sensitive data)
b) punters can get the low of the day when the RNS is released.
Cheers
Phil
Hello Everyone. Does anyone have any thoughts on HALOSOURCE? I am following this stock at the moment and I think it might be promising. Ethical product in developed and 3rd world countries. Seems to be selling well through franchises but appears to be jam tomorrow rather than today. It has fallen significantly so am I looking at a dead cat? Thanks.
Yup, you called it correct PP.
Happy to admit I called this one wrong. Always was a "perceived value" punt from my PoV.
My reservations being it was Nigeria, the lack of an Operations update, and just how on earth could things have gone so wrong given the cash at bank ($235m) , the hedged production, and the assumption production would be rising(and not falling)
Operations update revealed all..no wonder they delayed it for so long.
Quite amazing that we have got to this point - BOD have been seriously negligent imo.
Production BELOW previous guidance @ 31,800bopd - What happend to ramp up?
And it took CAPEX spend of £769m to get even that!
(No ramp up in bopd produced explained as follows: Group production in 2014 was down 33% due to cost recovery at Ebok and the delays in achieving production ramp-up at Ebok and OML 26)
Revenue $0.9bn versus $1.644bn prior year. So our production not as "cheap" as people implied it seems. And Guidance for 2015 sees another $500m capex spend to secure FY15 Net production guidance of between 29 to 36 kbopd.
No mention of the Oil hedge being SOLD! Which is extremely price sensitive info imv.
"cash at bank of US$237 million (2013: US$390 million) which includes the realisation of US$80 million on oil price hedges sold in December 2014"
Plenty were under the impression that cash at bank was $237m and that the OIL hedge was still in place. So this is a MATERIAL difference that investors were not aware of.
So operationally the company was sunk - and it wasnt just a short term liquidity crunch that I envisaged, but something more worrying.
Icing on the cake -
$2bn impairment charge.Brutal. Bardas Rash basically an expensive hole in the ground.No doubt similar to Akri Bijeel in a month over at GKP. Ain Sifni, quiet there.
Refinancing - $200m interim refinancing to cover short term liabilities, to be replaced with a $300m Super Senior PPN note.
Debt-for-equity swap: 25% of the 2016 Notes, 2019 Notes and 2020 Notes will be converted into equity with the remaining existing Notes being reinstated and extended to 2019 and 2020 at an annual coupon of 9.1%
Extension of the Ebok Facility until 2019, alongside a re-profiling of the amortisation schedule under such facility...
The Recapitalisation will result in substantial dilution for existing shareholders. Following completion of the Recapitalisation and assuming that the equity offering is subscribed in full by existing shareholders only, existing shareholders will hold up to approximately 11% of the fully diluted share capital of the Company
Restructuring pretty clear. Current shareholders will get left with very little.
Following the restructure Afren will still be sitting on debt of c £1.25 billion......Coupled to the continuing weak POO environment (Stockbuilds reaching overflow levels with likely further weakness according to bloomberg article) and a piss poor operating update I'm calling time.
Took my medicine.Sold
One of life's lessons
"BOD have been seriously negligent imo"
That seems very generous of you.
Seems it would go some way beyond that from your above description.
Is that not in itself something of a contradiction in terms? :-)
Steve