Small Cap Value Report (21 Oct 2015) - CNCT, FOUR, COMS

Good morning!
Connect (LON:CNCT)
Share price: 168.5p
No. shares: 244.3m
Market cap: £411.6m
I am writing part of this report the previous evening, as there probably won't be time to write it up in the usual time. On 14 Oct 2015 here I wrote up my review of the results for y/e 31 Aug 2015 from Connect - a specialist distribution company (formerly Smiths News).
Whilst the business seems to be performing alright, I have concerns over its weak balance sheet, which are summarised as follows;
- NAV of only £9.2m
- Taking off intangibles of £174.8m reduces NTAV to minus £165.6m
- Current ratio of 0.71 seems weak
- Net debt of £153.4m is higher than I would like
- I suggested that an equity raise of c.£166m would be sensible, to restore NTAV to around nil.
Telecon with CFO, Nick Gresham - one of the company's advisers suggested that it might be useful for me to discuss my balance sheet concerns with Connect's CFO, and so we had a chat today by telephone.
In most situations (where it's a proper company as in this case, and not some blue sky, or overseas rubbish on AIM), I'm more than happy to engage with companies, and put their point of view across too, so that investors can make up your own minds. It's important to have a right to reply if a commentator is saying negative things about your company.
Here were the key points made by Connect's CFO to me today;
- Net liabilities were minus £60m at the time of the demerger from WH Smith, so the balance sheet has improved from what was inherited.
- Post-acquisition of Tuffnells, the business should generate strong free cashflow, such that it is expected to reduce net debt to c.£100m by 2018.
- A £55m equity fundraising was done as part of the financing package to acquire Tuffnells.
- Net debt to EBITDA is currently 2 times, well within the banking covenant of 2.75 times, so the CFO feels they have adequate headroom.
- "I am comfortable with both the supply, and the cost of bank debt"
- Pension deficit - is very small, compared with say Wincanton (LON:WIN)
- Freeholds - of c.£25m book value, and current market value is about the same, which provides some balance sheet strength.
- Total bank facilities are £250m, provided by a syndicate of 5 banks, so again plenty of headroom is available. Available until Nov 2018.
- Acquisitions - none in the pipeline short term, possibly more in future, if so likely to be smallish.
- If market conditions deteriorated, then Connect could reduce its dividends to prioritise reduction in bank debt/ strengthening its NTAV position.
- The company does not want to dilute existing shareholders with an equity fundraising, when it doesn't see a pressing need to do so. This is always an option for the future though, if circumstances warranted it.
My (revised) opinion - overall I was reassured by this conversation, and whilst I would prefer to see a stronger balance sheet at Connect, I accept that the current situation looks stable & sustainable for the time being. Maybe I am a bit too paranoid about balance sheets? Although I do feel that a strong balance sheet protects the downside for investors, if/when things go wrong.
On balance I would still prefer to see the company reduce its very generous dividend yield somewhat, and focus more on debt reduction & building balance sheet strength. However, after talking to the CFO, and his justifications for the current position, I feel a bit more relaxed about the issues we discussed. On reflection, me describing the high dividend yield as "reckless" was probably a bit over the top!
4imprint (LON:FOUR)
Share price: 1296p (down 2% today)
No. shares: 28.0m
Market cap: £362.9m
Trading update - this company is a "direct marketer of promotional products", and operates mainly in the USA.
Today it says;
The Group has continued to experience strong organic growth in the period since the announcement of its half year results on 29 July 2015, with the balance between new and existing customer orders consistent with previous periods. The Board expects percentage revenue growth in the high teens for the year as a whole, while delivering its objective of maintaining constant overall operating margin percentage.
This strikes me as a bit unclear. It's fine to give additional detail like this, but investors really just want a simple statement saying whether or not the company is going to meet market expectations for the year (on profits). No mention is made of that in today's statement. Omission usually means it's fine, because if they were trading below expectations, then they would have to say so, but it does introduce doubt into my mind (i.e. that they might be trading a little below expectations, but want to avoid saying so).
Revenue growth "in the high teens" is obviously good, although note that revenue growth in H1 was 20%, therefore it sounds as if H2 growth will be perhaps c.15%, which would give high teens for the year as a whole. So growth is slowing somewhat. However, that seems consistent with broker expectations, which I see are for turnover growth of 16.6% for this full year.
The operating margin was 6.4% last year, so on forecast turnover of $485m, that equates to $31m operating profit this year (remember this company switched to dollar reporting recently).
EDIT - I have subsequently confirmed that 3 brokers covering FOUR have all published notes today leaving their estimates for this year unchanged - i.e. this update is indeed consistent with market expectations.
Valuation - it's looking very fully valued now, especially as growth is slowing;
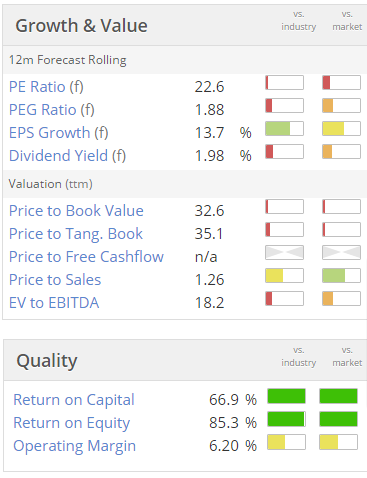
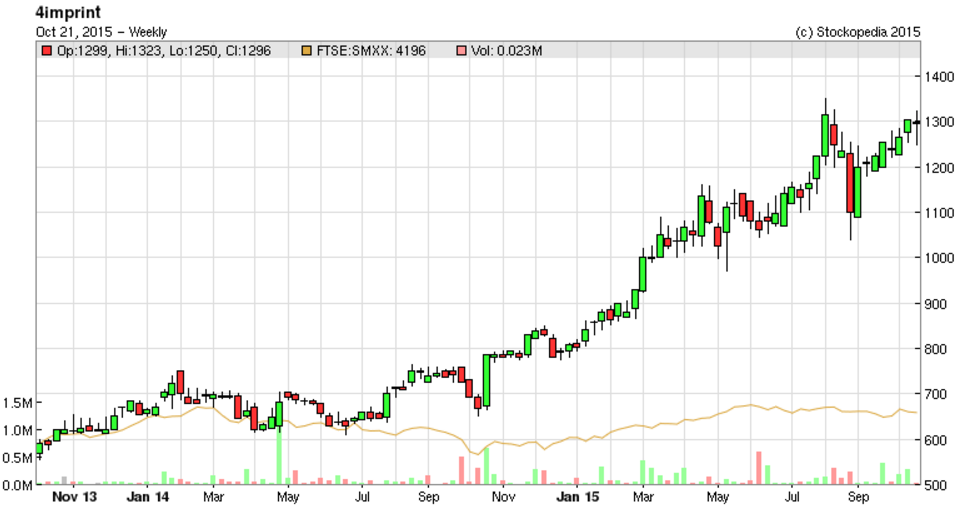
My opinion - this seems a very good company, and the shares have done really well, but personally I would be taking profits now if I held, given that growth is slowing, and the valuation is very full now, or even a bit over.
There again, it's looked pricey all the way up, so if you had worried too much about valuation then you'd have missed the big rise (as indeed I did!)
Coms (LON:COMS)
Share price: 1.03p (up 17.1% today)
No. shares: 1,389.5m
Market cap: £14.3m
Interim results to 31 Jul 2015 - I had a quick look at these figures earlier this morning, purely out of curiosity to see how close to going bust it was. However actually things look as if they are being turned around quite well.
It is around breakeven on continuing ops in H1 - not bad, considering all the disruption from changing management, doing an emergency fundraising, etc. An onerous lease of £30k per month (9 years remaining) has been exited, which is clearly good news.
The Directorspeak is positive.
Balance sheet - still quite weak, but not a disaster. I'd say they will need another top-up fundraising at some point.
My opinion - I've taken this share off my Bargepole List today, as it no longer looks to be in critical condition, and who knows, maybe a decent turnaround is underway?
It's not yet clear to me that the business is worth £14.3m, mind you. So more investigation would be needed to ascertain where the company is going, and whether it has a more viable business model second time around?
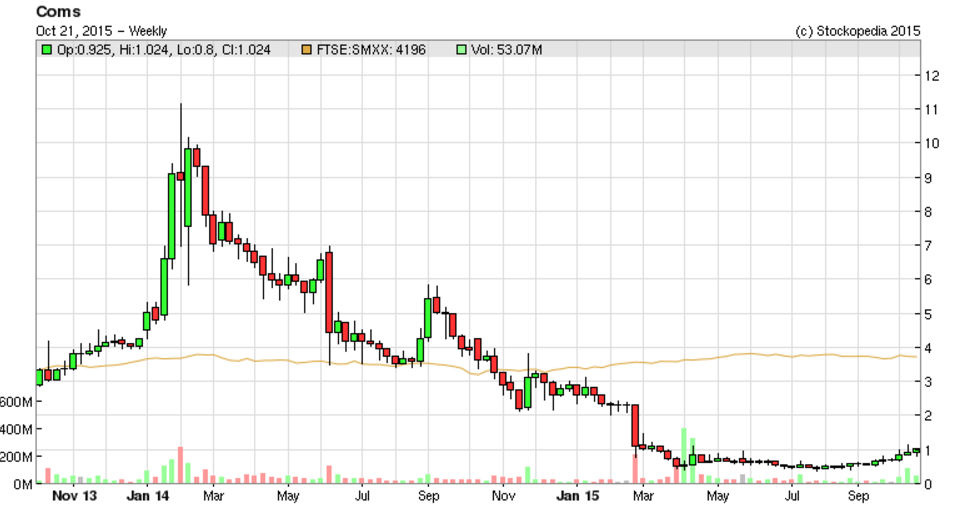
Clearly, as you can see from the 2-year chart below, a lot needs to be done to restore shareholder value. It's doubled from recent lows, on relief that the company isn't likely to go bust. However that doesn't on its own make it a good investment from here. More work is needed to research the new business plan I think.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

20 comments
Have there been any daily reports since this one ?don't seem to have seen any?
Not sure whether this is uk wide but in my area Amazon.com Inc (NSQ:AMZN) have stopped providing Collect+ as a delivery option and are using pass-my-parcel instead.
Given that Amazon.com Inc (NSQ:AMZN) have a stake (or at least did at somepoint) in Yodel who part own Collect+ with PayPoint (LON:PAY) this is a strong vote of confidence in the value of pass-my-parcel.
If this is a wider policy change for Amazon.com Inc (NSQ:AMZN) in the UK, long Connect (LON:CNCT) short PayPoint (LON:PAY) could be a good trade?
JTG said....
Maybe we should hold a contest for portfolios of 10 stocks to named and untouched for three years. (How about that for customer retention, Ed?!)
Not part of a contest but I have been showing my top ten holdings every Halloween for the last few years ( Performance can be scary !) and recording it ...
This posting gives you the stocks held and prices three years ago in 2012 and I am proud to say that all but Real Good Food have remained as major holdings all the way through to today....Halloween is almost here !
http://boards.fool.co.uk/halloween-top-ten-2013-12914838.aspx
LOQ is now Accesso (ACSO)
It is astonishing that those mainly small caps across ten stocks have outperformed the FTSE100 by a multiple of at least 30 and they are all on AIM which rather goes against those who say avoid AIM like the plague !
Careful stock selection backing quality management and in growth sectors will deliver excellent returns and most of these companies pay dividends too.....those can be added to total shareholder returns.
I am a long term small company investor and there is no guarantee that past performance of these companies can be continued into the future but I do think a three year hold can deliver very well indeed if you pick the right kind of company in the first place. You do need to act if things do not figure out in the way that you expected which is why RGD was sold half way through but still with excellent gains and in fairness it is higher now than my average selling price so certainly no problems in that 2012 list of 11 stocks.
David
Twitter @carmensfella
'Maybe I am a bit too paranoid about balance sheets? Although I do feel that a strong balance sheet protects the downside for investors, if/when things go wrong'.
If anyone ever reads this the above comment needs comment.
Paul's trademark is balance sheet analysis among other angles. Investors take it or leave it. A lot of the time I buy on profit warnings, for example when I am not holding the stock already.
It would be unwise, in my view, to relax vigilence over balance sheet analysis and pension deficits. No one else, to my knowledge, does this comprehensively in the small cap universe. It would be especially unwise to relax vigilence under pressure from the company analysed!
Yup, rather like Connect (LON:CNCT) trying to replace declining newspapers and magazines...
Or Glaxo or AstraZeneca (LON:AZN) replacing off-patent drugs, or any miner the output of a mature mine, or Vodafone (LON:VOD)
the value of its known services.
Growth stories that can afford a decent dividend seem few and far between, or they won't last three years. Having been a medium-tech manufacturer, and rather glad to be out of it, I see everything needing to be in a state of constant renewal anyway now. My investment horizon on individual stocks has definitely gone down. Maybe we should hold a contest for portfolios of 10 stocks to named and untouched for three years. (How about that for customer retention, Ed?!)
Thank you for the Connect piece, Paul. Much appreciated, as a holder of the last 18 months. I think the Tuffnells acquisition very important, and the possibilities of Pass My Parcel interesting. I am perhaps less interested now with the news of the Argos capabilities. So will look at HRG. But a having read earlier posts on DX Group, it's interesting to use the Compare Stocks tool, which implies DX is to be preferred to CNCT in nearly every aspect except momentum. Any comments, anyone?
The problem with DX (Group) (LON:DX.) is that it makes artificially high profits from its core document service to solicitors, etc.
That service is in structural decline, so I reckon the very high margins at something like 10% will, over time, in all probability drop considerably. So it's very difficult to value, as arguably it's a declining business, bolting on other things to try to mask that decline.
P.
I don't think the value of Pass-my-parcel should be underestimated. a) it capitalises on Connect's unique* relationship with newsagents, which the Connect delivery fleet is already visiting anyway; b) it is rolling out rapidly, as the latest results show. I was pleased to see that a "pass-my-parcel" sticker has appeared in the window of my local cornershop.
This network of many thousands of newsagents (albeit in a declining print media market) is a high barrier to entry for any potential competitor - and a big "convenience" USP for Connect**. I was also interested to learn at the meeting relating to the Tufnell's related rights issue that £10s of millions have been invested in IT systems to control their newsagent relationships/accounts in recent years. I am delighted to see Connect's management capitalising on those relationships & investment with the introduction of pass-my-parcel.
*strictly speaking, not unique, but a duopoly shared with John Menzies (LON:MNZS)
**My nearest Argos counter is about 3/4 a mile away from where I live. The cornershop is less than 100yds away.
Cheers,
Mark
I agree on Home Retail (LON:HOME).
£0.2b cash + £0.5b credit book leaves EV of c£0.5b.
Should be able to generate £0.2b cash annually once transformation capex winds down and normalising working capital flows.
Obviously have a bit of a pension deficit and like all retailers negative NWC but still very cheap for the UK's second largest internet retailer.
Anecdotally I was intrigued on a recent journey through Cannon Street station to see that there was a small Argos pick up unit within the tube station. The folks there outlined how if you order online by 1pm you can pick up your goods there by 4pm the same day. A remarkable service for all those stuck in an office all day unable to be home to collect a package from Amazon or who do not want to wait 3-5 days to make use of Amazon free delivery, or indeed those buying items whose values aren't high enough to qualify for free delivery. Apparently Argos have half a dozen such pick up units around central London being serviced by two large warehouses.
I thought this all very impressive however they are only servicing about 120 people a day presently at that particualr unit. It was enough to make me realise there is still alot of scope for innovation when it comes to deliveries and Argos have plainly realised that. I shall be taking another look at Home as a result.
Hi Paul, I know blue sky companies aren't really your thing so much these days, but I know you've commented on Advanced Oncotherapy (AVO) before and today's announcement seems pretty good to me. With the Chinese showing such interest in their LIGHT system the opportunity is huge as along they keep hitting their prototype milestones and can cope with the demand. In fact I've topped up as I think the market has under reacted IMO.
Cheers, James
Ref Connect
"Net debt to EBITDA is currently 2 times, well within the banking covenant of 2.75 times, so the CFO feels they have adequate headroom."
Strewth thats a ballsy statement to make, i know nothing about the business but it really annoys me when bods in charge of a company don't have a contingency plan for a scenario where profits might drop 30%. Ok EBITDA probably excludes so much that it may be a fairly easy metric to meat but nonetheless unless my maths are wrong i for one would not want to rely on the fact that you may be royally screwed if the profits (albeit EBITDA) dropped 30% due to circumstances beyond their control. Having said all of that if the EBITDA covenent is trending in the right direction naturally with higher future profits and lower future debt this would provide extra wriggle room on top.
In the past i have been a fan of gearing where a company is going places but the last credit crunch taught me a thing or two as to how stupid and naive i was to think that everything in the future would be nice and Rosy and that financial institutions would want to aid their customers
PS Good stuff Paul ensuring we have the full information from the horses mouth as most of the times us PI's don't get this unless someone takes the time to ask and update us.
Paul, Home Retail (LON:HOME) is off 14% today on its interim report. Reasonable? Or an overreaction?
Hi FREng,
Re Home Retail (LON:HOME) - I'm surprised the shares have dropped 17% (to 124p at the time of writing), on what was really a very mild profit warning - they said results for this year will be slightly below the bottom end of analyst expectations.
This share isn't really about current profits. The opportunity I think, is that the shares could considerably re-rate when they have the same-day delivery for £3.95 service working nationally. That's a game-changer in my view. So I expected some up-front costs to set that up, but apparently the market didn't. Ho hum.
Personally, I'll be buying more at this level, as it looks like the sort of mild profit warning that will soon be overlooked once people refocus on the upside potential from same day delivery, not just for their own products of course, but for third parties too.
The other nice thing with HOME is its fantastic balance sheet, where the consumer debt it extends is owned outright by the company, plus it has net cash. Those two put together are about half the market cap! So really copper-bottomed.
On the negative side, margins are wafer thin, and there's no guarantee same day delivery will be unique for long, others may replicate.
Regards, Paul.
The balance sheet seems indeed pretty strong, but I don't understand why you say that outright ownership of consumer debt is a positive in that regard. That makes them exposed to a recession where the consumer default rate would go up and they would have to write off some of that asset. Given the relatively modest size compared to book value (700m vs 2b), it seems safe, but wouldn't they be even more secure if they outsourced that to a financial service provider who takes the downside risk?
This risk is also correlated with their non-finance revenue (in a recession retail sales go down at the same time as consumer credit defaults go up).
Interesting, Home is one of the few shares with a clear strategic play in the market. I checked it out and the price looked too high but will put back on the table now, thanks.
Hi Paul,
Many thanks for taking the time and trouble to speak with the Connect (LON:CNCT) CFO and reporting what he said in a fair and unbiased way. It is really useful. I previously held shares in the company and had it on my watchlist again but having read both sides I have decided, on balance, that the risks are greater than the potential gains.
Steve
Hi Paul -
Nevertheless the company's balance sheet is pretty stretched and it is sailing close to its limits. It will not require much of a market correction to force them to take serious corrective actions. Additionally the company just cannot entertain further acquisitions with this sort of balance sheet.
From an investment viewpoint, the divi is great but the risk of a banana skin skid is greater IMHO.
An excellent précis thank you Paul & (as a previous holder of £CNCT) it is good to get the FD's perspective
Hi Paul
Many thanks for the update , very useful background and makes the share a credible choice for risk tolerant income seekers.
Cheers