Small Cap Value Report (Thu 23 Nov 2017) - MTC, NET, TCM, WINE, MNZS

Good morning, it's Paul here.
I updated yesterday's article in the evening with new sections. Here is the link.
There is very limited time available today, but I'll do what I can.
Mothercare (LON:MTC)
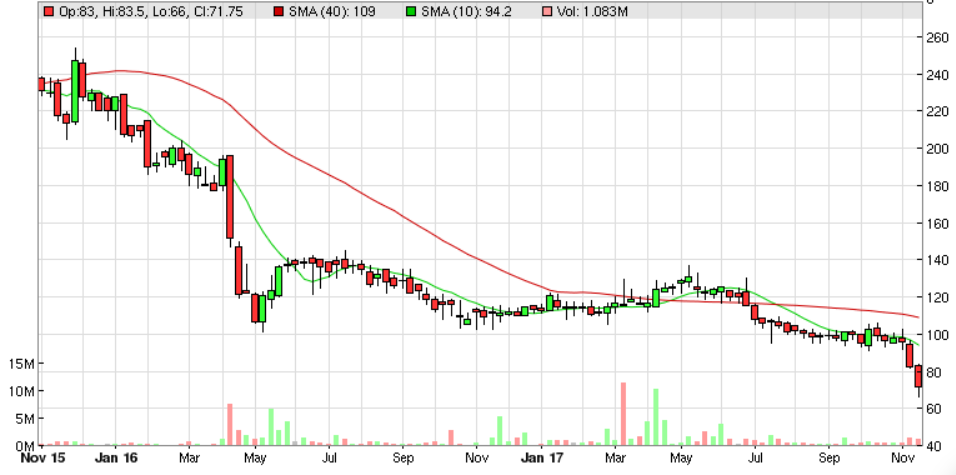
Share price: 70p (down 16.2% today)
No. shares: 170.9m
Market cap: £119.6m
Half year results - for the 28 weeks to 7 Oct 2017.
The company calls itself;
the leading global retailer for parents and young children
I don't like the PR spin at the start of the announcement, which trumpets;
Continued transformation of the brand, converting into positive UK like-for-likes set against a challenging consumer backdrop
That's just meaningless, as it tries to sound positive, when the figures are actually poor. I'd rather not have a heading, if it's just an attempt to gloss over poor results. People aren't fooled anyway, as you can see from the 16% drop in share price, so what's the point?
UK LFL sales are indeed positive, at +2.5%, but that doesn't seem to have been enough to absorb cost pressures. The adjusted UK loss was -£9.6m, a deterioration from -£8.8m in H1 of last year.
International (the only decent part of the business, in terms of profitability), saw a sharp fall in LFL sales, of -7.7% in local currency. That's not good at all. Adjusted profit fell from £20.8m in H1 last year, to £14.9m in H1 this year.
Overall, the group couldn't even reach breakeven on an adjusted (i.e. favourable method of calculation) basis, with an adjusted loss of -£0.7m. There were £16.1m of adjustments (i.e. ignored costs) in reaching that figure. The list of things they have classified as adjustments look very aggressive to me - many are just normal costs of running a business, in my opinion (e.g. restructuring warehouses & retail sites, refinancing costs, etc). So in reality, the business is loss-making.
Recent trading - the UK market is softening, which to be fair, lots of retailers are saying at the moment, and this is also confirmed by poor recent economic statistics;
"Towards the end of the reporting period, and in subsequent weeks, we have seen a softening in the UK market with lower footfall and spend which is consistent with recent industry reports. Not-withstanding this uncertain consumer backdrop, the Mothercare brand, whilst not immune, is in a stronger position with a much-improved product and service offer and a more robust business model.
Pension deficit - is falling, but still quite big at £68.9m. The company paid £7.1m into the pension fund in H1, which is a huge drag on a company struggling to breakeven. Younger competitors don't have this expensive historical baggage.
Net debt - has risen sharply, at £37.6m
Balance sheet - overall this looks weak. NTAV is only £4.0m.
Seasonality - looking at last year's figures, there seems to be an H2 weighting to profits, so a small adjusted full year profit looks the most likely outcome this year.
My opinion - this company looks to be in a rather precarious position.
With negligible net tangible assets, I wouldn't rule out the need for another equity fundraising. The trouble is, the company has been promising a turnaround for years now, and it never seems to get anywhere. Improvements made just seem to offset deterioration in other things.
The fundamental problem facing this company is online competition, and increasing costs - same as for any retailer selling products which can be bought more easily online.
If it didn't exist, would you invent Mothercare? Probably not. So for me, the shares are definitely to be avoided - unless/until the company can demonstrate genuine progress in improving profitability. That's difficult to imagine, with the various headwinds being faced by many retailers at the moment.
Note that the Stockopedia computers are also sceptical - rating it as a "value trap", and a low StockRank of 32. It reassures me when my analysis matches the emotionless Stockopedia algorithms.
Netcall (LON:NET)
Share price: 43.5p (up 6.1% today)
No. shares: 142.7m
Market cap: £62.1m
AGM statement (trading update)
Netcall plc (AIM: NET), a leading customer engagement software provider...
The company has a 30 Jun year end, so this update is from Jul 2017 to date.
Things seem to be going well;
"The Group has experienced robust trading in the first few months of the financial year driven by growing demand for the Group's customer engagement software platform, Liberty and recently acquired MatsSoft.
I've looked back at previous announcements, and Netcall used its entire cash pile to buy MatsSoft, so it's a very important acquisition. Based on the RNS about the acquisition, it seems that MatsSoft is essentially loss-making (as it only produced a £0.1m adj EBITDA for calendar 2016), which makes me wonder why Netcall was prepared to pay £11.1m initial cash consideration for it. They say the acquisition is going well;
"The integration of MatsSoft is progressing well and the Group has already won its first contract cross selling MatsSoft's low-code software platform into an existing Netcall customer. In addition MatsSoft continues to win new customers including international sales.
Outlook - I'm not sure the balance sheet is robust any more, following the acquisition, but I'll be able to check that when the next results come out;
"The sales pipeline is healthy and this, combined with a high level of revenue visibility, a robust balance sheet and an expanded market opportunity, leaves the Board confident in the ongoing success of the business."
My opinion - this one looks potentially interesting. Looking at the historic track record, organic growth seemed to have fizzled out, so a big acquisition was made.
Note that the bumper dividends will now stop, as the company has used the cash to buy MatsSoft instead.
If you understand the sector, then this one might be worthy of further research. I don't feel able to assess whether the acquisition made sense or not, so will move on.
Telit Communications (LON:TCM)
Share price: 162.5p (down 14.0% today)
No. shares: 130.7m
Market cap: £212.4m
(at the time of writing, I hold a short position in this share)
Board changes & trading update (profit warning)
This is an Israel-based maker of internet of things modules.
It's surprising that this share has only fallen 14% today, given quite a nasty profit warning;
Early indications are that pressure on gross profit margins stemming from the transition from 2G and CDMA products (mature technologies with higher gross profit margins) toward LTE products (newer technologies with lower margins at this stage) has been greater than expected.
As a result, the Board expects adjusted EBITDA for the year to be materially below previous guidance. Revenues and adjusted EBITDA for the second half will, as usual, be greater than for the first.
Since the year end is quite near, 31 Dec, this implies quite a sharp reduction in performance recently. The company is extremely aggressive in capitalising costs into intangible assets, to the point that its EBITDA numbers are completely meaningless as a measure of profitability. I've covered that in depth in previous reports here.
The company is implementing a cost reduction plan, more details to come;
The Board remains committed to delivering a significant rationalisation of the Group's product lines and a reduction in its cost base, the benefits of which will be achieved in the coming financial year to 31 December 2018 and following years.
This article from me covers the 2015 results. This explains my main problem with the company's accounts, which is still very relevant today.
Since then we've also had the CEO exposed as a fugitive from US law, who resigned in disgrace. A further issue was that the CFO dumped his shares just before announcing to the market that the company was in breach of its banking covenants! (you couldn't make it up). Today the company reassures us that this is absolutely fine;
"We are aware of the concerns raised regarding share trading undertaken by Yosi Fait in July 2017. We have absolute confidence in his integrity and believe, having examined the share trading with the assistance of external legal advice, on this basis that it was lawful.
So presumably "on this basis" means that on another basis it wasn't lawful? I imagine a court & a jury might take a dim view of insider dealing whilst clearly in possession of price sensitive negative information.
Anyway, this share seems to have a coating of teflon, as no matter how many red flags emerge, buyers still seem undeterred.
Director changes - part of the reason for a muted share price fall today could be because a heavyweight new Chairman has been recruited - Richard Kilsby. There are other board changes.
My opinion - I'm happy to remain short here. The profit warning today reinforces my view that this just isn't a very good company, in terms of its inability to make genuine profits. Maybe the restructuring will change that, who knows? Falling gross margins suggests that it doesn't have much pricing power.
Quick comments;
Majestic Wine (LON:WINE)
Interim results today look interesting. Adjusted profit has gone from breakeven in H1 last year, to £6.8m profit this year - an impressive turnaround. The main factor is Naked Wines moving from a loss to a profit. This seems to have been achieved by increased sales & margins, combined with a big reduction in marketing spend. Naked Wines actually made slightly more profit than the core retail business. There's an in line with expectations full year update.
I haven't got time to go into more detail, but just wanted to flag it to readers as worth a closer look.
John Menzies (LON:MNZS)
An in line update today;
The Group has continued to trade well since the half year and the Board is confident of meeting its full year expectations.
Outlook positive;
Commercially the pipeline of opportunities is strong and we look forward to 2018 with confidence.
My opinion - I reviewed its last interim results here. For me, the very low operating margin, and its horrible balance sheet, rule this one out. However, trading does seem to be going well, so my worries may not be pertinent right now.
I have to leave it there, as am off to Carmensfella's charity lunch.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

35 comments
No opinion on Netcall (LON:NET) but MatsSoft, the company they're buying, has a history of Companies House filings that would worry me if I were buying them. Start here: https://beta.companieshouse.go...
Multiple changes of accounting period. Having to re-file 5 years of Annual Returns - presumably due to errors. On Aug 4th 2017 notifying they'd allotted shares 18 years earlier. In 2013 being threatened with compulsory striking off, presumably for failing to file an annual return. It does not look like it has been run well. Most of the directors changed in August. Hopefully they will sort MatsSoft out.
Just posted a Creightons (LON:CRL) overview, with Pippa Clark Pippa Clark, Global Marketing Director and Paul Foster, Group Finance & Commercial Director talking about H1, and what they're up to.
http://www.piworld.co.uk/2017/11/23/creightons-crl-interim-results-interview-november-2017/
c. 7 mins
H1 highlights, Pippa Clark - 00:21
Financial performance, Paul Foster – 01:13
Managing growth, Paul Foster – 02:33
Future development, Pippa Clark – 04:10
Export growth – 05:38
Hi Paul,
You highly recommended a book on investment on your blog in the last three months or so. Please could you remind me what the title was. I'm sorry I've looked but can't find it, it might have been in the comment section.
Thanks,
Peter
Peter, the book is by Mark Minervini and is called "Trade like a stock market wizard".
Francis
Thanks Francis
He has a new book out now as well called "Think & Trade Like a Champion: The Secrets, Rules & Blunt Truths of a Stock Market Wizard"
Difficult to buy in UK, seems to be only available on kindle.
"Think & Trade Like a Champion: The Secrets, Rules & Blunt Truths of a Stock Market Wizard" is now available in the UK on a site beginning with A and ending with Z.
Thanks but as I said only as a kindle version. I don't have kindle even if I did I would prefer a book. Suppose I will have to order from the US, not sure about postage.Why this book is not available outside the US, several others have raise this on twitter without a response.
Hi Herbie
I ordered from the US only took about 5 days and cost about £28 inc postage. I sold hardcover on ebay and purchased kindle version when it was released as i prefer e books. Highly recommended though
Was previously long Telit Communications (LON:TCM) but sold before the major tumble. While the technology is compelling, this company is far too accident prone to be credible irrespective of technical capability. The IoT space is enormous and many faceted, like everything in the hype cycle it has a maturity roadmap, Garter still positions much of it at the peak of inflated expectations. When I think we talked about the internet of things back in 2001 as part of the RFID "revolution" then I tend to agree on maturity timecycles.
I too was surprised by the relatively small drop today : Telit Communications (LON:TCM) is ninth most shorted share in the UK atm (over 10% net short) and has been Top 10 for a while...not an enviable position. Looks like net shorts are increasing not decreasing so the most probable direction would seem downward for now. The price action is screaming sell too . 100p seems more likely than 200p in the next while unless some major good news appears
I know what you mean about the Gartner hype cycle and I agree that IOT is in the hype cycle.
But Gartner also say that when an idea comes out of the hype cycle it can either fade away to nothing or re-gather momentum and at least partially live up to the original hype. For example online shopping is still gaining momentum years after the hype cycle and years after it became obvious that it would grow to a global industry.
At 150p tcm is on a PSR of less than 1 so if there really are bidders out there it shouldn't go much lower...... famous last words.......
Majestic; good to see that inventory has gone up in value and intangibles (while large) have gone down roughly 10%.
The strategic decision to invest in the USA should make people nervous. How many British CEOs have left their sensitive parts hanging on American fences?
Mothercare should be avoided, no moat, no real focus on maximising customer loyalty from its core customer base.
How did it miss the opportunity for developing a mumsnet?
I had my Telit Communications (LON:TCM) short called-in last week unfortunately. I assume the owner wanted to sell them.
Hello Dangersimpson, BlueFrew, Paul,
I bought TCM in April 16 and I still hold now.
I hear what you say about the accounting red flags and trustworthyness of the directors but I think there is another side to tcm that doesn't get mentioned much on Stockopedia.
I would make the following points :-
1) Most people agree that iot will be a vast market over the next 20 years
2) Most people acknowledge that TCM is a world leader in IOT. They have partnered with SAP, Cisco and countless others much larger than them. When these partnerships were announced it wasn't just tcm that trumpetted them, these massive global companies put up spokesmen to endorse tcm's products and technology. tcm also has world leading clients e.g. John Deere, Tesla
3) Contrary to what has been said here before, this world leading business has been skillfully assembled over a number of years with very few diluting share issues. Debt has also been at manageable levels until this year. Although tcm breached covenants the banks renegotiated willingly and tcm met it's covenants at 30th September. Frankly, I don't really care what tcm's ebitda or profit is, as long as revenue grows and debt stays stable
4) If I look around me it is apparent to me that iot is slow to take off so it's not surprising that tcms growth has glitched (with requisite increase in inventory, working capital etc). But few doubt that long term iot will be a massive market. According to tcm it's iot software platform is fairly unique and world leading. This should strengthen margins in years to come and could conceivably develop a quasi-monopoly position
5) Regarding the trustworthiness of the directors I do think that is a serious problem and a reason to sell. However I also think some of what has been written is slightly sanctimonious and irrelevant. On the face of it Oozi Cats's issues seem trivial to me and nothing whatsoever to do with tcm (don't get me wrong, I would never do the things of which he is accused but I know people that have done similar things and I conjecture most of us who were around in the early 90s property boom do). Yosi Fait's share sale is concerning, however Richard Kilsby seems to have a lot of experience and has unequivocally backed him today. Tcm has had ample opportunity to dump Yosi Fait at any point in the last 3 months but it hasn't, so I think it's unlikely that any further skeletons will emerge in the accounts or Fait's probity. Both Fait and Cats seem talented, credible and trustworthy in the presentations I have listened to. There are plenty of companies whose CEOs I wouldn't trust but that does not make them bad investments!
6) It will be interesting to see if the bid rumours come to anything. Part of me wants that to happen because it will vindicate my analysis above, but part of me doesn't because if tcm can regain it's poise, the long term opportunity should be huge. I think the possibility of a bid is one reason the SP won't stay down
As Paul has said it really is a fascinating and polarising share but that's how I see it - weak hold. Once this has all blown over (hopefully by the finals in March?), we are going to be left with a fast growing world leading business.
Hi Paul,
Many thanks.
Has anyone heard anything about Sportech which seems to have dropped out of bed on no news today?
"The 29.0 pence per share distribution follows the gaming firm's sale of its Football Pools business for GBP83.0 million in June."
It's ex-dividend day for this large cashoff to Investors.
Thanks James totally missed that.
Burnley football fan here. Regards to Clarke Carlisle at your lunch today. He was a fantastic player for our club.
Hi Hollingrove,
Burnley football fan here. Regards to Clarke Carlisle at your lunch today. He was a fantastic player for our club.
Great stuff! I shall mention your comment to Clarke today!
Regards, Paul.
In case anyone isn't familiar with the red flags with Telit Communications (LON:TCM):
1. Former CEO wanted for fraud in the US:
https://www.investegate.co.uk/telit-communications--tcm-/rns/resignation-of-ceo-and-board-to-be-reinforced/201708140700058792N/
2. CFO now CEO sold shares while bank covenant breach unreported to market.
https://www.investegate.co.uk/telit-communications--tcm-/rns/director-s-dealing/201707041525021035K/
https://www.investegate.co.uk/telit-communications--tcm-/rns/interim-results/201708070700042176N/
3. Increasing Days Sales Receivables
4. Significant difference between PAT & FCF
5. Significant Capitilised Development Costs
6. Continuous stream of acquisitions
7. Banking covenants breached 56 days after raising $39m in fresh equity.
https://www.investegate.co.uk/telit-communications--tcm-/rns/placing-of-new-shares-raising-gbp-39-million/201705050700082619E/
https://www.investegate.co.uk/telit-communications--tcm-/rns/interim-results/201708070700042176N/
8 Low tax rate
9. Increasing days sales inventory
10. Some distributors listed on the Telit Communications (LON:TCM) website appear to be very small businesses or list out of date components.
https://www.shareprophets.com/views/30925/telit-bombshell-part-2-its-distributors-are-oft-on-a-par-with-those-of-globo
I wrote about why some of these things are red flags here:
https://www.stockopedia.com/content/red-flag-pink-flag-240123/?comment=8#8
Good luck at your charity event, hope you raise lots of ££! Thanks as ever for all the insights here, best read out there!
As there is little going on today I will mention that the FT100 demotion/promotion recalculation takes place next week. Any FT250 stock which would be in the top 90 of the FT100 by market cap gets automatic elevation and any 100 constituent that falls to 110 or below is relegated.
The one stock I am very interested in in this regard and have purchased is DS Smith (LON:SMDS) which is in the exciting growth industry of packaging, in particular cardboard boxes! Boring I hear you say? Well just think what everything sent by Amazon arrives in. I think this is away to play the growth in online trading without the tech risk.
DS Smith (LON:SMDS) is also a sustainable company with a virtually nil carbon footprint (all it's cardboard is made from recycled material) which is very important to it's customers in reducing their carbon footprints.
DS Smith (LON:SMDS) is in around 80th place by market cap and barring a major fall in it's share price in the next few days is nailed on for promotion to the premier league which means all the tracker funds/ETF's have to buy lots of stock.
DYOR but I will let you decide if these figures are "boring"-
Year End 30th Apr 2012 2013 2014 2015 2016 2017 2018E 2019E CAGR / Avg
Revenue £m........ 1,969 3,669 4,035 3,820 4,066 4,781 5,509 5,930.... +19.4%
Net Profit £m 75.3 74.0 140 156 167 209 318 368.6 +22.7%
EPS Reported p 1.15 7.19 15.2 16.4 17.5 22.0 +80.3%
EPS Normalised p 12.9 13.5 16.8 20.5 21.7 25.7 33.1 36.7 +14.8%
EPS Growth % +49.4 +5.2 +24.4 +22.1 +5.7 +18.2 +29.0 +10.9
PE Ratio x 20.9 16.2 14.6
Interesting Company £DS Smith, but they have generated quite a lot of growth by acquisition, and have had a recent tail wind of positive currency movements. Looks like they have good organic growth beneath the acquisition uplifts, and good/excellent cash conversion. So quite a few positives. Divi circa 3%
Could be a good 'boring' bellweather stock to have in the portfolio.
I made about 20% on SMDS a year or two ago... and they have risen a lot since then (drat). Personally I feel the price is well up with events - strip out the effects of currency-assistance and turnover, profit, and eps are all up only 6-7%; ROACE and return on sales are also down.
You may indeed be correct that the price will get an uplift from inclusion in the FTSE, and they also have a good record overall, but I prefer to buy on fundamentals that I am happy with, including good organic growth that is not excessively currency-flattered.
I'm no expert but I think most trackers track broader indices than the ftse 100 so the bounce from that source may not be so great.
I'm surprised that Telit Communications (LON:TCM) has fallen so little today, having recovered unusually quickly from the fall in August. I wish I understood why investors still like the company and trust its management.
Morning Team!
I'm on a very tight schedule this morning, as I have Carmensfella's charity lunch to get to, which starts at noon, on a Thames riverboat. So the fewer requests today, the better!!! I'll rattle off as much as I can though.
Best wishes, Paul.
Cloudcall (LON:CALL) have a new platform out, having previously built bespoke solutions for each CRM partner. This should increase efficiencies, up 2.4%. Paul holds as do I.
In resources news (sorry) Rainbow Rare Earths (LON:RBW) minerals have discovered lots more of the stuff underground with an aerial magnetic survey. One of the reasons I bought in was because the stuff was pretty much lying on top of the ground so less harmful to mine so am now conflicted - first production confirmed for end of this year though. I hold.
Directa Plus (LON:DCTA) Graphene comapny based in Italy have a new product Ecopave which can apparently increase the life of asphalt from 6-7 years to 12-14. Concerns abour Director options etc though have kept me out of this one.
Morning Paul!
If you find the time I would appreciate your comment on the following...
Netcall – 41p – £61m – PER 18.9 (pre-open)
AGM Statement – “The Group has experienced robust trading in the first few months of the financial year”. A Bullish statement but nothing regarding in-line/above/exceed/ahead of – That’s a pity, maybe those attending the meeting will ask!
Doesn’t look too bad - Operating Margin and ROCE are decent and there’s Net Cash (about 20% of Mkt Cap). I would need to await results for actual numbers to form an investment decision of some sort. I guess the price action after the meeting might help, assuming the right questions are asked.
CMC Markets – 166.75p – £478.3m – PER 13.1 (pre-open)
Interim Results For The 6 Months To End September 2017 – Revenue up 19% (£89.6m) and PBT up 58% (£29.8m) on high value client business. H2 trades in-line although there are still concerns regarding regulatory uncertainty. This comment is worthy of a thought “the Group considers a greater level of regulation could give it a competitive advantage as some smaller, less established players may find it more challenging to meet the new requirements”.
Yielding 5% (reasonably well covered) or so if you wish to accept the potential regulatory impact – This looks decent value here.
Thanks in advance as always.
Maybe Liontrust Asset Management (LON:LIO) who published their half yearly report today? I don't think they've been covered here before but fund managers Miton (LON:MGR) has a bit so maybe Liontrust's an option
My morning smallcap tweet:
Mountfield (LON:MOGP), Telit Communications (LON:TCM), Trader Media East (LON:TME)
Mountfield Group (MOGP) H1 trading. Net profit likely to exceed H1 and H2 2016. It won a number of contracts in H2 which are expected to be completed in 2018 so it will enter 2018 on a stronger basis than 2017. In line? Don't say. No f/c in mkt.
Telit Communications (TCM) warns FY adj EBITDA materially below previous guidance. Richard Kilsby (ex chmn of 88*). confirmed as chmn. Yosi Fait made permanent CEO. ""We are aware of the concerns raised regarding share trading undertaken by Yosi Fait in July 2017. We have absolute confidence in his integrity and believe, having examined the share trading with the assistance of external legal advice, on this basis that it was lawful."
Trader Media East (TME) Indirect subsidiary Pronto Media Holding (PMH) will close its digital operations. "As of 30.09.2017, TME has 5,8M-USD total consolidated revenue, with a net consolidated loss of 19.6M-USD, of which the major part of TME's losses occurred due the operations of PMH."
Telit Communications (LON:TCM)
"We are aware of the concerns raised regarding share trading undertaken by Yosi Fait in July 2017. We have absolute confidence in his integrity and believe, having examined the share trading with the assistance of external legal advice, on this basis that it was lawful."
Outrageous statement. When the CFO becomes aware (if he wasn't he was incompetent) that the company is about to breach it's banking covenants what would you expect the CFO to do? (a) Inform the market in a timely manner. (b) Tip out all of your shares at the highest price you can get for them before anybody is aware of the imminent breach?
Lawyers say a lot of things, especially if you pay them enough money. Perhaps with Robert Terry and Costis from Globo still free men, anything really does go. But is this really behaviour that is acceptable from an officer of a public listed company?
(Short Telit Communications (LON:TCM) )
Seems pretty quiet in small cap land this morning. An item of note is an agreed all cash bid for Servelec (LON:SERV) a specialist control management software company in the health, O&G and utilities sector backed by PE firm Montagu. Priced at 313.1p, about a 20% premium to last night's closing price.
https://www.investegate.co.uk/scarlet-bidco-ltd/rns/recommended-cash-offer-for-servelec-group-plc/201711230700062991X/
Reasonable exit for backers of 2013 IPO. Don't expect a competing bid but you never know. I hold and will most likely accept the offer.
Gus.