Small Cap Value Report (Tue 30 May 2017) - FXI, KNOS, BLTG, FJET

Good morning, it's Paul here.
I was looking into the horrible case of Fusionex International (LON:FXI) over the weekend, after a friend flagged it to me. It joins the long list of overseas companies which listed on AIM, and ended up being disastrous for UK shareholders.
I cannot stress enough how investors can protect ourselves by having a default setting whereby we decline to invest in overseas companies on AIM. The reason being simple - because many or even most of them end up being disastrous investments. Exceptions can be made sometimes, particularly where the country risk is lower (e.g. USA, or W.European countries), but I'll cover that in more detail at the end of this article.
As with Globo, and the Chinese AIM frauds, the warning signs were not difficult to spot - they were obvious. As I researched Fusionex over the weekend, the red flags were blatantly obvious. So people who get caught on this type of disaster stock really need to drastically improve their stock selection procedure, whilst they've still got some money left.
We all lose money on some shares, it's a normal part of equity investing. However, returns greatly improve if you have a process which weeds out the obvious wrong 'uns before they blow up. One of my key aims here is to help investors focus on better quality stocks, and avoid the junk. Although in a roaring bull market like this, plenty of junk stocks are doing very well (for now) - so there are opportunities for shrewd traders, nipping in & out of junk stocks for a quick gain. Getting out before the music stops is the tricky bit!
Anyway, on to today's results & trading updates.
Kainos (LON:KNOS)
Share price: 229.25p (down 4.5% today)
No. shares: 118.0m
Market cap: £270.5m
Preliminary results - for the year ended 31 Mar 2017.
This company (HQ in Belfast) describes itself as;
...a leading UK-based provider of digital services and platforms
Whatever that means? Checking back on my previous notes, it seems to be an IT company that specialises in UK public sector work. This is quite topical, given recent hacking & blackmail on the NHS (and other) computer systems. It's achieved superb growth in the past, as you can see from the Stockopedia historical graphs;
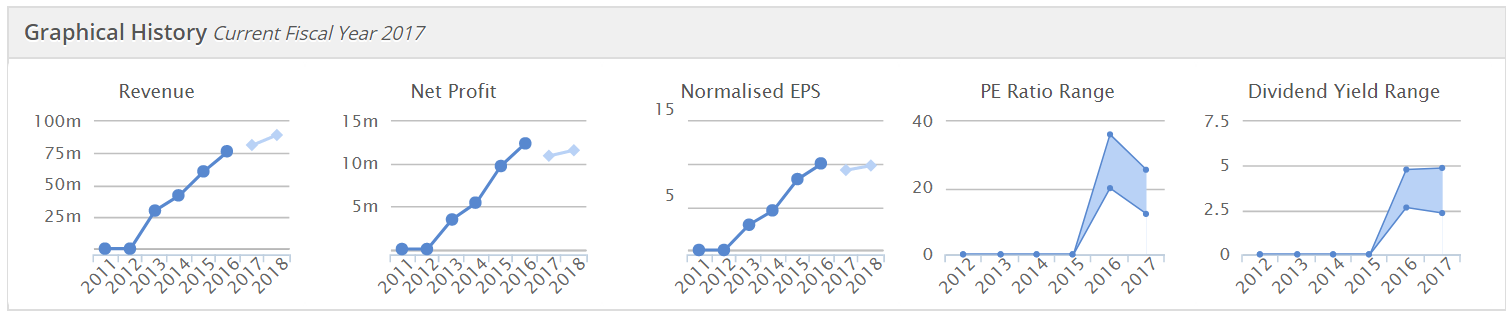
As usual, we can glean an awful lot from these simple graphs.
Graphs 1,2 & 3 - strong historical growth, but note that forecasts (the lighter blue blobs) are suggesting a slowdown in revenue growth. Profitability looks to have peaked - and is even forecast to fall slightly. So has the company gone ex-growth? It looks like that to me.
Graphs 4 & 5 - note that the very high PER is coming down (understandably, given growth fizzling out), and that divis became more meaningful from 2015. The company listed on the main market in Jul 2015.
Turning to the results for y/e 31 Mar 2017, I'm surprised that the share price hasn't fallen more today. The numbers are OK, but the growth seems to have fizzled out, as you can see from the highlights section;
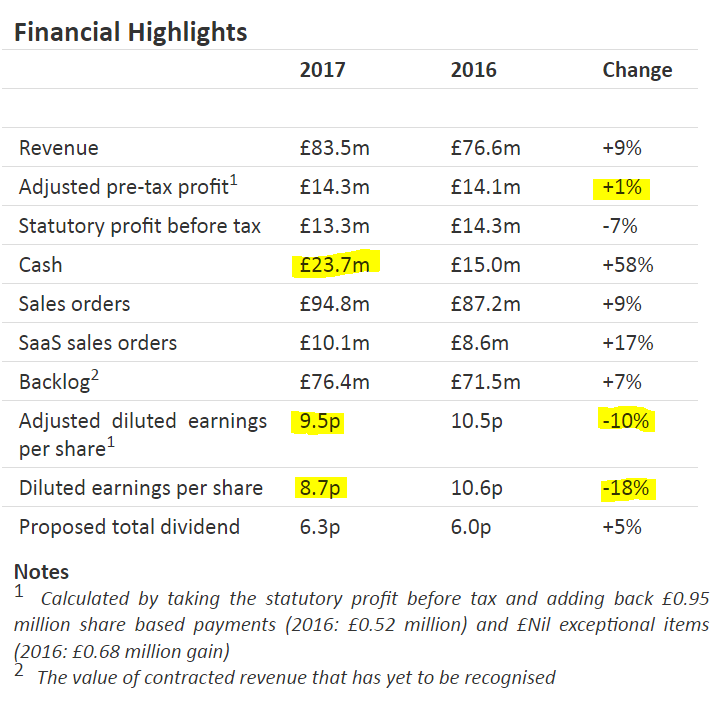
Working down the table, I've highlighted a few points;
- Adjusted pre-tax profit only up 1% - not very exciting, is it?
- Cash has risen well, to £23.7m. There is no debt, so that's a net cash figure.
- Why hasn't the increased revenues fed through to higher profit? Higher overheads - staff numbers have increased by 135, to 975. Plus R&D spending was doubled, to £4.6m (and this is all expensed as incurred, hence comes straight off profits).
- EPS has fallen due to a higher tax P&L charge compared with last year.
Dividends - note that the company pays out most of its earnings as divis, which reinforces that the cashflow is good, and genuine. Although due to the share price being high, this does not translate into a high divi yield.
The total divis for the year are up 5% to 6.3p - a yield of 2.7% - not madly exciting.
Balance sheet - is excellent. They don't capitalise any costs into intangibles, which is good.
The working capital position is healthy, with a current ratio of 2.31
There's £23.7m of net cash, and no interest-bearing debt.
Overall, very solid, so no concerns at all.
Cashflow statement - similar to the balance sheet, this looks very clean.
The business generates plenty of cash, some of which is paid out in divis, and the rest retained within the business. This is a very capital light model, with almost no capex - clearly a positive model.
Outlook - this is a bit waffly, although it does suggest that more growth is possible;
The directors believe that the Group remains well placed to deliver growth in the coming years. The Group's Digital Services division continues to benefit from the UK government's digitisation programmes, and from the strong and sustained growth of Workday.
In the Group's Digital Platforms division, Smart remains in a commanding position as the only automated testing product for Workday globally, and Evolve IC has passed a significant milestone with the successful deployment in 38 hospitals in the US.
While the opportunity for Evolve EMR in 2018 is muted, the directors remain confident that it is well positioned to capitalise on its lead in the NHS marketplace in the medium term.
In summary, the Group sees continued stability and growth opportunities for its Digital Services division and is encouraged by the strong position of its Digital Platform SaaS offerings globally. Going forward, the Group will remain focused on providing exceptional careers for staff and exceptional digital products and services for its customers.
Valuation - this stock looks expensive to me, given that adjusted EPS has just fallen, and forecasts are for only a modest increase in 2017/18. So why on earth is it rated on a growth company PER of 24 times?
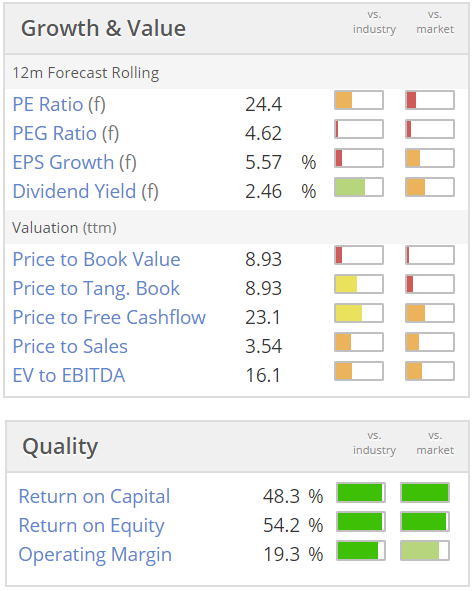
As you can see, it has very high quality scores.
My opinion - this is clearly a good quality company, with a terrific financial track record.
However, earnings actually fell in 2016/17, and there's not much earnings growth forecast. So I cannot see how this is worth a PER of 24 times. That looks significantly over-valued to me. The only justification would be if the broker forecasts are too conservative, which is often the case with apparently highly rated shares.
Investors would need to be very confident that Kainos can beat forecasts, otherwise you could be over-paying. Also this company is heavily reliant on contract wins. Whilst the pipeline sounds strong, profit warnings can happen with this type of company if a gap appears in the order book. Why take that risk, especially when the upside looks limited given that the valuation is so high already?
It's not for me at this price. Although it will go onto my list of quality stocks to potentially buy much cheaper a few weeks after a profit warning.
Blancco Technology (LON:BLTG)
Share price: 175.5p (down 5.7% today)
No. shares: 64.0m
Market cap: £112.3m
Chairman resigns - yet another red flag at this accident-prone company.
The Chairman, Rob Woodward, has announced that he intends to resign "at around the time of the Company's results for the year ending 30 June 2017, in October 2017".
This is surprising because he only became Chairman in Mar 2017. Although he was on the Board since 2013.
My opinion - I don't like this share one bit. Unexpected Director departures are something I'm going to pay a lot more attention to, in future. The learning curve for me recently was 2 CFO departures at Revolution Bars (LON:RBG) . Of course the company insisted everything was fine, but then we were slammed with a profit warning, caused mainly by cost over-runs and poor budgeting.
So in that case, people who were cynical, and played it safe by exiting the share, dodged a bullet. I was a bit too gullible perhaps, and as a result am nursing a hefty paper loss.
As regards BLTG, there are way too many red flags here, and I can't shake off the feeling that there could be more bad news to come. The Chairman's unexpected decision to resign, with no explanation given (not that anyone believes them anyway!)
The senior NED says today;
"Rob has contributed a great deal to Blancco and I would like to thank him for his professionalism, clear stewardship and counsel. The Board regretfully respects Rob's decision to step down and he will leave with our best wishes.
"We remain confident in Blancco's prospects. It is a market-leading business with considerable opportunities for continued growth."
Reading between the lines, that sounds to me as if there might possibly have been some disagreement over something. Personally, I wouldn't stick around in this share to find out. Again, why take the risk?
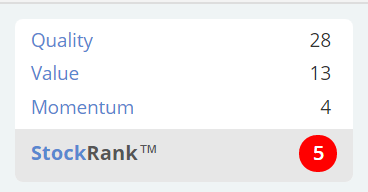
The Stockopedia algorithms are also sounding a loud warning klaxon, with a pitiful StockRank of just 5, and a losing style of "Sucker Stock" - I agree.
Some quick updates to finish off with;
Fastjet (LON:FJET) results, which look diabolical.
It's not worth wasting any time on this. The figures are just a joke.
I can only imagine that the repeated fundraisings are more about fund manager careers and egos, than commercial outcomes for their investors.
Fusionex International (LON:FXI) - delisting debacle - i.e. yet another overseas AIM companies shafts UK investors.
How could people have avoided the 64% loss today, from the company announcing it intends to de-list?
1) Don't buy shares in any Malaysian companies that list on AIM - they're probably dodgy as hell. Similar to Chinese companies that decide to list on AIM. I would widen that, and say don't buy any Asian or African companies that list on AIM - if you do, chances are that you're the patsy. Why take the risk, when the odds are against you?
Why would these companies come half way round the world to list on AIM? Probably because they're thinly disguised scams, and they've worked out that London has enough mug punters, and a sophisticated apparatus of smooth-talking liars (low level PR people & brokers) who will rip-off the likes of you and me, in order to earn a dishonest living.
We need to drive these shameless scumbags out of business, by refusing to participate in their deceptions.
2) Look at the accounts - Fusionex accounts are dripping with red flags - the usual culprits;
- capitalising a huge amount of costs into intangible assets, in order to create artificial profits
- unusually, it did actually pay a dividend. However, scrutiny of the cashflow statements show that this was a mirage - it didn't generate cash.
- respected bears such as Lucian Mears wrote scathing articles about this stock over a year ago, pointing out the numerous red flags in its accounts. Ignore this sort of thing at your peril - the best bears are usually right, eventually. Lucian is very smart, and a good guy.
- profits collapsed in 9/2016.
- Director shareholdings are TOO BIG. It's good for Directors to have plenty of skin in the game, but if they are above c.25%, then that starts to become risky, if they are unscrupulous characters.
- Fusionex shares are now effectively worthless. Many holders will be forced sellers, so this is really a way of scamming UK shareholders, forcing them to sell, so management can buy out the company on the cheap. It's a scam basically. I would sell, and move on, and learn the lessons.
De-listing should only be a last resort, if a company is about to go bust. Listing on the stock market is not a temporary measure, it is a long-term commitment. Even if the market rates your shares lowly, then it's the job of management to improve performance, thus earning a higher rating.
Fusionex management clearly either don't understand this, or are just con artists - having extracted funds from placing(s), now they don't need the listing any more, so they're off.
Good riddance to yet another pile of crap. Just don't fall for these overseas AIM scams. Enough is enough.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

34 comments
Many thanks Paul for your response.
I agree that EYE looks overvalued and the stock rank would certainly agree with you. I am certainly looking at the future potential, not historic valuation and, as such, recognise the risks involved. Most of my other investments are safe, debt-free, growth companies such as Somero, Zytronic and Headlam, plus the riskier, but very profitable for me so far, Paysafe. Hence, I have only taken a smallish punt on EYE on the basis that if it proves a flash in the pan it will have limited effect on my portfolio and if a multi-bagger, there would be little need to increase my holding.
I was surprised that the discounted share issue didn't result in a drop in the share price, in fact quite the opposite.
Time will tell.
The only other holding which would perhaps come into the same category would be Surgical Innovations (SUN), which I see as a turn-around company after a much needed change in management. If you have the time, perhaps you could comment, maybe after their next announcement.
Thanks again for your reply Paul and for your enlightening reports.
Nick
I am surprised more people don't take some notice of the charts. Fusionex has been trading under it's 200 day MA since December last which is negative territory for a chartist Using Stan Weinstein's methods, it has been in Stage 4 since that date and was, therefore, a definite 'sell'. Yet the fundamentals on Stockopedia give the share a 67 stock rank, a quality rank of 84, a piotroski score of 6 and an altman rating of 7.7 with no net debt which is hardly a cautionary set of figures. I always check with the charts as they are much more in tune with the current situation and usually give good, timely warnings
I've previously made a list of red flags based on various articles found on Stocko (including today's SCVR):
- AIM-listed & based abroad esp. Asia, Africa
- No earnings or divis which makes Growth & Value metrics impossible to calculate
- Lots of red in the stock's Growth & Value window
- High M-Score indicating dubious Earnings quality
- Risk of bankruptcy (Altman Score)
- Broker downgrades
- Declining 3m / 1yr price momentum
- Appears in James Montier’s Unholy Trinity Screen
- Low stock rank
- Low P-score indicating declining health trend
- Large pension deficit
- Validate any divi's against Free Cashflow per Share – if it’s negative then company funding divi’s from debt
- Director's shareholding >25%
- Large amount of cost capitalised into intangible assets, in order to create artificial profits
Unfortunately, there are many drivers for floating iffy foreign entities on AIM. The desire by the Stock Exchange to demonstrate that AIM is an international player against its competitor Stock Exchange platforms such as Nasdaq etc. The brokers and advisers (lawyers, accountants, financial PR etc) get paid for their due diligence, and then get paid ongoing fees for Nomad status.
So there are more drivers than there are negatives at the present, because loss of investor value doesn't show up in their various balance sheets. The fact that AIM is not just a market based on risk but is in danger of offering an open shop for foreign promotors to take advantage.
The reputational damage to AIM seems to be the least of anyone's worries.
How do you find out what origin the company is from other than word of mouth ?
Hi clarea,
If you look at the Stocko company page, the names of the directors might give you a clue (many overseas executive names with a couple of nominal Anglo Saxon NEDs) followed up by a look at the company's website (also linked directly from the Stocko company page) should point you in the right direction. If you can't find out/don't know the domicile of a company's principle business activity, is it really prudent to be investing in it?
Gus.
One of Paul's old "red flag" summary posts is here:
http://www.stockopedia.com/content/small-cap-value-report-gbo-koov-107216/
I think there are more.
https://docs.google.com/spreadsheets/d/1Tmi5-HKO5Vw70EFLymaaTzfNaBXCo4tkiM5IVKqBIx4/edit#gid=2
Paul' spreadsheet
Paul, looking forward to reading anything you write on Fusionex & other foreign AIM duds. I didn't hold FXI but did hold Rapidcloud (RCI), a smilar company. Maybe, as you suggest being sceptical about silly company names is a good starting point.
My own experience with Rapidcloud has been an education. Although the financials should have warned me off, I exchanged emails with the CEO / founder & found him affiable, PI friendly and convincing. There was also a British chairman which was encouraging. I then woke up one day & found out most of the board had gone along with the advisors & the listing.
I hope I have learnt something during the journey.
Dennis.
Guys -
I think that Paul produced a handy list of red flags to look for, following the Quindell fraud or the Globo fraud that he successfully uncovered. I was into Globo and his constant warnings saved me bucket loads. This must have been on or before 2015.
Would be handy to re publish this , especially for the newbies. I don't think there is a search facility on Stocko to do this quickly. Anyone able to help?
On the subject of DYOR etc., with regards to Fusionex International (LON:FXI) it took me 3 mouse clicks to bring up a discussion thread - albeit from 2013 - that would have put me off investing in this company. Two sides to the debate between a clear advocate and a sceptic, but full credit to regular contributor "cig" who did some digging and raised some pretty basic questions that absent convincing answers would have put me off investing.
Plenty of fish in the investing sea to move along to if the contributor commentary, whether it's a pro like Paul or a regular amateur on Stocko, doesn't stack up. Plenty of rampers and de-rampers with their own agendas on many other bulletin boards and blogs but by and large Stocko seems remarkably free from these.
Gus.
This is probably a 'strange' comment - but many of the companies people have discussed today have one thing in common - unusual company names! I personally stay well clear of any company with a daft /silly name; normally they try to allude to something sophisticated which is just code to try and fleece punters / investors like us.
As is usually the case in investing, simple is often the best.
Hi everyone,
Sorry I didn't get round to responding to queries & comments.
I'm still unloading stuff from my car, from the last trip yesterday, so have been humping boxes around all afternoon, for about the 5th day on the trot! Moving house is such a nightmare, I seem to have accumulated so much clobber, it's ridiculous.
Anyway, the good news is that I finally have room to breathe - my new flat is much more spacious than the old one - my new sitting room is bigger than my previous entire flat lol! And I've got 2 nice roof terraces, so can step outside and bask in the sun, if it puts in an appearance. This should be conducive to better SCVRs hopefully! (once I'm settled in)
Regards, Paul.
Paul, I'd also be interested if you could explain in detail the red flags at Fusionex International (LON:FXI). I took a £200 punt on it a few months ago because I thought it might do well as it looked like a Big Data company similar to WANdisco (LON:WAND). What prevented me from putting any more than small punt money on it was it being foreign and the suspicious negative net cash flow. In hindsight that should been enough for me to give it a wide berth, even with punt money. It appears to be a very sophisticated fraud as the FXI website lists a lot of blue chip clients.
Kind regards
Ricky
Hi Paul cracking work as always any pointers you can give in using Stocko to spot red flags would be appreciated.
Paul.
I realise you are, in your column, taking the view of the private investor. You are, of course, absolutely right that an unacceptably large number of foreign based companies on AIM turn out to be 'Norfolk Broads' of one sort or another. This is wrong for all the reasons you, and others, are constantly pointing out.
The fact that the majority of PIs are hopeful amateurs should not mean that their favoured pond should be filled with toxic fish swimming beneath the surface and as such, difficult to spot.
I am almost more concerned that these fish are brought to market by professionals in banking, broking, PR and fund management who earn fees and commissions from their activities. It's bad enough that the shares are offered to PIs who are able to, and should, do a bit of their own research, but far worse that the 'professionals' must stuff these millions of questionable shares into funds over which they have control on behalf of retail investors. Investors who are time-short or unsure of the market and, presumably, somewhat risk averse and who believe that the savings they commit to the funds are responsibly managed.
The slow death of so many of these companies, in spite of the strident warnings from you (and Tom W. et al.) must mean that the institutions continue to hold long after the red flags are spotted. Is it that the fund managers are inept, are they plain lazy, too embarrassed to admit buying a dog or is there something more sinister going on? By this I mean, is there a general agreement, unwritten naturally, that they will collude with the dog's promoter and, in turn, will expect their peers to buy the next bit of rubbish they are in turn promoting?
I cannot, otherwise, understand how it is that these millions of shares are sold into a sophisticated market, time and time again.
Hi Paul, I was interested to see your opinion on Fusionex as I always thought this was a good company, getting increasing orders, but like so many early starters, running into a few difficulties along the way but largely misunderstood and consequently ignored by investors. Obviously I missed these red flags and look forward to seeing your research so i don't make the same mistakes in my future investments. Dave Cox
I have also been wondering how the system really works. If UK companies and markets are supposed to be some of the better regulated ones it makes you wonder what some other exchanges are like. And it's not just dodgy foreign companies. TrakM8 had a placing at 333 p in late December 2015. I wonder who's sitting on those?
Does anybody know of any articles about what happens behind the scenes in the equity markets? I've seen the term 'accelerated book build' now and then and it seems that one can drum up a few million in no time at all, leaving little time for 'due diligence' and careful enquiry.
On a more general note, I find this forum extremely valuable and am impressed by the knowledge, expertise and constructive input of contributors here.
Carcosa - any particular reason why you sold out of Fulham shore ?
Hi harvs19,
Wish I could say it was a reaction to the news related to the resignation of the Pizza Express CEO; but I was unaware of this at the time of my sale (and had I known I doubt it would have influenced mydecision anyway).
My reason was that i wanted to release some cash for another investment and looking around my portfolio this share price was not performing in the way I wanted over the last couple of years. I don't much like 'growth' stories, having come from a value investor background, as they tend to crash and burn at some time in the future. However that 'sometime in the future' can be anything from next week to 5 years down the line!
Overall, as retail rollouts go, I think FUL is a reasonable share to own although not the best available and it was never considered a 'core' holding for me.
=====
I remember a good article by Paul (Or Ed?) relating to red flags as mentioned by Ramridge. Anyone have the link?
Partly the reason why Fulham Shore (LON:FUL) is down because I sold out of it and given the number of shares I sold it had an effect on the share price. However with a share like this a few percentage point swings either way in a random day should be ignored. Illiquid shares like this react accordingly.
Fusionex International (LON:FXI) is a Malaysian company and (as I live in Malaysia for years) you can guarantee corruption and fleecing of investors for any Malaysian company. Corporate governance does not exist an any meaningful way.
According to the Times Fusionex told its two brokers of its plans on Wednesday night, leading to a row with Peel Hunt, which promptly quit. Its name was absent from Friday’s announcement, which was issued by the nominated adviser Stifel, the other joint-broker. Buchanan PR also quit.
If forecasts are to be believed then shareholders could have expected significant returns in 2018 or so. Obviously too tempting for the BoD scum to allow ordinary shareholders to be rewarded with.
Fastjet (LON:FJET): More of the same in todays RNS. Been discussed on Stockopedia numerous times so should not be any surprise when this comes to a crashing end ;-)
The Blancco Technology (LON:BLTG) announcement is just bizarre. Presumably Mr. Woodward would have felt comfortable with the personalities on the board when he became chairman 2 months ago. If he didn't feel comfortable he could have opted for an interim chairman role while a new chairman was pursued. The only "new" board member is the interim CFO but you'd have to assume that Woodward had a role in picking him. It's hard to imagine the relationships souring so badly in the span of what can't be more than 1-2 board meetings under his leadership. Since he's a former strategy consultant and a former banker I'm going to speculate it's strategy or acquisition related.
Hi Paul Is Warpaint not the big new disruptor in the world of global cosmetics? Have you had a look at this one?
Very much looking forward to your write up of Fusionex. You are a good teacher. Learning how to avoid the next Fusionex, Globo, or whatever is so valuable.
Hi Paul I bought this share (KNOS), because it was one of only a few local PLCs and seemed to be doing quite well, but in the end i sold out late last year at a small gain, after the dividend had been paid because I just found it was slow too move and not half as exciting as another local firm First Derivitives (FDP) which provides IT to financials and is now selling its products into retail and engineering companies. It has just posted results and its shares are now trading at £30.00 + an increase of around £4.00 in just a week I suspect in some part due to the floatation of ALFA on the LSE and its (FDP's) growth over the last year.
Hi Paul,
Could you comment, please on Eagle Eye (EYE).
Back on 16 November 2016, you said it might be of interest once it had raised more cash. It announced a placing last week and in spite of rather too large a discount to those greedy institutional investors. The SP has gone up significantly. I made a small investment a few weeks ago and topped up last week.
Your thoughts please.
Nick
Hi Hedgecutter,
Eagle Eye Solutions (LON:EYE) - there was an interesting article about this company in SCSW recently.
As I mentioned back here in Nov 2016, I think the company looks interesting.
The valuation looks very expensive on the historic figures, but we're in a bull market, and people are prepared to pay up for growth companies with good future potential.
Overall, as a more speculative share idea, in current market conditions, I think this share has potential.
Regards, Paul.
Many thanks Paul for your response.
I agree that EYE looks overvalued and the stock rank would certainly agree with you. I am certainly looking at the future potential, not historic valuation and, as such, recognise the risks involved. Most of my other investments are safe, debt-free, growth companies such as Somero, Zytronic and Headlam, plus the riskier, but very profitable for me so far, Paysafe. Hence, I have only taken a smallish punt on EYE on the basis that if it proves a flash in the pan it will have limited effect on my portfolio and if a multi-bagger, there would be little need to increase my holding.
I was surprised that the discounted share issue didn't result in a drop in the share price, in fact quite the opposite.
Time will tell.
The only other holding which would perhaps come into the same category would be Surgical Innovations (SUN), which I see as a turn-around company after a much needed change in management. If you have the time, perhaps you could comment, maybe after their next announcement.
Thanks again for your reply Paul and for your enlightening reports.
Nick
Hi Paul, wanted to ask your opinion would you consider Franchise brands (FRAN) to be a growth stock? not sure if you looked into it, but could be a lot of potential in this stock.
Hi vik2001,
Franchise Brands (LON:FRAN) - I know this company of old, as a friend of mine set it up a few years ago.
The shares have done very well since listing. It looks very expensive on current broker forecast, but of course that might be because the forecasts are too conservative, I don't know.
I will review the figures when the company next reports.
Regards, Paul.
I'm looking forward to hearing more about Fusionex and what went wrong Paul! I hold Kainos (LON:KNOS). They do digital care plans and are expanding into States & Germany so they're in a position where they're investing, diversifying AND still making cash. Here's Shares' news article. https://www.sharesmagazine.co.uk/news/shares/kainos-will-be-glad-to-see-back-of-general-election It's still a hold for me in hope next results should be better, after all, demographics are on their side and NHS funding/efficiency will either improve, or they will refocus on private healthcare. Results in 2016 were also exceptionally good so probably should not have expected same again but Cannacord have raised target to 290p.
Paul - I bought Kainos (LON:KNOS) just after the Brexit referendum result and made a decent amount from the bounce back, selling last autumn after the half-yearly results. Even then they were flagging that profitability and EPS was flat on H1 2016 results so I was surprised it remained on a high PE multiple since then. One of its biggest customers is the NHS and, as a sector I work in, I know there's been a slowdown in IT spend and this might partly account for slowing growth and profitability. I don't think it ever says how much of its revenue is from the NHS but, checking my notes, last year around 86% of its revenue was from the UK.
Another risk with Kainos (LON:KNOS) is that part of the business (c.14% of revenue and profits) is implementing the software of another company called Workday. If Workday ever changed the fees they give to Kainos (LON:KNOS) then that could harm revenue, albeit not on a massive scale.
On the plus side the company has been spun out of a university and seems to have great staff morale who are loyal. I like those features in businesses I invest in. The CEO has been with the company since 1989 when he started as a graduate software engineer.
On a different note does anyone know why Fulham Shore (LON:FUL) has had a bit of a dip today? I am guessing its simply because it's quite an illiquid share so prone to wild movements but just want to double-check before I top up!
Id also be interested to know whats caused the Fulham Shore (LON:FUL) drop today.
The resignation of the Pizza Express CEO, and the company's suggestion that sales are softening, are likely to be factors in drifting Fulham Shore price. Ironically softening sales for PE likely to be partly due to increased challenge of competitors such as Fulham Shore !