#11 Frontier Developments - back from extinction

This is #11 in our "Twelve Stocks of Christmas 2025" Series. You can review the full set here.
The Pitch
Frontier Developments (LON:FDEV) is the AIM-listed game developer behind hits like Jurassic World Evolution and Planet Zoo. After a difficult period of failed diversification, a back-to-basics strategy is driving a turnaround. With a StockRank of 96 and a cash-rich balance sheet, subscribers have been waking up to the recovery. Brokers are now revising estimates upwards after a successful game launch, and the re-rating may have further to run.
The Big Picture
Frontier spent years attempting to become a third-party publisher and branched into sports titles. But after the F1 Manager series struggled, the share price collapsed and the company’s reputation with it. Management decided to refocus entirely on its core, world-class niche: Creative Management Simulation (CMS) games.
- Why this works: Unlike hit and miss sports titles, CMS games like Planet Zoo have long demand tails, generating high-margin revenue for years through downloadable content add-ons (DLC) and offer periods.
- The evidence: The strategy’s main test was November’s release of Jurassic World Evolution 3, a sequel in a successful series. The launch was near perfect, which seems to be proving the core business model, and more importantly, execution, remains intact.
Going Deeper
As active investors, it’s not enough to wait for half-year reports. We’ve been sleuthing the data to get an early read on Jurassic World Evolution 3’s sales numbers (JWE).
- The Launch: The October release of Jurassic World Evolution 3 (JWE3) was a critical test. It passed, hitting #1 on Steam and received record reviews on Metacritic. Frontier rushed out a bullish trading statement.
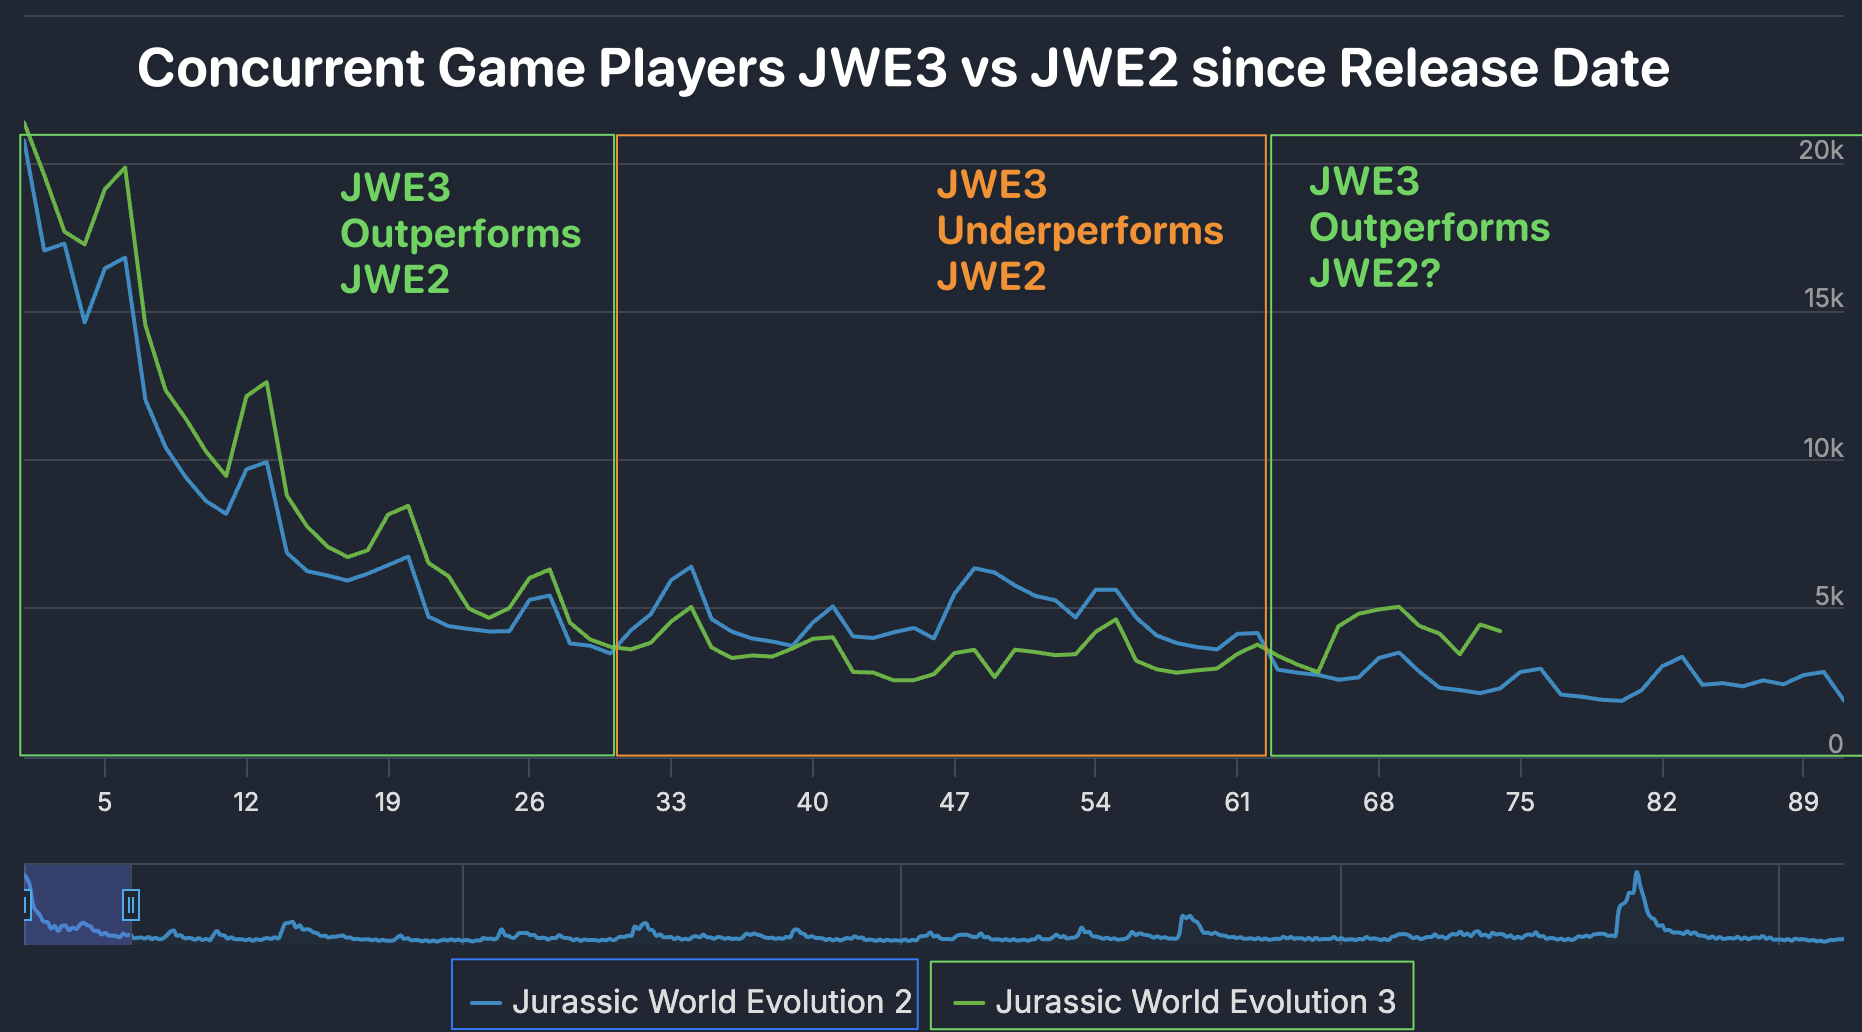
- The Fade: While launch sales were strong (500k units in 2 weeks), deeper SteamDB real usage tracking revealed a temporary fade later. While the JWE3 sequel was tracking 18% ahead of its predecessor (JWE2) in the first 30 days post release. Player activity then dropped to 73% of JWE2 in the second 30 days, before surging to double in the last week. Can JWE3 continue to match JWE2?
- The Pipeline: Importantly, Planet Zoo has the highest "sustain rate" in their game portfolio, and is very high margin given it’s wholly owned and without third-party licensing costs. Frontier just confirmed a sequel for release next year which underpins the forecasts.
What The Brokers Say
Following the JWE3 launch, the City has been ratcheting up their numbers. At Stockopedia we love to see these earnings revisions, as they drive price momentum.
- Upgrades: Panmure Liberum hiked their FY26 profit forecasts by 24% and raised their target price to 565p. Zeus Capital is even more bullish, upgrading their profit forecast by 30% and lifting their target to 620p.
- Valuation: Despite a 120% share price rally in 2025, the brokers argue that their forecast valuation of 12.5x EV/EBIT is modest. Peers like Paradox Interactive trade closer to 14x.
The Bear Case
These kinds of gaming stocks are hard to own as buy and hold forever shares. Frontier’s volatile share price history is a testament to that. Here’s what could spoil the party:
- Hit Dependence: Gaming business models are volatile. If the upcoming Planet Zoo sequel underperforms, the recovery thesis could break. Can sequels work indefinitely? New titles may be needed for growth.
- Post Launch Fade: The drop-off in JWE3 player retention compared to JWE2 was a yellow flag. Christmas discounts appear to have helped in the last week, but weakness or poor DLC drops may fail to excite new and current players, which could lead to the revenue sustain rate disappointing targets.
- Leadership transition: This month, the steward of the turnaround, CEO Jonny Watts, stepped aside after 27 years company tenure. CMO Jo Cooke has been promoted. The shares dropped 7% on the news.
The Bottom Line
Frontier Developments has, so far, successfully managed a tricky strategic shift. With a proven strategy, a cash-rich balance sheet, and good institutional backing, it offers a classic, if speculative, turnaround profile. David Braben, founder, remains President which may mean the recent drop on the CEO change is an over-reaction. For active investors willing to stay on the pulse of game data, it is a good candidate for a continued 2026 rerating.
(The author is a shareholder in Frontier Developments)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

8 comments
If Frontier Developments (LON:FDEV) is a “textbook” case and follows the Kaczmarek 2025 research, we should now anticipate 60+ Days of PEAD, sending it closer to the Panmure target price.
Excellent interims out today - brokers upgrading etc, JWE3 confirmed hit - I've left a brief comment on the DSMR.
From the broker:
One Frontier Developments (LON:FDEV) point not mentioned is its repeat history of 2025 Earnings Surprises causing signifigant share price Jumps. A new Machine Learning paper “Beyond the last Surprise” by Kaczmarek published last month investigated this effect. I have run the Jump% FDEV numbers past Perplexity who describes it as a, "textbook case".....
AI: Frontier Developments is not merely a strong 2025 performer; it's a textbook case of small-cap PEAD in action. The stock's 4 distinct post-announcement rallies, combined with its volatile earnings history and minimal analyst coverage, align precisely with Kaczmarek's framework predictions.
A contender for a 2026 repeat? (I hold)
For more detail see: https://ideas.repec.org/a/eee/...
Ian - interesting analysis!
I think the trading and results update on January 14th should be positive, given the SteamDB info on JWE and the general trend of updates. We do see time and again that companies often behave the same way in and around trading statements, so I wouldn't be surprised to see a jump. If it is positive, then we should also see earnings revisions from the brokers through the rest of the month. From that point on, the market will start looking forward towards Planet Zoo.
Do we know whats next? Elite Dangerous (space worlds/HALO) looks interesting. The rest seem Nintendo'ish without the Mario and Link. Warhammer is mentioned but not on their website.
Everything pales into insignificance against the groundbreaking release of Arc Raiders by the small Swedish software house Embark Studios. I did find it quite hard to buy Frontier Developments (LON:FDEV) when they came up on my screen in July and I was glad to sell them recently when momentum failed.
Best of luck to holders!
I'd interpret the last "Concurrent Game Players" chart to mean that JWE3 usage is evolving like the earlier releases, plus a bit of noise. Can we really say more than that?
seems a reasonable summary.
one might also need to compare popularity of the movies - looks like both movies made similar amounts at box office - it does look like though box office take is dropping with each movie - $1.3 billion 2018 movie - $1 billion 2022 moie and $860 million 2025 movie. Sop not great trend ref movie success - however thats still very decent numbers at the box office - so i supect the game can perhaps manage just fine even if the movie isnt as popular "as it was"
imho it kinda makes sense that there is enough fresh youngters every 3 years that would want to be buying their first "dinasaur game" - that it should be money for old rope - its possibly the same for the movies too - heck add an ever growing collection of "golden oldie" plyers froim each new 3 year sequence and its a pretty good niche they have - as long as there is no competition !!!
part of the problem with drilling too much down to the detail is that any tailwinds now become headwinds as soon as the money has been earned.
Note i would agree that drilling down to detail to see if next trading update is likely to be good or bad is always sensible.
my main worry here would be if they have gone back into their shell and are only concentrating on theoir core stuff that may set ceiling on how well they can do - previously the sky was then limit if they could have competed with the big boys.
So under current plans are they ever going to make more than £20 mill per year profit? and if they are only going to do half that this year and next whats the upside here - there doesnt appear to be any unless they can churn out more than £15 mill pa in regular free cashflow for shareholders. could they slash costs so that they are making £30 mill per year profit ? is that the cunning plan. I can see why the ceo is the exc ceo bearing i think is perhaps more a gaming enthusiast at heart rather than a "money man"