#12: Northern Bear - raising the roof

This is #12 in our "Twelve Stocks of Christmas 2025" Series. You can review the full set here.
The Pitch
Northern Bear (LON:NTBR) is an AIM-listed specialist building and support services group. With a StockRank of 99. While this may be a relatively unknown microcap in the wider investing universe, many subscribers will be aware of this SuperStock due to its high score in all of the QVM Ranks. It is rare to see a company where the share price has doubled in the last year, still trading on a mid-single-digit earnings multiple.
The Big Picture
Northern Bear is my Momentum pick for the “12 Stocks of Christmas” with a Momentum Rank of 93.
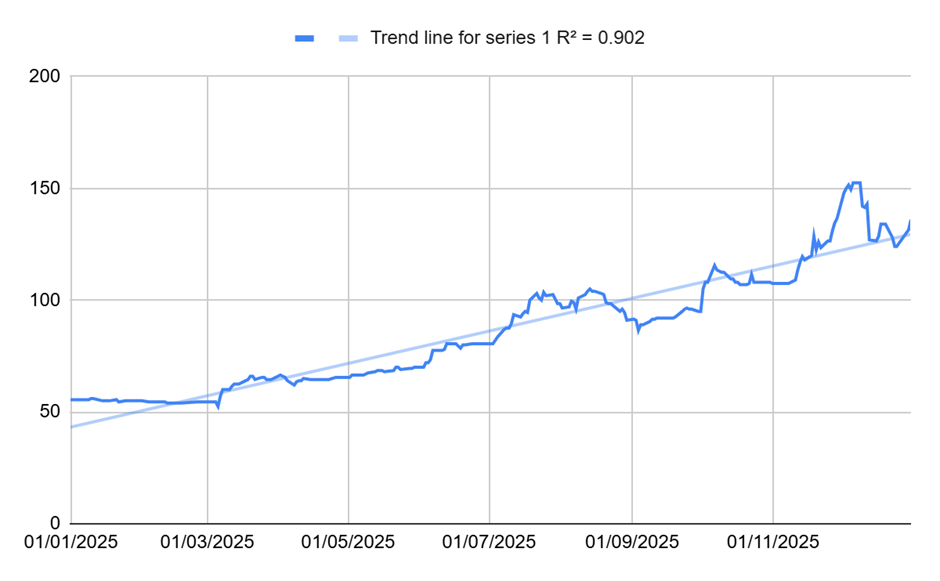
- Smooth Trend: Ed has written about the importance of smoothness when it comes to trending stock prices, and I’ve shown how investors can measure how closely price action matches a line-of-best-fit using an R-squared value. In this case, the figure of 0.90 suggests that this is a stock where the trend is definitely your friend:
- Balance sheet reborn: I have been sceptical about the balance sheet strength in the past, as trade payables have often exceeded trade receivables. This didn’t leave much leeway should the company have issues with being paid, or suffer from an onerous contract. While the current ratio is still only just above 1, the company had £3.8m of cash at 30 September, giving enough headroom that I no longer consider this too risky to invest. Instead, it gives them scope to expand via acquisition, or return cash to shareholders as a special dividend, as they have happily done in the past.
Going Deeper
Northern Bear has been listed since 2007. The aim of the business was to consolidate independent specialist contractors under a single strategic umbrella, combining their operational expertise with centralised finance and governance. Initially, the focus was on roofing contractors with Isoler, Springs Roofing, and Wensley Roofing forming the foundation of its group structure.
From the beginning, Northern Bear’s strategy has emphasised the autonomous operation of subsidiary companies backed by central guidance and financial planning. Over time, it added capabilities in electrical contracting, fire protection, materials handling and building services, mostly through acquisition. Geographically, their focus remains on Northern England. One subsidiary, H. Peel & Sons, undertook interior fit-out projects throughout the wider UK, but this was closed in FY25.
Northern Bear’s operating model consists of a holding company and roughly ten subsidiaries. These cover three principal segments:
- Roofing Activities: providing slating, tiling, leadwork, felt roofing, refurbishment, maintenance and more recently, renewable roof installations like solar panels.
- Materials Handling Activities: supplying, maintaining and renting forklift trucks and warehouse equipment.
- Specialist Building Services: which include electrical contracting, fire protection, building maintenance and refurbishment, sound insulation, and consultancy services in health & safety and environmental compliance.
There are a couple of reasons that Northern Bear looks likely to be an outperformer in 2026:
- Earnings as well as price Momentum: while price momentum alone can be a good indicator of positive future returns, it can also add to the risk of overvaluation if it isn’t backed by fundamentals. In this case, the company has seen several broker upgrades since the summer for both forward years:
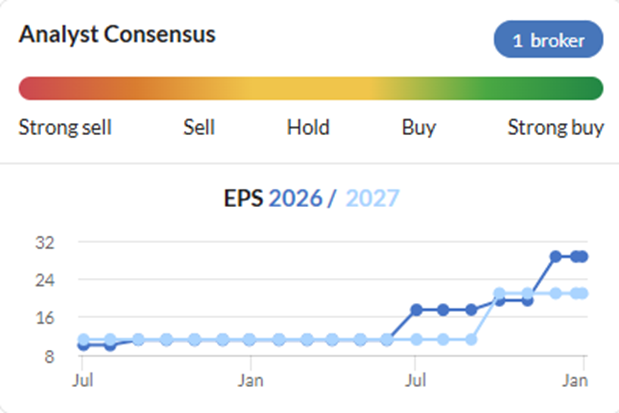
- Still very cheap: FY26 forecasts put this on a P/E of less than 5. Forecasts for declining EPS in FY27 will see the P/E rise to around 6.5x. However, the company is cautious about providing forward guidance, and EPS figures may be upgraded in time.
What The Brokers Say
There is just a single broker here, with Hybridan highlighting the company’s improving quality of earnings and lack of debt. They point out that the forecast P/E of 6x for FY26 is significantly lower than the 10.8x weighted average for the construction services sector. They believe a higher P/E rating is warranted.
The Bear Case
Investors need to be wary about a couple of factors that may impact trading, or the percpetion of the business:
- Poor disclosure: the company’s reporting leaves something to be desired, in my opinion. This year’s H1 operating profit figure included £1.3m that “arose from the Group's normal trading activities”. However, they give us no clue what this actually was, and then don’t exclude it from “adjusted” operating profit.
- Weather: There is no doubt that dry weather benefits this company. A significant proportion of their business is still in the roofing segment, which requires dry conditions to operate effectively. While the Summer period was very dry, Autumn was wetter. It is probably too soon to call whether this will have been a headwind for the company in H2.
- Lack of competitive advantage: While the individual subsidiaries of the group may benefit from the centralised procurement, finance and planning functions, compared to stand-alone operations, there is no unique product here. To generate higher returns compared to competitors, the company will rely on brand and operational excellence as its main advantages. These are not typically the strongest, meaning long-term average returns on capital are unimpressive.
The Bottom Line
While the company looks conservatively financed and has improving prospects, the lack of a unique product means that it will never be the highest-quality business. However, it doesn’t need a huge competitive advantage to be a good investment. Strong earnings Momentum means that this is very cheaply valued, despite a rising share price over the last year. This share price Momentum points towards further possible gains in 2026.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

11 comments
After a 20% jlift I sold the bulk of our investment last November. The remainder is there to keep my eye in. Buy the dip and sell the peak for now, unless it's a gold miner!
Weather, 2025 was the sunniest year, on record.
Bear point the spread is pretty wide. I can't even get a price on my platform, at the moment, no quotes available at present.
I reduced my order to under 300 shares and price is 140p, shows how illiquid this stock is.
I might somewhat defend the compony - if one does large contracts - some of which might be at "fixed quotes" its tricky one might make a killing - but much can go wrong. If they have been lucky enough to make a killing from one of their large regular customers the last thing they would want to do is shout that from the rooftops to all and sundry.
all that matters is that they have been 100% transparent from the get go that they have a one of brucie bonus here - if they are choosing not to disclose the exact reasons - well i wil trust them enough to know that we dont really need to know - and it might be better that its not over publicised if they have had a contract that delivered amazing margins - that might lead teh customer to expect cheaper in future or some sort of kickback. The good news is that they they arent pimping things up - its one off and wont repeat so little relevance to buisness valuation - other than the obvious good news that they have extra cash.
Its tricky one to work out if the good times will continue - i have held since half the price and have been tempted to top slice and probably should do if it hits 150p again - but p/e is still only showing as being 6 - so perhaps further to come. I do applaud the note of caution though ref your post - construction is rarerly an easy place to make money - and things like the weather can throw a spanner in the works.
My viewpoint ref weather is that most years it should not be a huge problem - but really bad year might half or wipe out profits temporarily - perhaps they benefitted from really good year - but most years now arent terribly bad up north (hmmm its almost knee deep in snow as i type this) - so i am not over worried about the weather - but i would agree its safer to sit on sidelines and wait if one has worries - if they do have poor h2 i am pretty sure the price may tank unless they have a very solid outlooks statement that eases the pain - to me the general outlook is more important than anythiong else - eg will they say they can deliver £3 mill net profit next year "presuming no bad news" - if they can say that then any temporary issues with weather - or one of contracts doesnt alter the bigger picture - in that regard unfortunately they dont give much away - they certainly dont tend to over pimp the future prospects - something i quite like.
Very good 'colour' to add to the article rmillaree thank you!
@rmillaree do you have any tips for the new year?
i dont do tips really i am anything other than mystic meg- often shares i hold take long time for value to out - its literally been years with Northern Bear (LON:NTBR) - overall my returns are unspectacular compared to many on here - i probably aint the best at spotting a value trap - value traps are best avoided like the plague !!!!
if you are putting me on the spot ref my some sensible value picks i would say
Jet2 (LON:JET2) - well capitalised company - pe under 7 - slight worries over bookings perhaps being slower than last year. airlines/travel companies are above normal risk investments though ! - this seems a fairly reliable stock.
ZIGUP (LON:ZIG) - this havs bounced 20% off its recent lows so not as good value as it was but p/e is only 7.2 now and company seem to be trading fine.
Greggs (LON:GRG) - this is up 10% from its lows but is a sound company pe now 12.8 it was below 11 - they have tailwinds at present so next trading update might NOT be good - one to watch if it dips back closer to 1500 without things getting materially worse
B.P. Marsh & Partners (LON:BPM) - ntav fully diuted is now 900p plus and shares are at 680p so decent discount to ntav -
£BOWL - pe of 11.7 is decent value seems to be trading fine and canada rollout seems reasonably low risk way of upping profits other things being equal
Eurocell (LON:ECEL) - pe is 6.2 - nextr trading update may be sketchy though with retail being tough - not sure how much extra rates costs wil screw them over yet if anything ?
Spectra Systems (LON:SPSY) - pe is 10 frowth sems to have gone here - froth was related to large contract that i think was always flagged as being one off - i think many thought more was to follow there m,ay be but they seem to be back to core stuff
to me these all seem decent value - they may seem decent value though as things are not going swimingly fantastic perhaps - so you pay your money and take your chance. deffo more value stuff here compared to garp.
yea I'm definitely susceptible to the value traps but I actually did some thinking this year about what's worked for me and it's when I've followed a company for years and maybe bought and sold at the wrong times but then seen it fall to an absolute pit and then buy when I see an actual recovery. So not bag holding all the way but knowing the story well.
@jet2 - I have loved the business but the profit margins are compressing; not helped by the Gatwick expansion
but the profit margins are compressing; not helped by the Gatwick expansion
margins will ebb and flow - as long as they make a sensible margin and keep increasing sales then profits shoudl go long term - even if that may not be happening right now due to margin compression. tricky one your caution might be right here - balance sheets are geting replenished after covid - so we dont really want any price wars and there is always potential for that to happen.- and all it takes is one party to start that. Overall i am happy though adding when there are clear headwinds but overall direction of sales is good as i feel the headwinds wont be present forever. a p/e of 7 for it still to be good outtake even if margins dont match prior peaks.
Interesting well presented appraisal, but I wonder why they like MJ GLEESON (LON:GLE) stick to ‘the North’. Most of the wealth resides in the South, and they have roofs there too.
(Disclosure: I hold GLE and live south of Watford).
Northern Bear (LON:NTBR)
historically they had a very flakey balance sheet withn large payables book and net debt.
They have also had a couple of acquisitions that havent been briliant so they are perhaps wary ref expansion.
hey have also focused on buybacks - the share count was 19 mill and is only 14 mill now - with lowly rating its bveen a great way to pimp up up historically by reducing share count.
I suspect their work is old school ish - they know the North labour will be stable - its would be big effort expanding down South and not without risk.
Note if they continue to generate something close £3 mill pa clean profits - they do have scope to do something with that cash that could also tubocharge earnings - so who knows.
On the flipside they are in nice sweet spot ref profits at present - its not always easy in their sector to avoid bad times though - they seem to be doing on in hard times though as things stand but who knows if they will continue to churn out decent numbers as they are doing.