12 Stocks of Christmas: Billington Holdings

For my contributions to the 12 Stocks of Christmas, I am choosing four stocks that epitomise Quality, Value, Momentum and Growth for me. Yesterday, it was Value; today, it is Quality.
On the 9th Day of Christmas, my true love gave to me:
Billington Holdings (LON:BILN)
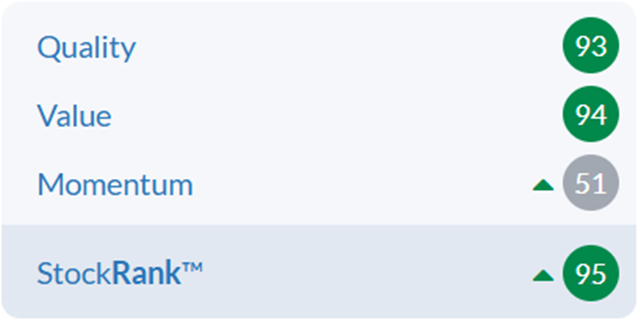
Billington has an impressive 93 Quality Rank:
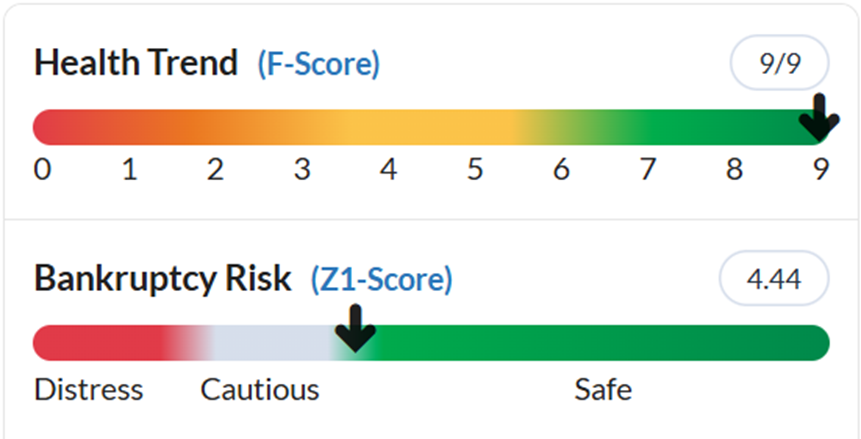
This is partially due to its 9/9 for Piotroski score and bulletproof balance sheet:
The Beneish score flags this as a potential earnings manipulator. However, having looked at the accounting details, I don’t believe this is a company that has manipulated their earnings.
There is an even better reason to consider Billington a Quality stock, and this is because it regularly earns a return on capital significantly above its cost of capital:
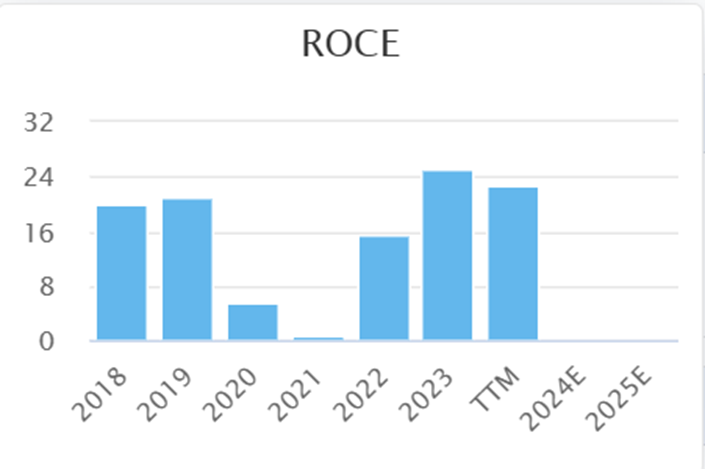
It isn’t the perfect share in this regard. It struggled during the COVID-19 years when there was little investment in construction. This cyclicality is why the stock is on a forward P/E of 7, not 27. From studying high-return quality compounders, I have developed what I call an MROC framework. I am looking for companies with a Moat, Runway to grow, have Operational Leverage, and I want to buy them Cheap. I believe Billington hits all four of these criteria:
Moat
As already touched on, the ability to generate high returns on capital or equity most of the time is a sign that the company has a moat:
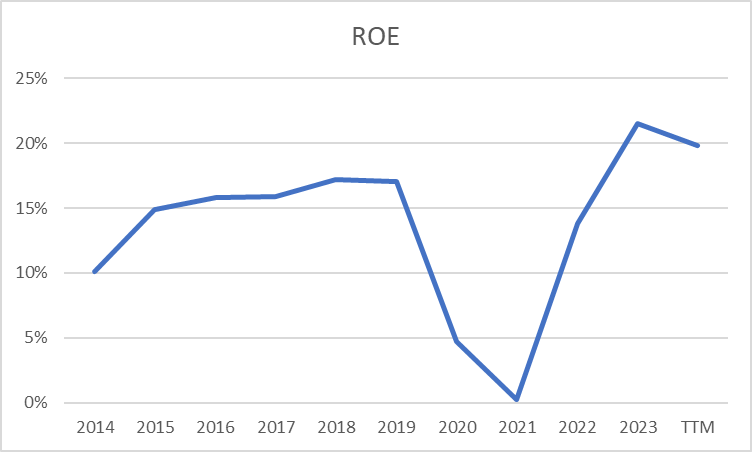
The ROE is particularly impressive here, as the company has held increasing net cash in recent years. In this case, the moat appears to be the niche they have in the structural steel market and the ability to deliver complex projects. This may not sound like the strongest of moats. However, the returns on equity suggest that competitors haven’t been able to breach it so far.
Runway
There continues to be scope for a company of this size to take market share from larger competitors. In addition, the company has recently embarked on an investment program that will see greater automation in its process flows. This should see not just better efficiency but also an uplift in capacity. The benefits of this will take time to come to the bottom line, but it shows there is plenty of scope for the company to invest its growing cash pile to drive EPS growth, not just return cash to shareholders.
Operational Leverage
In the last 10 years, the company has grown revenue by about 3 times. During that time, net income grew by 7.1 times. Shares have only been issued to satisfy options during that time. This suggests that the company has a decent operational leverage. I expect future EPS to grow faster than sales in the medium term in the same way as it has in the past.
Cheap
The Value Rank of 94 is based on a number of positive metrics:
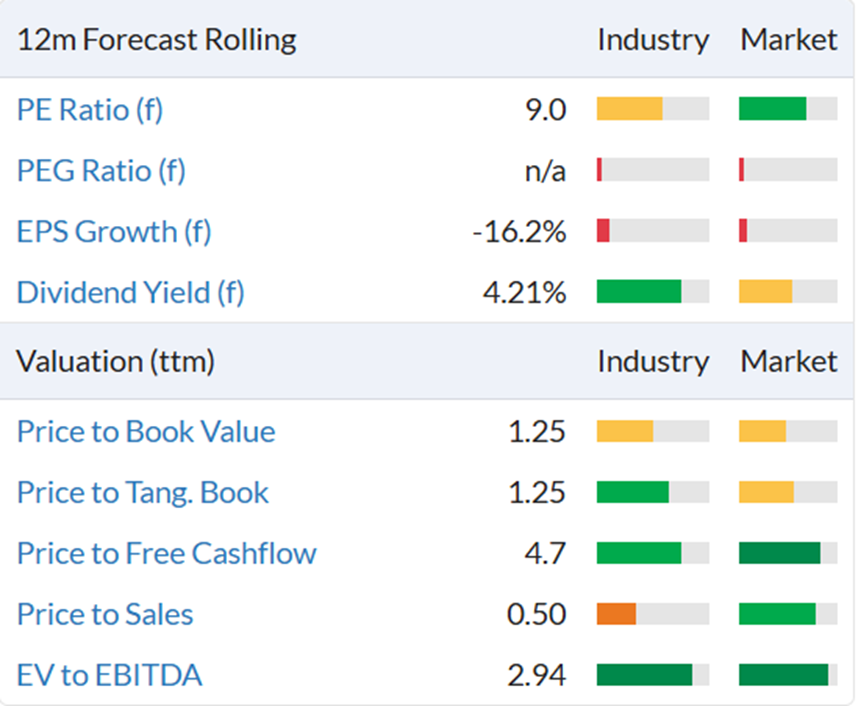
One of the reasons this isn’t more highly rated is that earnings are forecast to decline going forward:
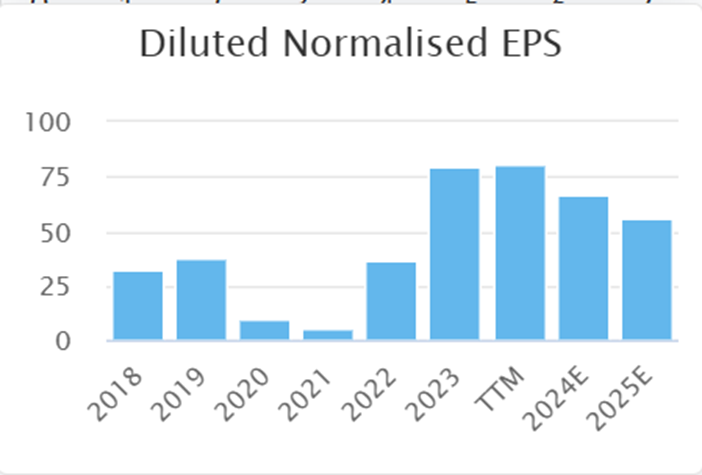
It is clear now that one-off factors partly drove the strength of 2023 EPS. Namely, pricing contracts based on continued inflation which moderated during the year. However, 2024 estimates have had repeated upgrades during the year, suggesting a management team that wants to under-promise and over-deliver:
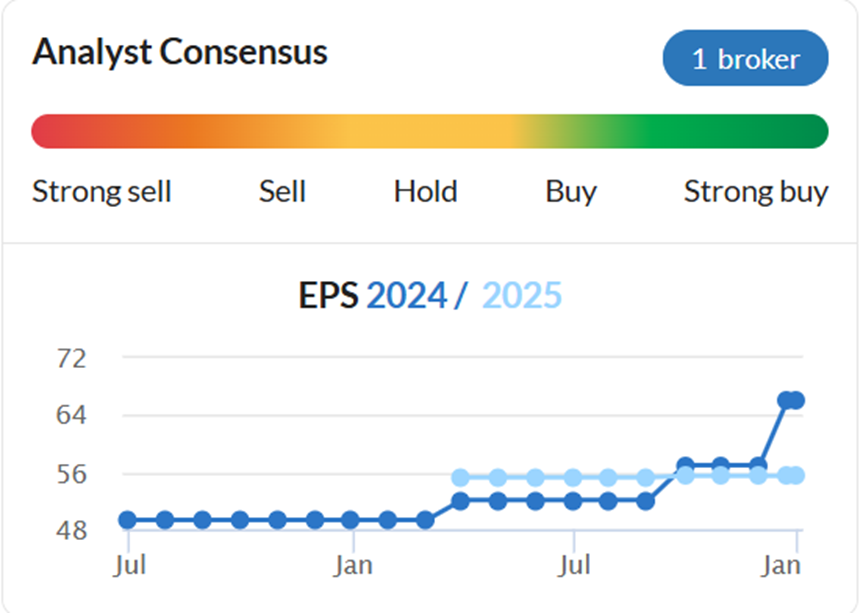
I wouldn’t be surprised if we see exactly the same pattern of upgrades during 2025. The alternative is that this is a true reflection of how poor the current end markets are for them. However, even if this is the case, the company is only trading on 9 times trough earnings with significant net cash. When better market conditions return, it will continue to reinvest its capital to drive sales and earnings growth, as all quality compounders do.
[Disclosure: Mark owns shares in Billington Holdings (LON:BILN) ]
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

2 comments
After visiting I believe excellent management with good team. Cash of £20m, no goodwill and smaller subsidiaries growing strongly. Large weak competitor SFR.
I’m an investor, I also impressed with the management when they present, also like the efforts they make to communicate.