12 Stocks of Christmas: Serabi Mining

For my contributions to the 12 Stocks of Christmas, I am choosing four stocks that epitomise Quality, Value, Momentum and Growth for me. Today, it is Momentum and a contribution that is very timely given the continued strong momentum yesterday, which sparked some chatter among our community.
On the 10th Day of Christmas, my true love gave to me:
Serabi Gold (LON:SRB)
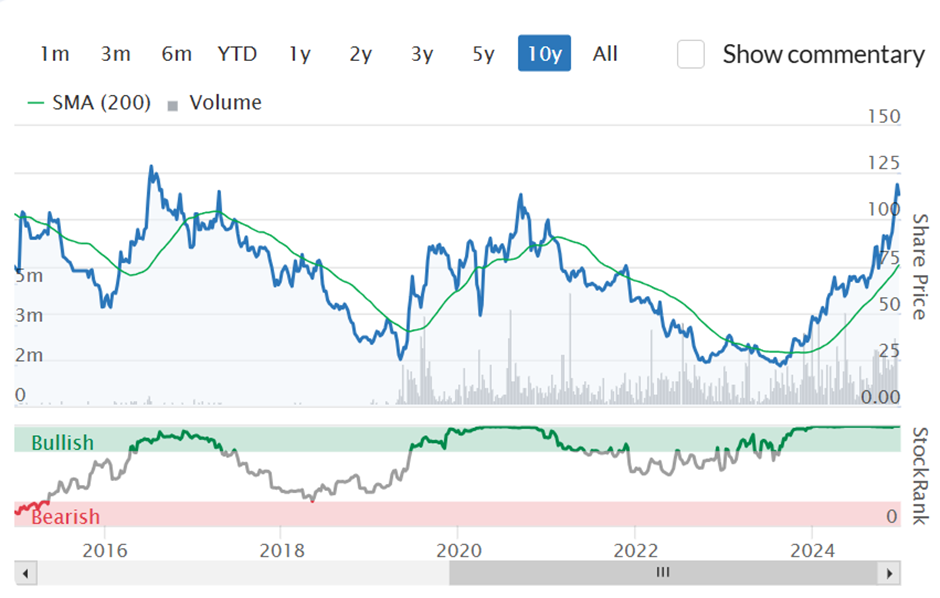
Serabi had a phenomenal 2024, with its share price rising over 150%:

Unlike many shares in 2024, this has been backed by earnings upgrades:
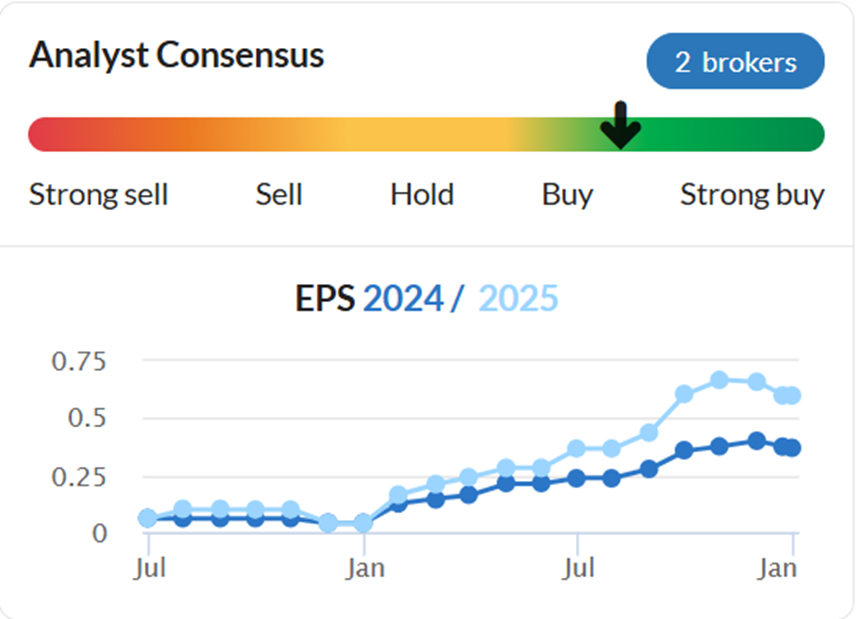
Indeed, this has made the forward P/E look incredibly low:

The major driver of this has been the gold price, which has risen 27% in Sterling in 2024. The cash flow generated from production at high gold prices means that they now have net cash. This momentum in earnings upgrades means the company has a 94 momentum rank and the highest StockRank in the UK market at the moment:

This isn’t just a story of leveraged gold price exposure. There is increasing production from their Coringa project planned:

This step change is driven by the recent commissioning of an ore sorter at Coringa. The idea is simple; if they can sort the ore, they can only process high-grade material, which has much better economics:

This means that trucking the ore some 200km to the processing plant at their main operation at Palito is more economical. Indeed, this has decent planned economics at current gold prices:

With 11 years of mine life, this will add to the plant economics for some time yet.
The risks here are largely self-evident:
- The rise here has been at least partly due to the rise in gold price. If this drops, the share price would likely follow.
- Resource companies operate at the behest of their host countries. There has been an increasing demand from some countries to share in the increased profitability coming from a higher gold price beyond regular taxation. With operations in a single country, there is little Serabi can do to hedge this risk.
- The company currently pays no dividend, and intends to reinvest its current profits into adding to reserves and exploring wider gold mining opportunities in Brazil. They may have great opportunities, but the reality is most gold companies overinvest in times of gold price strength. Long-suffering shareholders may prefer just to receive a dividend.
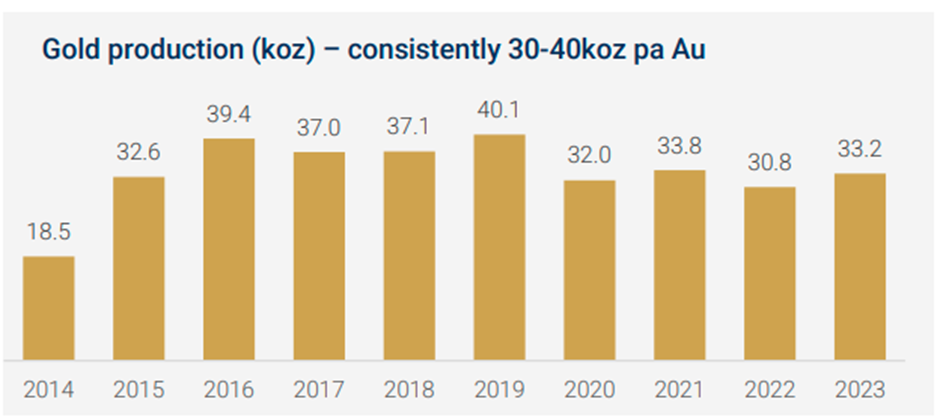
- The company doesn’t really have a particularly impressive long-term record. Production in 2023 was flat on 2015:
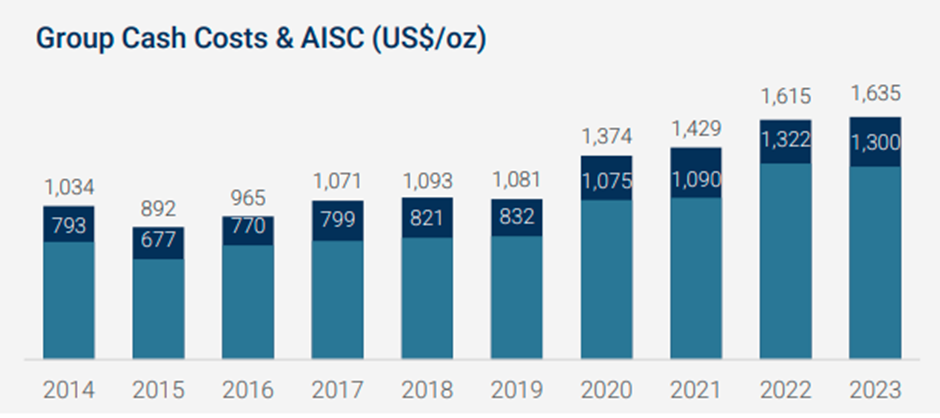
And during that time, cost per ounce has almost doubled:
The 10-year chart reflects this long-term mediocrity:
Probably none of this matters, given the production growth and very low rating. The price and fundamental momentum suggest the share price has much further to go in 2025. However, history suggests investors will want to be quick to exit when either the gold price or the momentum fades.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

3 comments
It's also worth pointing out that the Brazilian R$ has never been this cheap against GBP or USD. Measured against spot gold, things look even worse for the R$. Good news for Serabi with their various R$ costs however.
Good article, but one risk that’s not mentioned is that the Coringa mine is currently still operating under a Trial Licence (last renewed Jan 2024 for 3 years). There’s no obvious reason why a full licence won’t be granted in due course, but this does add some uncertainty regarding future revenues. In saying this, I’m also very bullish on gold and silver, and have held SRB through most of the recent rise (32p to 98p). I don’t currently hold as now see more value in MTL, ALTN and HOC, but I’m tempted to buy back in a bit if the price/RSI retraces.
As you say a growing rise in the value of gold as the age old currency of choice to harbour reserves globally. Helped perhaps, by a reluctance to trust US dollars with Trump and his liking for cryptocurrency. The rise of Serabi has been remarkable and may well bear some watching, but MTL are also performing well and miners looking for copper will not disappoint in the near future either.