12 Stocks of Christmas: Water Intelligence

For my contributions to the 12 Stocks of Christmas, I am choosing four stocks that epitomise Quality, Value, Momentum and Growth for me. Finally, it is the turn of Growth.
On the 11th Day of Christmas, my true love gave to me:
Water Intelligence (LON:WATR)
Water Intelligence is both an operator and a franchisor of minimally invasive leak detection systems for water pipes. Demand for their services has grown strongly in the last five years:
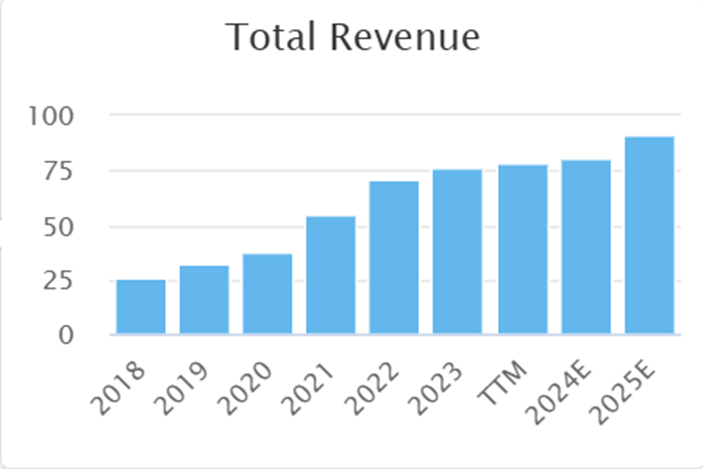
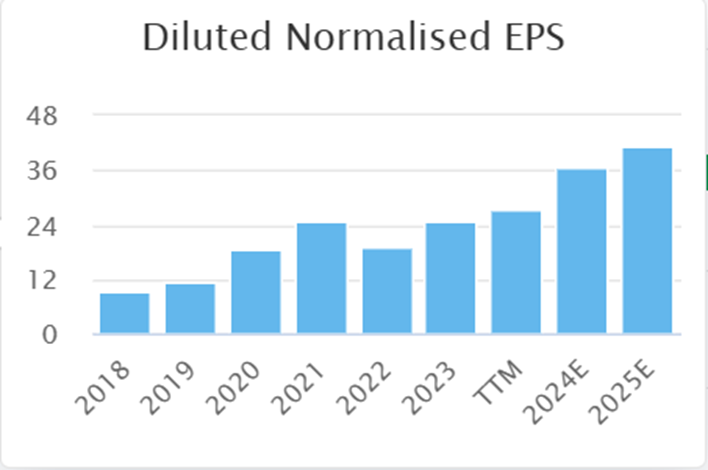
Over the last 10 years, their sales have risen tenfold, making it one of the fastest growers on the UK market. The 5-year sales growth works out to be 24% CAGR. However, despite a high gross margin, there hasn't been any sign of operational gearing. The 5-year CAGR here is still impressive at 22%, and EPS growth is forecast to accelerate, growing 48% year on year:
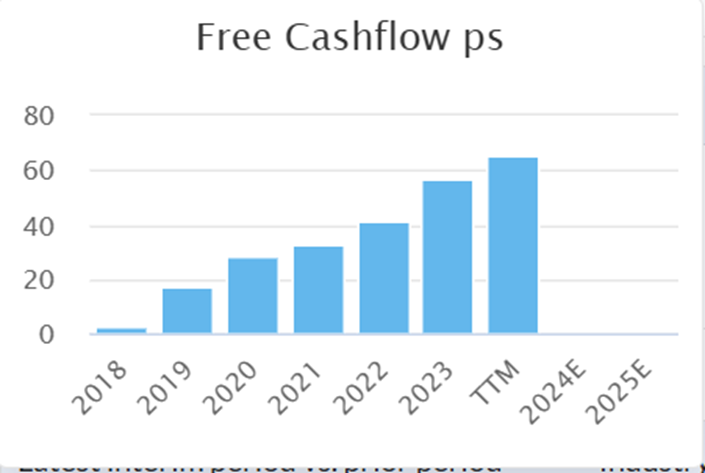
As you would expect from a franchisor model, growth has been cash-generative:
However, Returns on Equity are below what you’d expect for such a business, leading to questions as to whether this growth has added shareholder value:
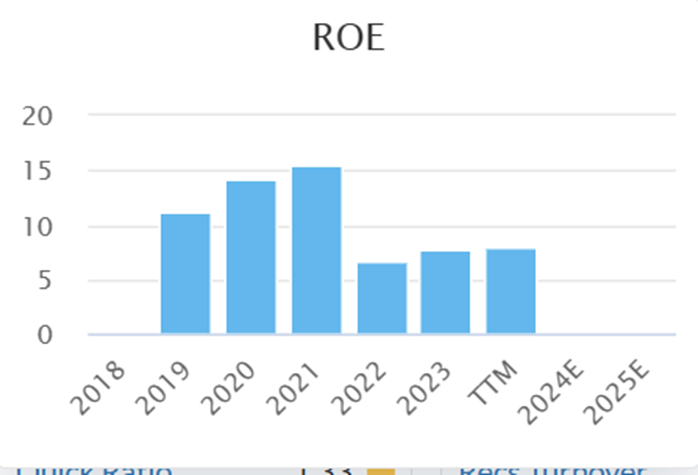
The low ROE comes about from a step change in Book Value in 2021:
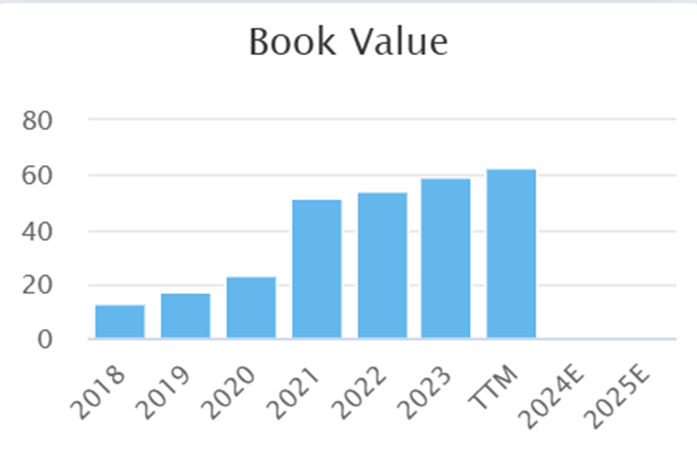
In addition to minor international acquisitions, the company has been using all its cash plus money raised from the market to acquire its franchisees. So, the increase in book value is primarily the goodwill from these transactions. The reality is that this appears to have largely moved away from the capital-light franchisee model in favour of greater control over the business. This has made it an excellent growth business, but perhaps not a quality compounder due to its low ROE and lack of operational gearing.
No dividends have been paid, but a share buyback program has been initiated at the end of 2024. However, the share count has still risen over the last five years since there has been dilution from options exercise, and they raised £16.2m from the market in 2021.
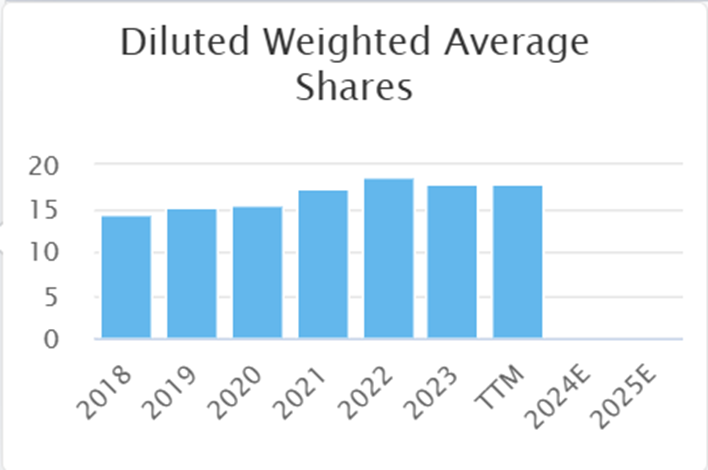
At least they had the good sense to do this at 960p and then 1200p, when investors were (overly?) excited by the prospects here.
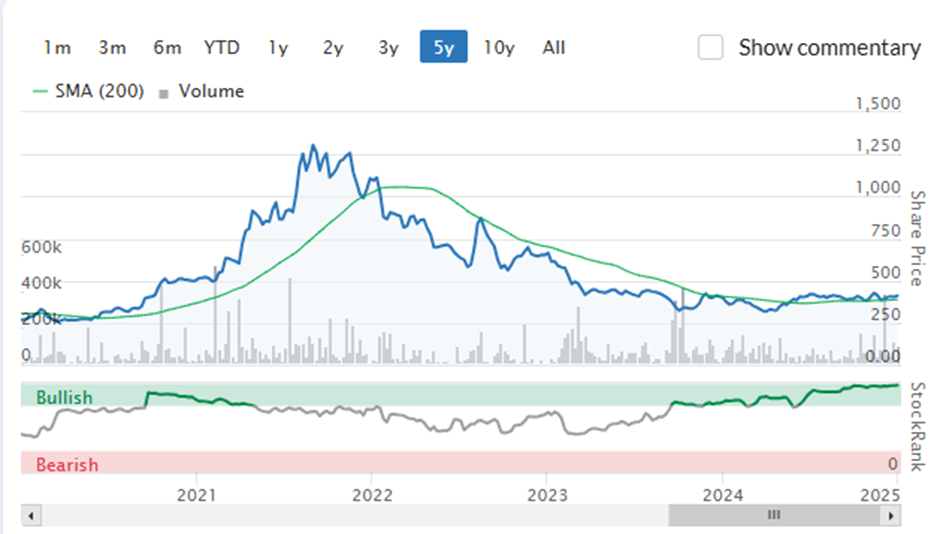
There are some questions about the strategy. The company seems to have a habit of franchising its operations but then buying back the franchise. This may be a low-risk way of expanding into areas, but it is hard for independent investors to gauge how good a deal the company is getting when negotiating these types of deals. Investors need to trust management are always acting in good faith regarding transactions such as this. The Chairman’s significant holding should at least maintain a significant alignment of interests.
These concerns are probably irrelevant if the company keeps up with the forecast growth rates, as the current forward P/E of 14 will quickly enter single digits if these growth rates continue. If they stop acquiring, the free cash flow will enable them to buy back shares or pay generous dividends. The overall StockRank is pretty good despite the Value Rank being average:
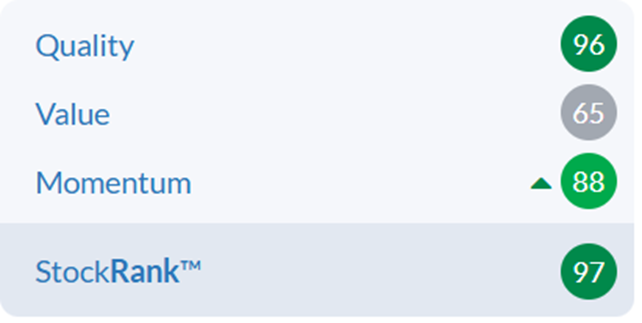
The Momentum Rank is surprisingly strong for a company with mediocre 1-year returns:
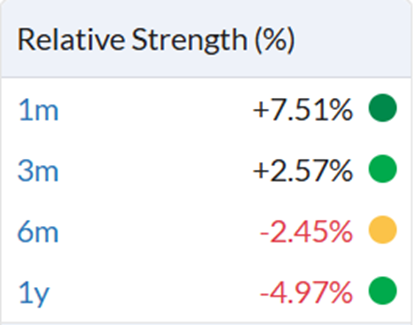
Instead, this is driven by some recent broker upgrades that don’t appear to have been reflected in the share price yet:
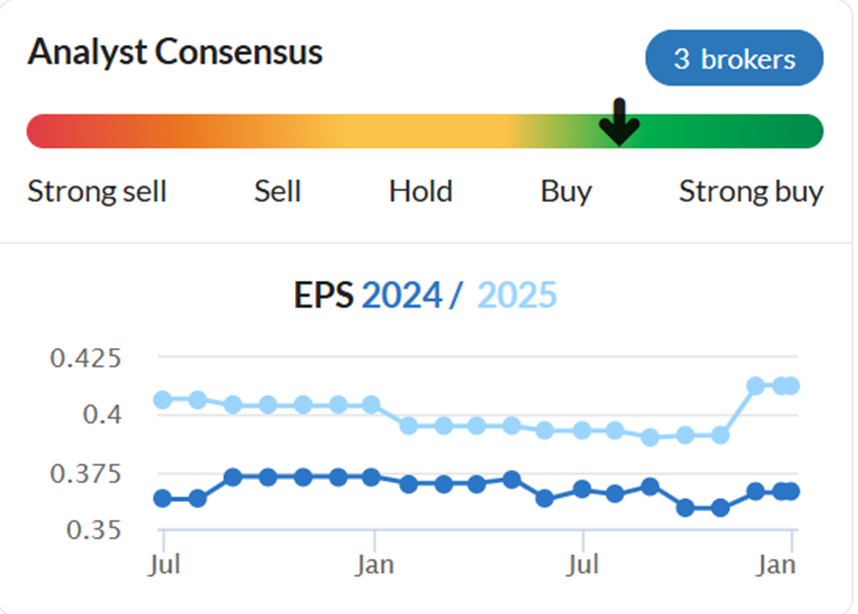
That in itself could present an opportunity for 2025, and there is always a chance that this is the year that shareholders fall in love with this stock again!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

9 comments
Price breakout of $440 then maybe some tailwind. Leak detection and repair is an essential service but perhaps the responsibility of the Utility Cos. Moats an all.
I think you'll find that the water co's are only responsible for what's out in the street - once it passes your stop-tap it is the home/office owners issue - and that's about 30% of all leakage.
Most modern toilets nowadays (the push button types) leak a small amount and underfloor leaks are common across houses - I had one that increased my consumption by about a 1/3rd until I had it fixed and I never knew about it - the leak was below a concrete floor and all the water headed south so there was no visible sign.
Looking at their website they are obviously looking at large offices/factories as a target and playing on the cost impact of major bursts as well as the day-to-day consumption costs from leaking systems and the efficiencies they could deliver.
Like gas & electric there is a big demand for efficiency savings in these areas and the opportunities are huge.
I don't own the share as I don't like the numbers, but the opportunity for growth is definitely there.
Water Intelligence (LON:WATR)
Other than that I’m instantly distrustful of foreign companies listing on UK markets when they have a strong home market as an alternative, I have very much derived the impression with this company that it is run for the benefit of management and with scant regard for external shareholders. The balance sheet is stuffed with goodwill and that results in a big discrepancy between reported profits and EBITDA, artificially boosting the valuation, while the company is an inconsistent generator of free cash flow. That said, the multiple looks more attractive than it has in a long while. I’m just not sure it’s a particularly high quality company.
The problem with the US market, is anything under $1bn, has very little coverage, even some around $8bn, have few analysts reviewing. Maybe that is the reason for listing here? Somero Enterprises (LON:SOM) is another of course.
I doubt it’s to access analyst coverage. That comes at the cost of a serious liquidity shortfall. Hardly ideal for a management team that is always looking to cash out their stake, as, to be fair, most are!
My point was, small caps on the US markets, will get little interest with investors. Why bother with $100m mcap, when you can buy shares such as NVIDIA (NSQ:NVDA) which can 10 bag in a short time. Large caps in the US di gallop. Seems very little interest in small cals there, unlike the UK market.
P. J. Desouza holds about 28%, last sale was over 3 years ago. Maybe he will selling some more soon? Seems to have picked up 14% since the last sale.
Not bad about 5% per year, presume all free?
Water Intelligence (LON:WATR) In 2006 ALD [which is the essence of WATR] was acquired by ALDHC, which is 92% owned by Plain Sight Systems, Patrick DeSouza, Stan Berenbaum and certain other individuals. Plain Sight Systems owns 14% of WATR on top of DeSouza's 28%
ALDHC owns Qonnectis Plc which was renamed Water Intelligence Plc in July 2010 [see note 21 of the 2023 accounts]. I think you need to be an accountant with a wet towel on your forehead to understand the "reverse takeover" and presentation of the figures in these accounts, which appear to be those of ALDHC.
It therefore appears that Plain Sight owns ALDHC, which owns both ALD and WATR. I couldn't understand how Plain Sight is credited with 13.99% of WATR, and I gave up trying to understand what I'd be investing in and who controls it. Certainly 75% of the shares are held by the top holders, so WE only have a minority interest.
I also read seeming reservations in Mark Simpson's write up, and BnB may be right. Anyway this isn't an investment for me
My xmas stock selection ...
Macfarlane (LON:MACF) 109p It's a stock that's gone sideways for the last 5 years whilst its EPS growth around that time has been 11% pa. It's on a PE of 8.8, a P/FCF of 6.9, a dividend yield of 3.6% and EV/EBITDA of 6. ROE over the last 5 years has been a decent 14.5%. Interest cover is 9.7, which is pretty safe.
I hold.
Unloved and un-sexy is that the reason for the 'link', whilst we are all saving up for Starlink IPO or nuclear fuel pellets.