12 Stocks of Christmas: IG Design

For my contributions to the 12 Stocks of Christmas, I am choosing four stocks that epitomise Quality, Value, Momentum and Growth for me. I’m starting with Value:
On the 8th Day of Christmas, my true love gave to me:
IG Design (LON:IGR)
It is apt that IG Design is one of my Christmas stocks as they design and manufacture a huge number of Christmas products. Greetings Cards, Gift Bags & Boxes, Gift Wrap, Gift Tags, Accessories, Crackers, Partyware, Decorations, Santa Shop, Christmas Fun, Stationary Essentials, Santa’s Grotto and Christmas Display Solutions are just the category headings in their UK Christmas 2025 Catalogue. They are not all about Christmas, but even their non-seasonal products, such as Frames & Albums, Calendars & Diaries, and Kids Create, will have highly seasonal sales trends aligned with the same period.
IG Design has been on a bit of a rollercoaster ride in the last 10 years:
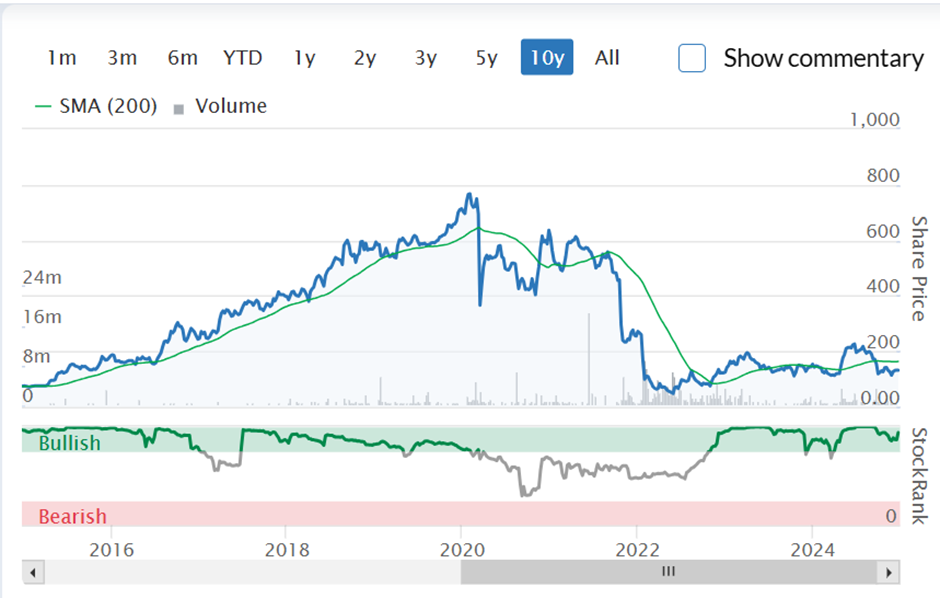
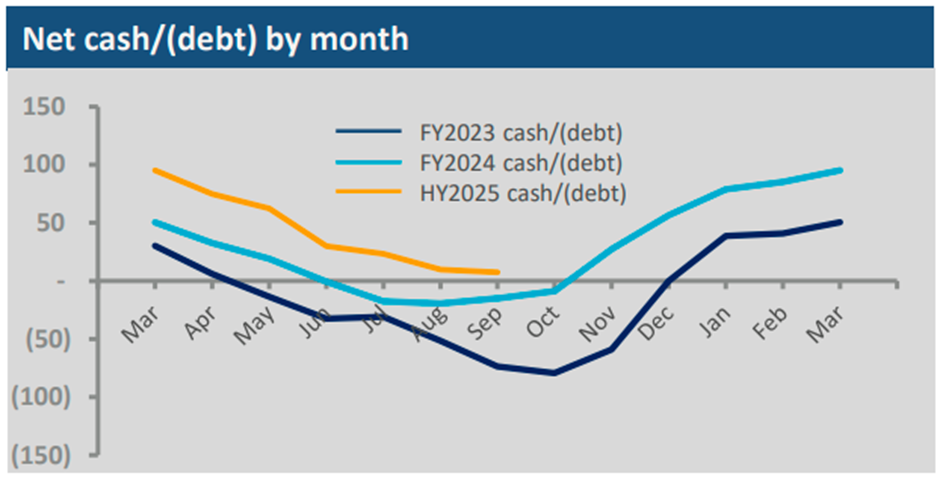
It 10-bagged from 2015-2020 as it pursued a growth strategy, but like many companies that prioritise sales growth above all else, it became unstuck. Partly, this was the impact of COVID-19, but then inflationary effects led to losses in 2022 and 2023. The company came close to insolvency in 2022, which seems strange for a company that regularly reports net cash. However, like many companies, the balance sheet date is carefully chosen and represents a seasonal high. The effect of having to order stock early and inflationary pressures meant that the working capital position put significant stress on the balance sheet.
While management changes are not always good for a struggling business, in this case, they appear to have been the catalyst for positive change. Paul Bal was appointed CFO on 1 May 2022 and was subsequently promoted to CEO on 1 April 2023. His focus on financial discipline can be seen in the net cash (debt) trajectory year-on-year:
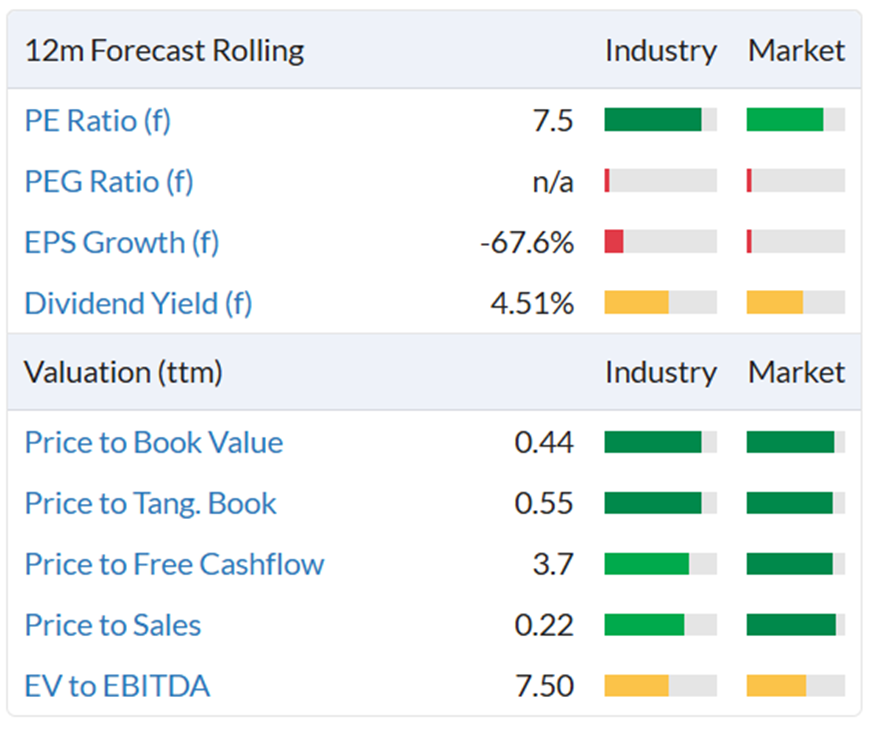
With solvency no longer in doubt, investors can focus on the valuation, which looks very cheap on many metrics:
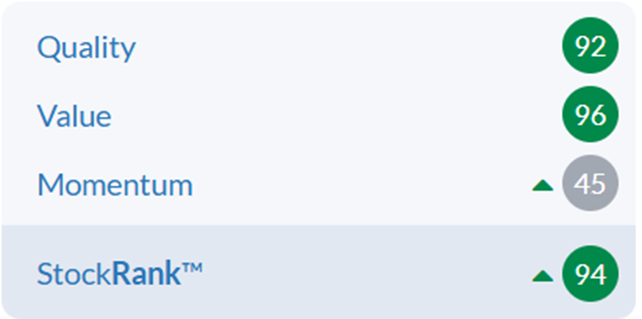
Leading to an impressive 96 Value Rank:
The key metric that makes this a value play for me is the 0.55xTBV. Most of this is inventory and receivables. Here are the values from the HY results to 30 September:


The company reports in dollars, so this is a net value of £208m at current FX rates, compared to a market cap of £130m. While there is a significant discount to liquid net assets, these are currently unproductive. However, there are signs that, after stabilising the balance sheet, the focus is now on improving profitability. EPS consensus is for 20.8c in FY25, putting them on a P/E of 8. The market still has some doubts over how achievable this is. After all, the EPS trend has been down until recently:
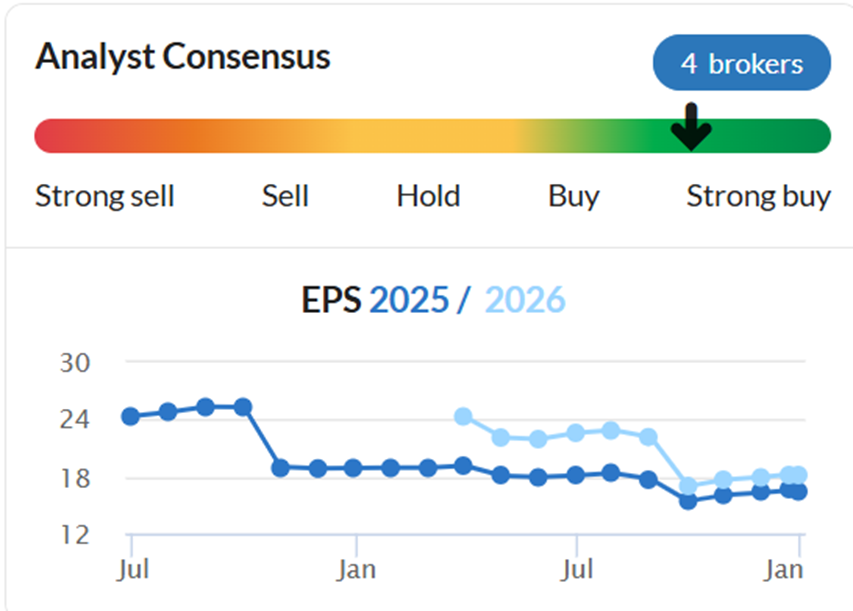
The Half-year results were initially received poorly, as they did 11.2c EPS in H1 this year versus 25c the previous year. This leaves a big H2 swing versus the previous year to hit those forecasts. However, there are specific reasons to think that they can meet expectations. In DG International, $2.1m of profit is due to delayed orders moving from H1 to H2. Plus, the lack of losses from China should also contribute to a $7.6m swing from H1 to H2. In DG Americas, they have had initiatives to drive increased operating profit totalling $9.4m. On top of this, in Q4 last year, they reduced deliveries to protect themselves from customers who were at risk of going into Chapter 11, and they don’t expect the same this year. All in all, they are confident that DG Americas will be profitable in H2. There will be exceptional costs associated with these changes, but these should be genuinely one-off.
At the end of the HY results presentation, they summarised the current situation as follows:
The first half was tough, and the retail environment was tough. Consumers were under pressure. It will pass. The strength of relationships with major retailers remains.
The current rating means any recovery will make the shares look very cheap. It is likely that even if the recovery doesn’t happen in 2025, the green shoots will be visible by the end of the year. If that happens, it will be included in analysts’ forecasts and priced by the market. Even a modest premium to TBV would see the share price double from here. There could be more to come when any medium-term cyclical recovery appears in consumer retail.
[Note: this article was written with the share price around £1.30. While a rise in price since then may change some of the metrics, the fundamental thesis is largely unaffected.]
[Disclosure: Mark owns shares in IG Design (LON:IGR) ]
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

5 comments
For the super brave - an opportunity to pick up some cheap this morning! 55% down from yesterday on profit wipeout.
I suppose we should be pleased that this news didn't leak early with insiders getting out before the RNS? They are hit just as hard!
Ouch, the mother of profit warnings!
Yes, poor timing on this one! Here is what I said elsewhere about what has gone wrong:
Oh dear, this is a huge profits warning here.
DG Americas is again doing the damage with their 4th largest customer entering Chapter 11. Something management specifically said they didn’t expect this year. There’s still net cash, but also below expectations:
Progressive has this at $63.4m at the year end. And, of course, the huge discount to net current assets remains. But the timeframe for these becoming productive is now kicked into the unknown:
Management credibility has taken a huge hit here. After all, less than a month ago, they gave a number of very specific reasons why they expected DG Americas profitability to recover in H2. The reality has been far from that and means they’ve pretty much gone from hero to zero in one step.
However, the 60%+ fall this week also looks overdone. Even with write-downs from one of their customers entering Chapter 11, the discount to Tangible Book Value is huge. Indeed, the expected cash balance at year-end covers almost 90% of the current market cap. The market is pricing this as if their receivables and inventory are largely worthless. This may be the case, but it seems far from the central outcome we should be using. The shares are trading not far off the level when the company was facing the real risk of insolvency, something that is no longer the case today. It will be a long wait for any recovery, though. With management credibility shot, the market will no longer value this on forecasts but will want to see profitability over an extended period before believing that DG Americas has actually been turned around.
Yes - extremely bad luck Mark. BTW, what are you now planning to do - Buy more, Hold or cut & run?
FYI, Party City seem to have been the US retailer that filed for chapter 11 bankruptcy protection - triggering #IGR's profit warning on Friday and write-off $15m in receivables.
It was flagged in the UK press here on the 23rd Dec.
https://www.dailymail.co.uk/yourmoney/store-closures/article-14222669/party-city-bankruptcy-huge-twist-worthless-tat.html
https://www.theguardian.com/business/2024/dec/20/party-city-closes
https://www.ft.com/content/ac3c1e2f-c9bc-417e-a686-7170e1bf8533
Hi Paul,
Personally, I am happy to average down so I have been adding. My logic was that the risk wasn't materially changed by this update, but the near-term outlook is more uncertain, which would normally mean a reduction in position size. However, the upside if these assets can be made productive again is now much higher. Overall, this means my position size should be similar. However, a 60% fall in price makes me underweight. This doesn't have characteristics that would mean I refuse to average down i.e. obsolescence risk or excessive gearing, and my at-cost weighting in the stock was not too high, so it made sense to add on the fall.
This is obviously a function of my unique personality and strategy, and I can see why other investors would take the opposite tack.
Cheers,
Mark