#2 - MP Evans - a different type of farm

This is #2 in our "Twelve Stocks of Christmas 2025" Series. You can review the full set here.
The Pitch
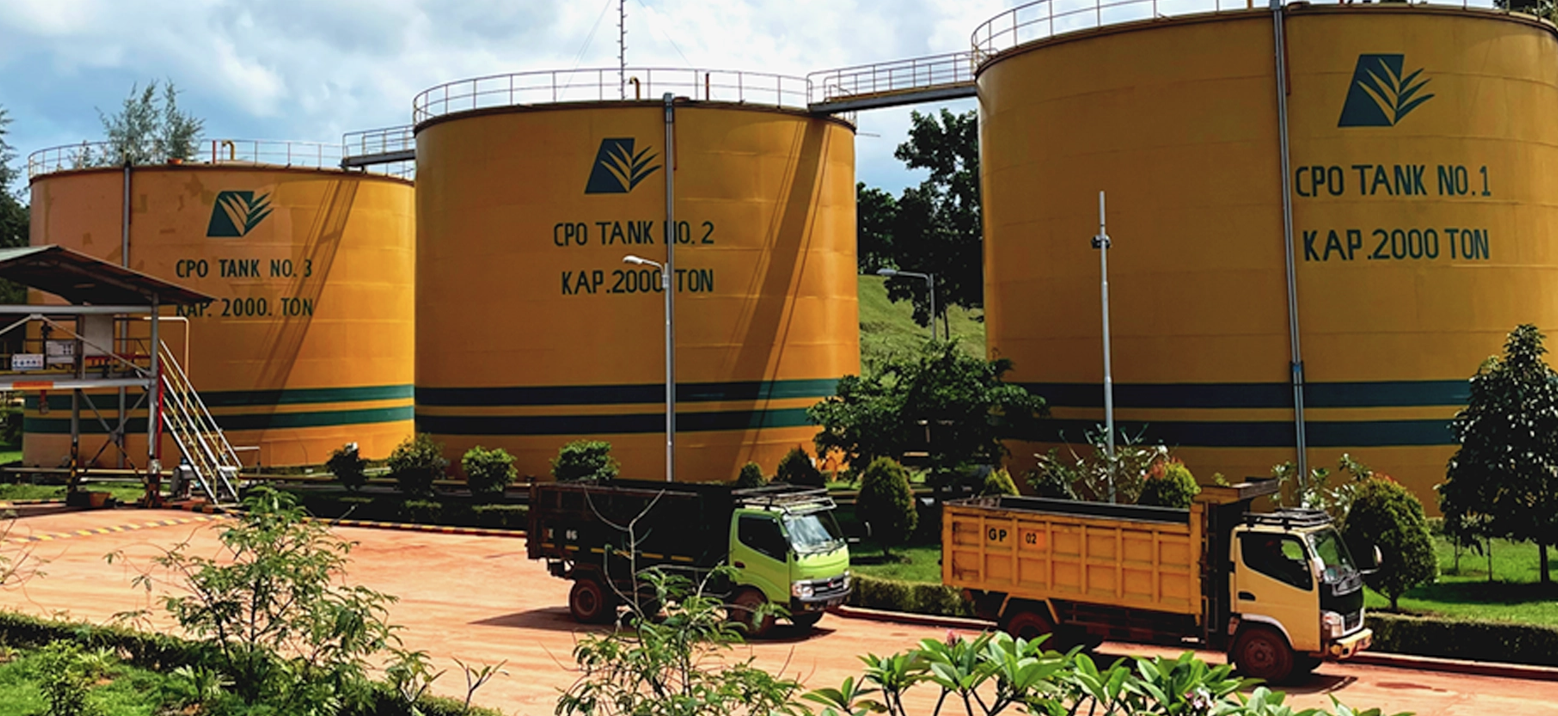
M P Evans (LON:MPE) is a producer of Indonesian palm oil, managing 66,000 hectares and six palm-oil mills. The business has existed in various forms for 150 years, and for much of that period was involved in the rubber trade, but it began shifting to palm oil in the 1970s.
Palm oil has a wide variety of commercial applications and is said to be used in over 50% of supermarket products.
The company has benefited this year from prices of $869/tonne for crude palm oil, compared to an average of $823 in 2024. Earnings forecasts have been upgraded on multiple occasions this year (most recently in November) and the share price has been strong, but the stock still passes multiple screens for value.
The Big Picture
MP Evans is a very old name on the London stock market, having listed originally in 1981 (before it was fully focused on palm oil).
Family involvement: Chairman Peter Hadsley-Chaplin is not related to the Evans family but he is a 4% shareholder and the son of Edwin Hadsley-Chaplin. Edwin spent over 50 years with MP Evans, starting in 1947.
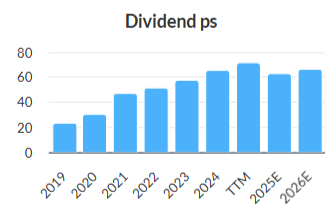
A dividend champion: this rich history means that MP Evans, while not being a family-run business, does carry an ethos of long-term stewardship on behalf of its shareholders. It has paid dividends every year for as long as I can find records, which is for multiple decades, and the general progression of these dividends has been very positive.
Going Deeper
Two core activities: the company has a twin model of production and harvesting. When it comes to harvesting, 3rd party crop is bought in to ensure full capacity utilisation at the company’s mills. Surplus amounts can also be sent to external mills where necessary.
Focusing on its own production: In 2025, this flexibility allowed the company to dramatically reduce the quantity of 3rd party crop bought in, which it says is “considerably more expensive than harvested crop, and is often of a much poorer quality”.
The combination of harvesting more of its own crop (up 8% at the interim results), which inherently has higher margins than 3rd party crop, along with higher palm oil prices, created a 50% surge in operating profit in H1. This was despite total harvested production falling by 3%.
What The Brokers Say
Singer Capital Markets describes MPE as a “palm oil producer with a vertically integrated, low-cost model in Indonesia and a strong track record of delivering record revenues, cash flow and progressive dividends". They say MPE has “industry-leading ESG credentials” and “is positioned to generate resilient income and sustainable growth”.
EPS forecasts: Looking ahead, they forecast adjusted EPS of 209p in the current year, before dropping back to 188p in 2026 and 167.6p in 2027.
To get there, the key assumption is that the crude palm oil benchmark price in Rotterdam will fall from $1,100 in FY25 to $1,050 in FY26 and then $1,015 in FY27. [Important to note that the Rotterdam benchmark doesn’t perfectly align with the price in Indonesia.]
Strong balance sheet: Singers further anticipates that MPE’s net cash will improve from $79m (Dec 2025) to $142m (2026) and then $193m (2027), although I expect MPE to invest more of its cash for growth rather than letting it grow so large.
The Bear Case
Crude palm oil price: as an agricultural stock, the major risk faced is the commodity price of palm oil and palm kernels. MPE has no control over this but it does at least benefit from having its own high-margin production with a 33% operating profit margin achieved at current prices.
Political risk: a new State-owned palm oil company in Indonesia now has 17 mills and plans to have dozens more. This comes after the Indonesian government seized vast amounts of land from illegal operators and handed down enormous fines to companies that it said were corrupt. While there is no suggestion that MP Evans is in any way impacted by or associated with these events, it’s always worth bearing in mind that there are special risks whenever we invest in foreign jurisdictions.
The Bottom Line
As I type this, MPE is trading at a share price of £12 ($16.14), which puts it on a PER of 10x for 2027 earnings. I acknowledge that there’s a wide range of uncertainty, depending on whether the CPO price falls by more or less than forecast.
But this is a stock that offers something a little different compared to the usual London-listed midcaps, and I think its history and heritage prove that it is worthy of our consideration.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

19 comments
Seems Oil is an essential commodity.
For cooking, heating, engines, shampoo etc etc. Vegetable or mineral both have adv/disadv.
It's not going away - world population grows then demand is not reducing. Everyone wants a better life.
Coal is making a resurgence - Thungela Resources (LON:TGA) and Platinum Sylvania Platinum (LON:SLP) Tharisa (LON:THS) - so the ESG / Net Zero tide is turning to common sense.
2026 for me is commodities - hard to get (supply constraint) with demand expanding = price rises. We can hope for a more together world and clever politicians but just turns into socialism and 1984 so no hope.
I will never buy a palm oil producer though I surely consume enough of the ruddy stuff. A destroyer of fertile forest, animal habit and human dwelling.
Please google Sumatra floods.
Last month 3000 people died .
Palm oil plantations massively over developed on Sumatra were a very major contributor as well as Nickel / rare earth mining.
I have a business in Indonesia with reclaimed and salvaged woods and have been actively involved in the rescue / aid operation in Sumatra in both fund raising and sending some employees from our town to support the effort , 21 off whom died as a result of secondary flooding.
The palm oil producers and the ministers that granted the licenses on such a colossal scale are all in the firing line for contributing to the catastrophe .
Firstly there was very little support from producers post the event they were nowhere to be seen which is just not acceptable.
Secondly the main cause for the huge death toll was not only the huge surge of water cased by the "run off" of water from the plantations, but more deadly the hundreds of thousands of logs / timbers that they had chopped down and not cleared, you can see the devastation on YouTube which really any shareholder should at least take the time to see.
These timbers were swept up by the water sending a deadly flood containing tens of thousands of trees that were cut by the plantations (should have been removed)
All hell has broken loose in Indonesia with 3000 dead and an island oblierated by a stupid government selling its soul with palm oil licenses and palm oil producers and rare earth miners raping a country of its resources but not putting in place correct practices to clear timber .
Very high chance of fines and maybe the previous top tier of ministers will go to prison (so they should)
It's a very very sad case of environmental destruction and greed.
3000 dead in Sumatra, trust me the people of Indonesia are devastated by our greed and holders of palm oil shares need to really look into this situation .
The situation is repeated in "the rape of Sulawesi" which is being destroyed with loss of habitat, poisoned river ways, displaced tribes, orangutangs starving, due to the clamour by the west for Nickel .
9 billion "invested" in a "strategic partnership" so we can drain an island of its nickel "to secure our nickel" supplies to build our EV so we can all drive round in our stupid EV patting ourselves on the backs that we are "net zero" at the expense of the destruction of beautiful Sulawesi .
And yes - the 9 billion comes from the UK proudly supported by our government .
You could not make this up
"The UK and Indonesia signed a Strategic Partnership in Sept 2024, with UK Minister Anneliese Dodds focusing on responsible nickel mining, ESG, and supply chains, despite concerns over environmental damage in Sulawesi/West Papua from the EV nickel rush. While supporting sustainable practices and a $9bn UK consortium investment (Glencore, Umicore) in Indonesia's nickel industry (incl. Sulawesi), the UK faces scrutiny for potential "green colonialism," balancing clean energy goals with local impacts like deforestation and pollution."
Sometimes I hate being British and we are vacuous and morally bankrupt in our self deluded perception of our role in the world.
I don't hold MP Evans .
This has indeed been a disaster - M P Evans (LON:MPE) issued the following earlier this month
FLOODING IN INDONESIA
Following a particularly severe cyclone in the region, the island of Sumatra in Indonesia has experienced significant flooding in several regions, particularly Aceh and North Sumatra.
The Group has estates in both Aceh and North Sumatra and, whilst the North Sumatran estates have been unaffected, the Simpang Kiri estate in Aceh has experienced some flooding. All the Group's workers have remained safe throughout this time. However, operations at the estate have been temporarily disrupted. The flood waters have now subsided, and normal operations will be resumed in the coming weeks. The flooding will not have a material impact on the Group's crop and production for the year.
The Group is providing support where possible to those affected in the local community around its estate, and its thoughts are with those who have suffered greater losses during this difficult time. Our condolences go to the families of those who have died in the flooding.
M P Evans (LON:MPE) It is a good diversifier. Adding another bank or tech company to a portfolio doesn't reduce risk very much, but this company is in a radically different industry and location.
Obviously it has a number of risks but the point is that these risks are different to those of most other companies.
Surprisingly, no reference to one of the differentiating factors versus other companies in this field. I quote from their own statement -'M.P. Evans Group PLC is a United Kingdom-based company, which is a producer of sustainable Indonesian palm oil' Sustainable means what specifically? Other companies are unsustainable? Presumably they chop down even more rain forest - tho little left - abandon the useless land, and replant on new land.....and so on. A sort of slash and burn, without the burn? What say you Graham, and where does AEP Plantations (LON:AEP) fit into all this?
Hi ridavies! It's an agricultural stock so I don't expect massive differentiation against other companies. At the end of the day it's a price-taker. But in their marketing literature they do emphasise sustainability, and they are a member of the Roundtable on Sustainable Palm Oil:
Link
i hold:
MPE has achieved a significant increase in operating profit despite slightly lower total volumes by processing more of its own palm fruit and reducing bought in fruit. Helped by purchasing 3,000 hectares adjacent to existing mills
It has paid back all debt - strong balance sheet.
Indonesia’s B40/B50 biodiesel mandates ( where the govt plans to use local palm oil for biofuels)creates a domestic demand "sink." This provides some protection to MPE from global price volatility .
MP Evans (I hold). I understand that governments of Indonesia and India have major bio fuel programmes in which palm oil (partially) replaces mineral oil, and India is the world's largets importer of palm oil. These programmes largely underwrite demand for, and the price of, palm oil, There are, of course, many other products which palm oil, and it is widely used as the cheapest cooking oil in Asia and Africa, Others better informed than me may be able to elaborate further,
I remain a confident holder of MP Evans and also AEP Plantations (until recently Anglo-Eastern Plantations).
Richard
The soil degradation caused by the mass plantation of palm trees has caused flooding on a catastrophic level with significant loss of life. Many of these plantations are owned by companies based in offshore tax havens so the wealth generated does not flow to the local communities which are by any standard extremely poor.
I have travelled around Sumatra and been on one of these plantations. They use far more water than the previously farmed rubber trees and consequently not many other species live underneath them. The scale of these plantations is astounding. They go on and on for miles. Doubt very much the locals benefit from much of the wealth generated by these plantations. Most of the original rainforest has gone now. Very sad.
Sumatra is twice the size of the entire UK. 80% of Sumatra has been destroyed to palm forests. Once it is used for palm oil production the soil is of such poor quality that it becomes no longer fit for any other crop.
I hold. It seems a classy operation, and seem to treat their employees well.
“industry-leading ESG credentials” Grr, I can't find it on their website offhand, but they have a certain accreditation which commands a premium oil price.
I also read somewhere that palm oil demand is increasing at a rate of about 7% pa. Don't quote me on that, though.
I recently learned that it is increasingly used in chocolate bars. It's cheaper than cocoa butter, and makes the chocolate more waxy. It's a controversial subject amongst consumers.
Worth checking out is the palm oil price chart https://tradingeconomics.com/c... . Very curious. Prior to 2020 (so around Covid time), prices were in the range 2000-3000, spiked up massively in 2022, but then fell back to a "new normal" of around 4000, where it sits today.
Will this "new normal" be sustained? Answers on a postcard on that; but it seems to be. Arguably the spectre of inflation will never disappear, so the price is unlikely to go down. Maybe, as a holder, I'm just fooling myself though.
If you believe that, then a PE of 10 and a P/FCF of 6.8 does not look demanding.
the 2022 price spike was caused by russia invading Ukraine. Ukraine is a major food oil supplier.
The European market increasingly demands certification of palm oil
This further explains why they are now processing a greater ppn of their own palm oil - it's also cost effective
And its Aim listed - qualifying for the 20% IHT relief
https://www.mpevans.co.uk/sust...
Thanks Mark, always enjoy reading your posts and appreciate your comments. Merry Christmas.
I do normally but sadly did not enjoy this post
Thanks for the write-up Graham - quite interesting and did make me go and look at their website to find out more.
I think it may have listed 100 years earlier than you have stated - probably just a typo.
Best wishes for 2026 - you and the team do a fantastic job and I find myself spending far too much time across the various boards, but yourselves and the various knowledgeable subscribers provide an extremely rich environment of ideas and thoughts. Thank you.
Hi Kevin, thanks for this nice comment back on Boxing Day! Very kind of you.
As for the age of this company, it is extremely old. In terms of when it first listed in London, this is my source:
https://www.mpevans.co.uk/abou...
Best wishes,
Graham