2023 investing mistakes
There is nothing special about another orbit of the Earth around the sun that makes it essential to measure investment performance. However, the end of a calendar year is a natural point for investors to take stock of their recent performance. Hence, this is the time of year when investors tend to publish portfolio reviews. This is something I feel torn about. On the one hand, I genuinely enjoy reading about other investors' progress or pitfalls. However, learning about other investors' performance can lead to several biases.
Investment Behavioural Biases
These biases are usually based on a form of myopia – an unduly short-term focus. A year is a relatively short period to test an investment strategy, and continually comparing short-term performance to other investors is unlikely to help bring Investment success. After a good year, investors may succumb to hubris and become overconfident. Merriam-Webster says that:
In classical Greek tragedy, hubris was often a fatal shortcoming that brought about the fall of the tragic hero. Typically, overconfidence led the hero to attempt to overstep the boundaries of human limitations and assume a godlike status, and the gods inevitably humbled the offender with a sharp reminder of his or her mortality.
Overconfidence often leads investors to be overweight positions, believing they know more about a company or industry than they actually do. This is a dangerous combination. The market gods are great at humbling those who succumb to investing hubris.
On the flip side, seeing others generate high returns in a poor year can lead investors to conclude that they should modify their investment strategy. If the underperformance lasts many years, a serious look into what has gone wrong may be required. However, if an investment strategy is based on sound principles, switching is more likely to cause future underperformance. There are at least three significant mistakes investors can make:
Mistake 1 - Missing the role that luck plays
Short-term investment results are a mix of both skill and luck. When an investor has excellent results but holds a few risky and illiquid stocks, the outcome is far more likely to have been due to luck than skill, particularly when one or two stocks are responsible for all the gains. While skill can persist, luck is likely to be mean reverting.
Mistake 2 - Having a different risk tolerance
The best investment strategy is one you can stick with. Investors can look at the overall results that other investors generate and often miss the path they took to get there. Having large stakes in pre-profit microcap stocks that have multi-bagged sounds great. However, this strategy would have been down at least 75% in early 2020. Few investors can cope with losing three-quarters of their investment pot in the space of a few months and still make rational decisions. Those who panicked and sold when the news looked grim in March 2020 probably never recovered from this draw-down.
Mistake 3 - Style shift
Many sectors are cyclical in performance. Investors who had significant direct gold exposure will have done well in 2023. Oil and gas investors, less so. Investors who favoured large caps will have done better than small caps. While there is nothing wrong with having a sector focus if an investor believes they have an edge in this space, shifting to last year's hot sector is likely to be a losing strategy.
The same principle applies to investors who choose to invest in funds. Many investors like to use long-term track records to pick funds. It seems to make logical sense; surely good managers remain good managers? However, S&P Global looks at the persistence of US fund manager performance every year and has never found evidence of persistence in long-term performance. For example, here is the proportion of funds that perform better than average over five years that subsequently still outperform in the following five years:
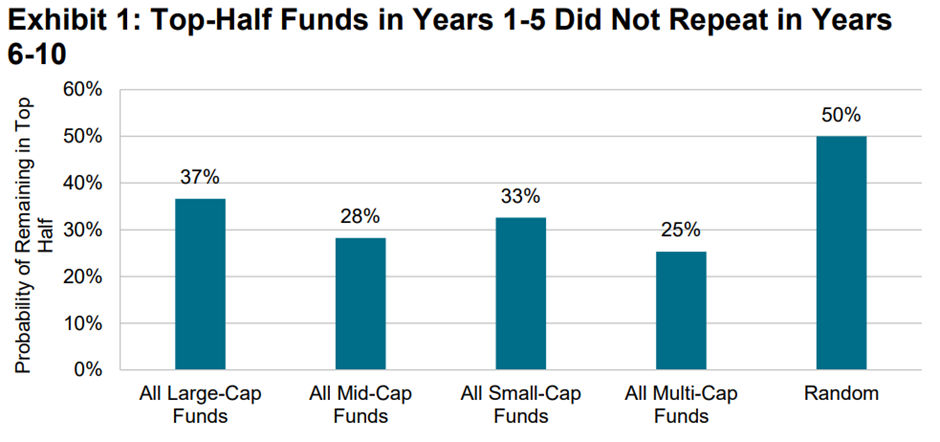
Top-performing fund managers are actually less likely to outperform in subsequent periods than they would be if it were pure chance. There may be many reasons for this, including growth in AUM eroding a successful manager's ability to invest how they would like. However, I would certainly expect that fads in successful investing styles play a big part in this mean-reversion. There is a reason that Warren Buffett talks so much about the importance of an inner scorecard. He would have had a significantly worse investment performance record if he had given in to external pressure from others and shifted to investing in tech stocks in 1999.
Closer to home, Buffett disciple Keith Ashworth-Lord's Buffettology Fund is a case in point. The fund had excellent results in the five years to the middle of 2021, trebling investors' money. However, since that point, the fund has underperformed. It has 4th Quartile performance over three years and has lost investors 15% since then:
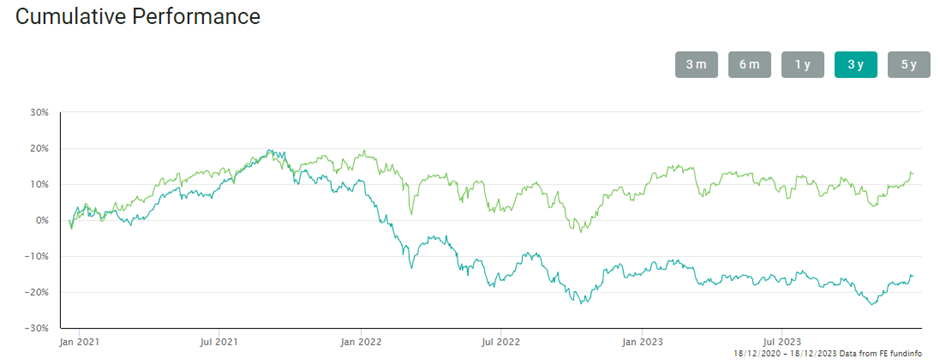
I would certainly question the wisdom of running a "never sell" portfolio in an open-ended fund structure. However, this is the same manager with the same strategy. It seems that mean reversion impacts almost everyone in the end.
Portfolio review?
If reading portfolio reviews has the potential to introduce biases, then writing one may be even worse. I know that a comparatively good year makes me hubristic, and a relatively bad one leads me to take more risk in the future. Yet, the process of reviewing performance can be a valuable learning experience. I square this circle by doing a portfolio review focussing only on my investing mistakes, attempting to learn from them.
So, what is an investment mistake? It may be tempting to think it is one where I lost money. However, this assumes that there is always a complete correlation between my investment process and the investment outcome. In reality, luck also plays a significant part in investment results, particularly over such a short period as a year. I find the following table from Michael Mauboussin a helpful way of thinking about this:
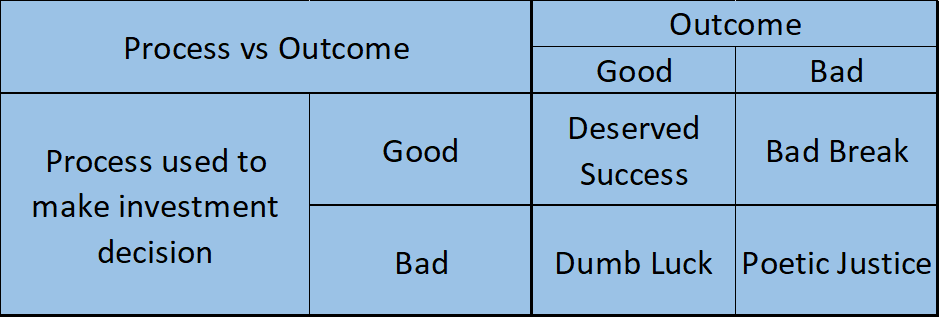
It can be hard to learn from instances of "Dumb Luck", where my process was bad, but I caught a lucky break. Likewise, a "Bad Break" may cause me to learn the wrong lessons and short-circuit potentially good processes due to a few specific instances when things didn't work out. So, I tend to focus on the times of "Poetic Justice", where things went wrong and I deserved it.
There are also two types of mistakes an investor can make: errors of commission and errors of omission. Errors in commission are where an investor took action to buy or sell a stock, which they shouldn't have done. Errors of omission are where they didn't take action and should have done. I'll start with errors of commission.
Errors of Commission
The best way to measure this is to look for stocks I sold that rose significantly. There are two that stand out:
SCS (LON:SCS)
I had held this share for several years, believing that the large cash pile would make it the ideal candidate to be taken over by Private Equity. I even joked with friends that if I had a spare £100m, I'd buy SCS, immediately return the cash I paid from their own cash holdings, load them with a similar debt structure to competitor DFS Furniture (LON:DFS), and tell management to get on with it. However, with an aggressive buyback in place, the cash balance somewhat depleted, and a looming consumer recession, I sold into the strength caused by the buyback. It seemed the right decision at the time, as the shares fell back when the buyback ended. However, given the current trend for takeovers, it was wrong to have sold my entire holding, as later in the year, an Italian trade buyer swooped for the company.
Vertu Motors (LON:VTU)
I have held this share on and off over the years. While I believed it was still undervalued, at the start of the year, I didn't think that the upside on the stock was as large as other opportunities, so I sold at around 55p per share. While some of this money went into stocks that did perform well, some also went into Cavendish Financial (LON:CAV) and Gulf Keystone Petroleum (LON:GKP) at much higher prices than they trade today. The thing I missed was that despite the upside not being huge, the certainty that there would be a positive outcome was high. This is because there were at least three keen buyers of the stock: two trade buyers and the company themselves via share buybacks.
In addition to these two, there is a stock I traded badly:
Zoo Digital (LON:ZOO)
This company has been severely affected by a lack of content production within the film and television industry, which itself was caused by a writers' and actors' strike in Hollywood. On top of this, their major customers were going through a process of streamlining suppliers, leading to a further hiatus of work being given to Zoo. These problems were temporary in nature, and since the company had raised money for an acquisition they didn't complete, they should have the capital to see them through this weak period. I bought shares at around a 60p average price, expecting an eventual recovery. The problem was that I bought ahead of a scheduled trading statement that I knew would be terrible. And when it was, the shares plummeted below 30p at one point. However, the size of my initial position and the weakness of trading meant that I wasn't willing to add at these levels. When the share price bounced back to around 50p, I sold for around a 20% loss. Only to see the Hollywood strikes end and the share price rise to almost 70p in response. In many ways, I was lucky not to have a worse outcome. However, the big mistake was really around position-sizing, being too aggressive with initial buys ahead of a trading statement I knew would be weak.
The flip side of this is identifying the stocks I purchased that subsequently show a significant loss. I don't keep detailed records of the P&L on individual buys. However, in many stocks, I bought too aggressively too soon. National World (LON:NWOR) , Cavendish Financial (LON:CAV) , and Jupiter 2nd Enhanced Inc (LON:JSE) are all stocks that I believe are materially undervalued, but I started buying, only to see them fall much further. In all cases, I have been able to average down. However, the size of the falls means I am still showing a loss overall on these positions. I am considering putting in some more formal rules for averaging down. This is problematic because I haven't analysed the impact of cases where an initial aggressive stance or average down paid off. However, a rule such as only allowing myself to average down after a stock has fallen a further 20% certainly feels like it may add value to my investing process.
Errors of Omission
This year has been a year to be nimble. Given the headwinds that small cap funds have faced with redemptions and the uncertainty around the economy that many individual investors have felt, few stocks have had sustained rises in share price. As such, this has been a market to top slice into strength. In general, I have been successful in doing this. However, I have not been aggressive enough. For example, I correctly judged Hummingbird Resources (LON:HUM) to be one of the most geared stocks to the price of gold and a stock that was widely hated by the market. This type of stock is at the limit of my normal risk tolerance and, understandably, is quite volatile, as the YTD chart shows:
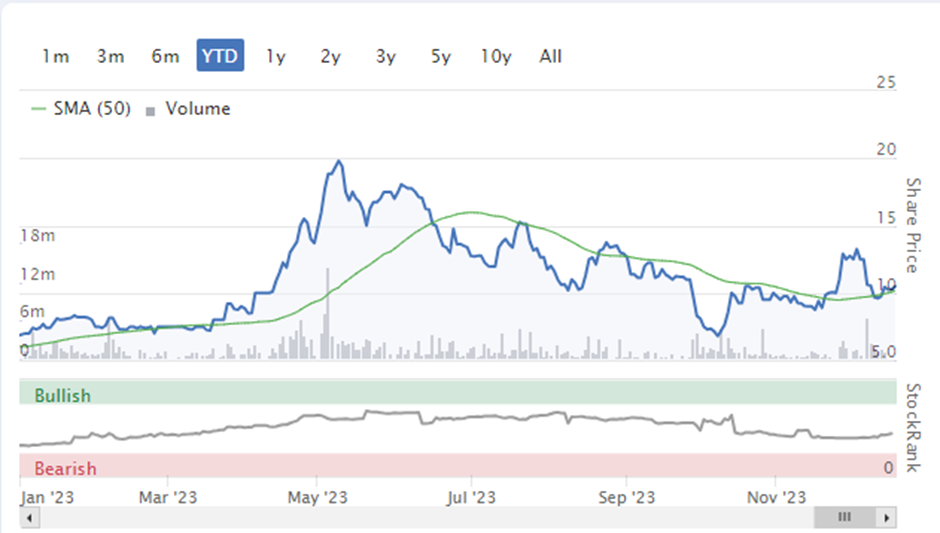
The stock started the year at around 7p per share, but subsequent gold price strength and a good couple of quarters of production meant the share price trebled to around 20p. I top-sliced around these levels, but not by enough. By October, the price was back below that of the start of the year and notably below the price of a strategic placing to their main lender that significantly de-risked the shares. Although this placing reduced the upside, this was never in doubt, so the risk-reward looked favourable to add again. The problem was not so much in the timing of my buys and sells but in the size. If I had been more aggressive in selling on the way up and buying on the way down, I would have done much better out of this volatility.
Finally, errors of omission would not be complete without considering shares that have done well but that I didn't purchase. In last week's article, I looked at the best-performing stocks of 2023, and it was clear that many of these are poor-quality speculative stocks that have done well because they have captured investors' imaginations rather than the underlying business performing well during the year. I don't regret not buying these, as these would have been an example where I would have had a poor process but a favourable outcome. I.e. any returns here would simply have been "dumb luck". After all, the average expensive, poor-quality stock did terribly in 2023.
There are a couple of examples in the list of companies that did well that I should have owned. The first is MS International (LON:MSI) , where it seems several defence contracts have turned around the future financial performance of the business. The second is cosmetics manufacturer Warpaint London (LON:W7L) , which has seen continual upgrades in forecasts during the year:
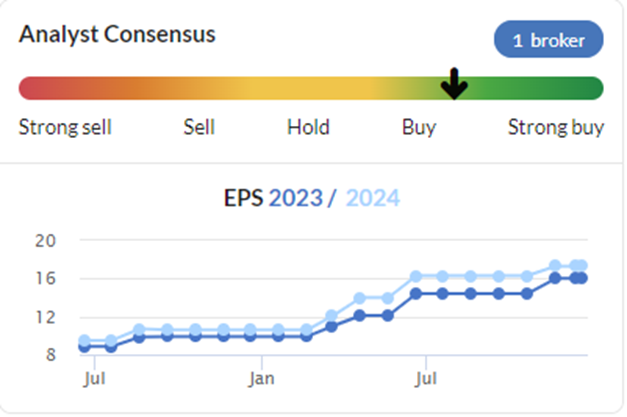
In both cases, I was too slow to change my mind when the facts changed. It actually counted against me that I had previously owned both stocks, so I knew the businesses already. With both companies, I was put off by the cyclical nature of their businesses. For MS International (LON:MSI) , there is a multi-decade history of management looking after themselves at the expense of minority shareholders. The quality of the contract wins suggests they finally have winning products and are capitalising on them to the level that other concerns may be insignificant. With Warpaint London (LON:W7L) , I struggled to believe that the same business, with the same management, could be so mediocre since listing in 2017 through to 2022 before hitting the sweet spot of profitable growth when so many other personal care businesses have struggled in 2023. But they have, and the signs that they were performing well early in the year that I missed. In both cases, I think the price is at least up with the current news flow, so I will not invest at current prices. However, these remain significant errors of omission in 2023. In 2024, I intend to look more closely for businesses that win prestigious contracts or companies that have started to perform after many years of struggling. In both cases, the market will likely have mispriced the stock's potential.
Overall, my biggest mistake was being too aggressive in my buying and too timid in my selling. This may be a function of the range-bound market for small caps in 2023. However, unless there are clear signs that 2024 is a significant bull market where buy and hold works best, I will aim to be more cautious in my buying and aggressive in my selling.
This type of exercise, looking at investment mistakes, can often yield insights for improving an investment process. I urge investors to give it a go, even if, like me, they are not big fans of doing portfolio reviews. And, of course, Stockopedia is a great environment in which to write these up and receive constructive feedback from other experienced investors.
Wishing everyone a mistake-free end to the year and a Happy Christmas!
[Disclosure: Mark owns shares in Cavendish Financial (LON:CAV) Hummingbird Resources (LON:HUM) Gulf Keystone Petroleum (LON:GKP) Jupiter 2nd Enhanced Inc (LON:JSE) NWOR VTU ]
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
8 comments
Dear Mark,
Any thoughts on your buy Luceco sell Zotefoams line of argument at the start of the year ? Are you still of this view both negative and positive be interested in an update.
Thanks tom
Hi Tom,
I replied to your question on the previous article, but looks like you may have missed it, so forgive me if I copy-paste most of the answer from there:
Basically, it comes down to the quality of the business. Do they consistently generate a return on capital above their cost of capital? With Luceco (LON:LUCE) they do, with Zotefoams (LON:ZTF) they don't. Yet, on valuation, you are paying 12x forward earnings for a business with a history of good economics and 19x forward earnings for a business with a history of bad economics.
The original call was not so much a buy and sell one (no one on Stockopedia is making these calls) but an observation that Luceco (LON:LUCE) surprisingly had many of the qualities that Buffett & Munger look for and Zotefoams (LON:ZTF) doesn't. (Specifically, it seems to fail the requirement to have consistent returns on capital in the region of 15% or higher.)
I get that Buffett & Munger isn't the only style of investing and that history isn't always a guide to the future. Although the current business appears to be low-quality, there is blue-sky potential with Zotefoams which may transform the economics in the future. However, if they had a history of generating innovative products that were actually profitable, then I'd be more willing to give them the benefit of the doubt over future products. Perhaps the recent retirement of the CEO will lead to better management with a greater focus on generating acceptable returns on capital. Paying a high multiple for unproven blue sky, or betting that a new management can fundamentally change a business that has been poor for many years, just isn't my style of investing. If you have a history of doing blue-sky investing better than me, then that's great, I wish you luck.
On the other thread, you asked about changing my mind, and that is a pertinent question for an article about analysing mistakes. In terms of changing my mind, I will certainly do so, if the underlying performance of the businesses and the valuation changes. If Luceco (LON:LUCE) ends up on a P/E of 20 with a few years of ROCE in single digits it will almost certainly be a sell. If Zotefoams (LON:ZTF) ends up on a forward P/E of 10 and manages to double its ROCE, then it will almost certainly be a buy. Price action alone will not change my mind since the short-term link between the two is shaky, at best. This is the heart of this article: the table on process versus outcome highlights that mistakes are made by a poor process, not just poor outcomes. This means that price action alone doesn't define a mistake. Speculation can take the value of shares far above fair value and despondency far below fair value. My aim is to do the opposite: buy the widely hated and sell what the crowd is most excited about. That's simply my preferred style, and it certainly isn't for everyone. So, it may yet prove to be a mistake for me not to own Zotefoams, but it will be one that is shown up by a rapid change in the performance of the underlying business, not price action.
Happy New Year!
Mark
Thank you Mark. I've now read this article a few times. Each time I find another bone to chew on. Maybe because your thinking seems to chime with mine in quite a few ways.
I like the way that you have kept it simple. It's a fundamental approach of many of the best stock-picking investors. But not the most celebrated. Tends to be in tension with the algorithm led approach of Stockopedia. That's not a criticism, just a fact. I benefit from both approaches, though I tend to place 'Keep It Simple (Stupid)' before Algorithms. Asking ChatGPT to suggest my mistakes is not going to be my favoured approach :-)
That a bad outcome is not necessarily a mistake. Conversely that a bad process does not always lead to a bad outcome has distracted me for a long time.
And how you have inverted (to borrow a Munger phrase). The best way for me to succeed is to stop making as many mistakes. Particularly big ones. I don’t need more successes. Just less mistakes. As a natural contrarian, I can take a lot of pain. I have confused a large fall in share price with a mistake. Being able to tell the difference is an important skill I’d like to learn a lot better!
It's amazing and humbling, just how long, how many years, decades even, I've been trying to learn these simple things. Sadly I'm a slow learner. Almost always from my own mistakes. And easily distracted by my successes with dumb luck! Which is dangerous for someone who tends to be in too much of a hurry.
The 'interesting times' of the last few years have proved particularly fertile ground for my continued learning! Not disastrous. I'm still here, still learning (I take living costs from my portfolio - so it does need to work), but I've made just about all the mistakes you describe in the last year or two. The absence of abundant dumb luck has helped make this much more clear to me, In the words of Warren Buffett, it's caught me swimming naked a couple of times.
I'll try to contribute something on my sins with particular companies once I've had time to think about it.
Please keep up the good work - I'd very much like more in the same vein when you are able,
Good luck - as well as great skill - to us all in the New Year,
regards
Mark (Allery) aka Illiswilgig
Has not been a good market, over the last 2 years, for averaging down, a stop loss strategy, would have worked better. Easy with hindsight, But the market will change again.
Great article as ever, definitely recognise some of these mistakes in my decisions. Fortunately I was too early to the party in some cases, but held on long enough to see the current upturn.
Thx Mark, loved your articles over the year and this in particular highlights a weakness with my own investment approach. I’m very analytical on my purchases and sales but tend to then box off the transactions (good and bad) and move on. A bit more retrospective analysis would definitely make me a better investor. I still hold Hummingbird Resources (LON:HUM) Vertu Motors (LON:VTU) and sold SCS (LON:SCS) prior to take over news(doh). Cavendish Financial (LON:CAV) seems an enigma to me given the glowing report yesterday, from a stockopedia metrics perspective it doesn’t seem to tick many of the boxes. Definitely got me thinking on my pure metrics approach….
Hehe, joining BnB in giving you moral support ! good read, and a timely reminder that hubris is something to constantly guard against (something that I believed long before my investment journey). The current change in market sentiment (short or long lived) is flattering some of my poorer investment choices at the moment, the christmas break will be a welcome time to take stock !
Hi Mark. Thanks for the honest piece. In the absence of other comment, I just thought I'd let you know someone is out there and enjoying your article. Happy Christmas.