2025: A year in Value

The concept of Value has been a guiding light for investors for decades. The idea of buying stocks when they are cheap and selling them when they are expensive sounds logical, profitable and easy. However, it ends up being harder than you’d think. The challenge is that the most expensive stocks tend to have the best products, the best management, the best story, and the highest recent share price performance. Humans tend to be both narrative-driven and tend to overweight recent events, making it psychologically easier to own expensive stocks than the cheapest ones.
US Value Performance
The academic evidence for preferring cheap stocks over expensive ones is strong, but as with any investing anomaly, it relies on very long-term performance analysis and is prone to being arbitraged away. Indeed, the classic Value factor, which looks at Price-to-Book-Value, has weakened significantly in the US in recent years. 2010 – 2019 has been described as Value’s “lost decade”, as many analyses show the academic Value factor was near zero or negative in this decade, which is in stark contrast with earlier decades. Many reasons have been proposed for this, ranging from the impact of low interest rates to the different accounting treatment of intangible versus tangible investment. Whatever the reason, the reality is that big tech companies were the winners in this period, and these tend to be expensive on many measures.
It seems that the academic Value factor has struggled from 2020 onwards, too. The continued preeminence of big tech has led to excess Value returns being flat or even negative in the US so far this decade. However, 2025 itself has been positive, with estimates putting the returns to going long the cheapest stocks and shorting the most expensive ones at around 5% this year. This may be the start of a new era for Value in the US, after a long time in the desert.
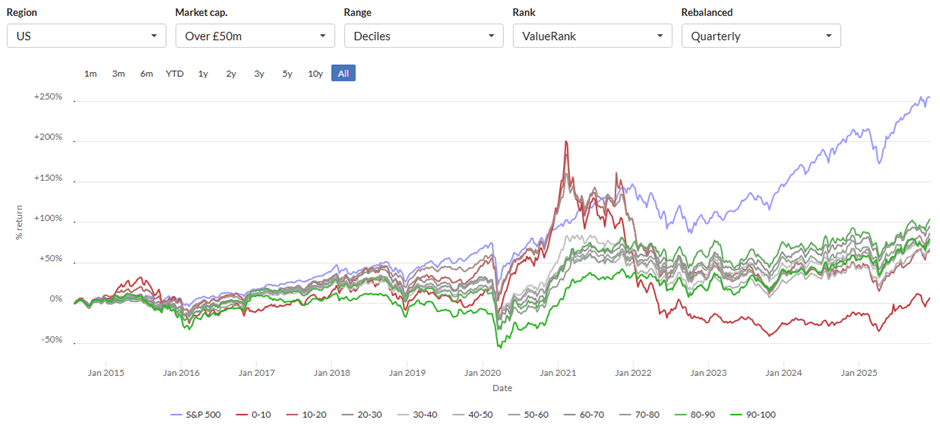
Historically, the Value effect has been most prominent in smaller companies. Small Value in the US has generated around 3-4% higher returns than Large Growth per annum from 1926 – 2024, even including more recent poor returns to the Value factor. While there are some signs of a recovery in the Value factor, small company returns in the US have lagged larger companies by 4-7% in 2025. US smaller company returns have been trounced by larger companies over the last few years. So much so that the historical outperformance of smaller companies has even been called into question by some academics. It is this effect that we see in the long-term returns of the Value Rank deciles in the US. When almost all cumulative equity returns have come from just a handful of stocks, every equal-weighted decile of stocks underperforms a market-cap weighted index:
US, Value Rank Deciles, Since 2014
UK Value Performance
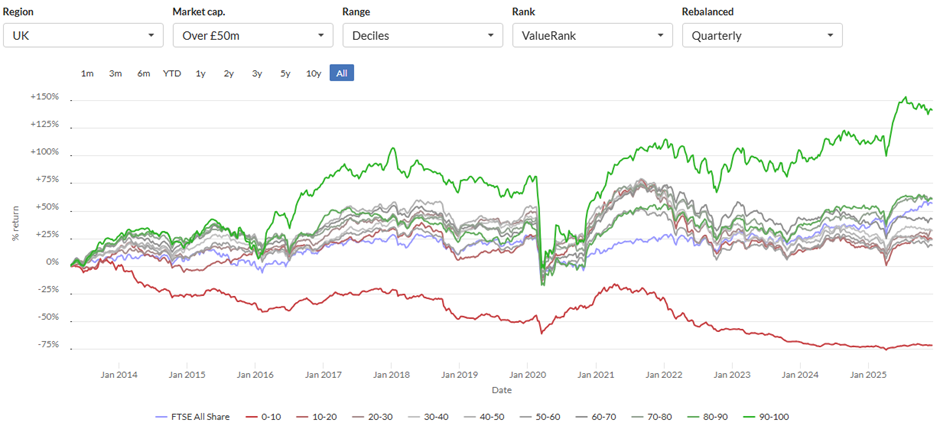
In the UK, the long-term outperformance of cheap stocks is more clear-cut, as the UK market lacks the very high technology mega-cap concentration. If I ignore the microcaps, which are particularly volatile, the cheapest stocks on the Value Rank have handily outperformed both the most expensive stocks and the wider UK market:
UK, Value Rank Deciles, Since 2013
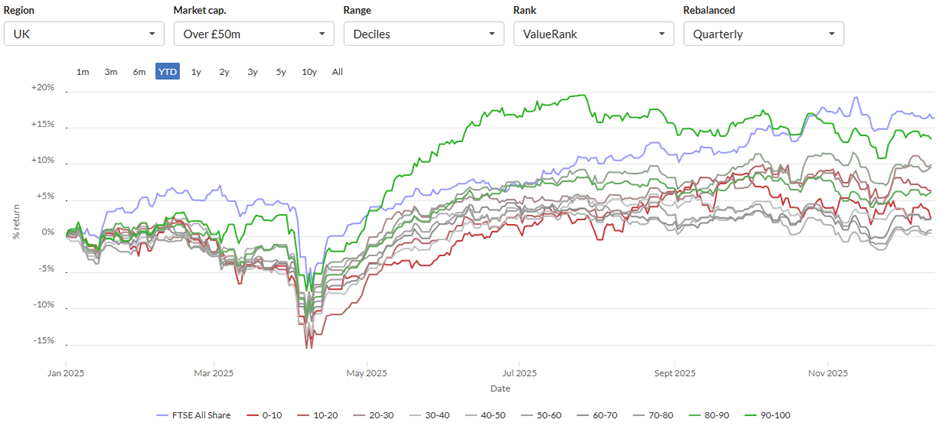
However, when I zoom in on the year just gone, the story is a little different. While the cheapest stocks had a great recovery from the Trump Tariff Tantrum, they have given back some of these gains and now lag the wider index:
UK, Value Rank Deciles, YTD
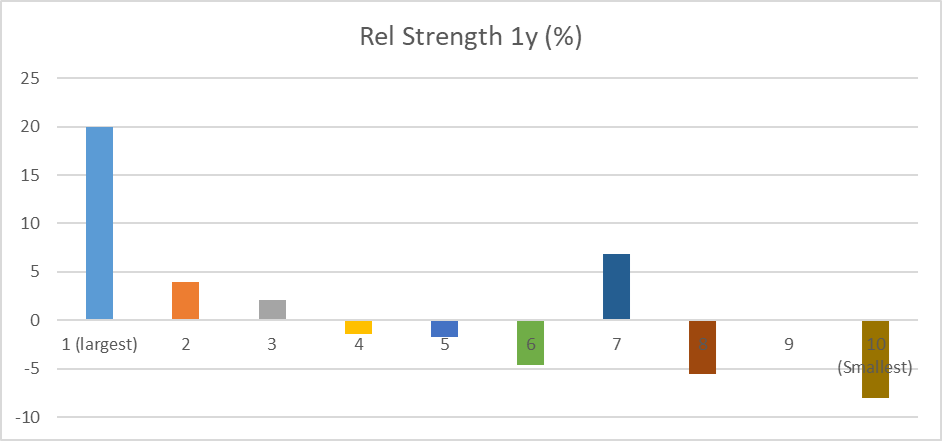
The reality is that these equal-weighted deciles suffer from the same issue. Almost all the returns this year in the UK have been in the FTSE100. When I wrote an article on this earlier in the year, I noted that the top decile of trading companies, roughly equivalent to the FTSE100, significantly outperformed all the rest of the UK market on median relative strength:
So, the Value story looks a bit better when I focus on only the Large or Mid-cap stocks:
UK >£2.5bn, Value Quintiles, YTD
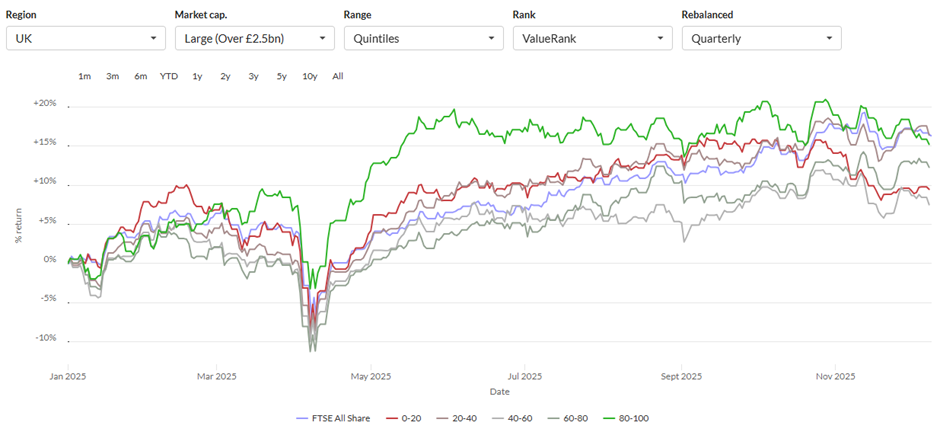
[I’ve used quintiles here, partly to make the more tightly clustered performance clearer, and partly because fewer stocks make the result noisier at a decile level.]
The FTSE100 also has large mining companies, banks and defence companies. Many of these score highly on Value metrics and have been some of the top performers in 2025.
UK £350m - £2.5bn, Value Quintiles, YTD
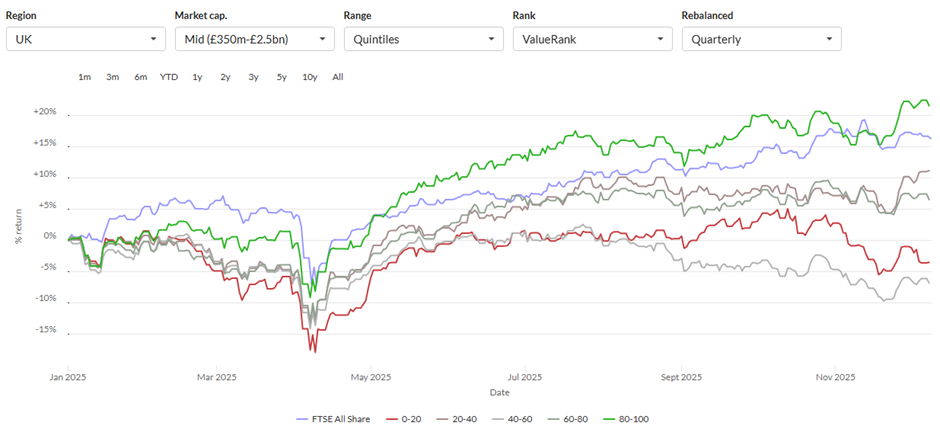
But as I go below £350m, the Value Rank performance is much weaker, and the overall weakness of most companies not in the FTSE100 becomes apparent.
UK £50m - £350m, Value Quintiles, YTD
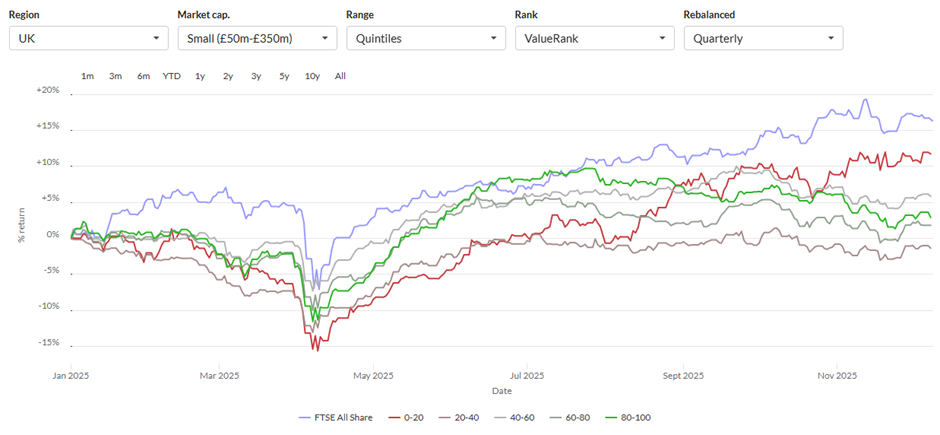
This effect may be due to the types of companies that are outperforming. Take mining stocks, for example. Larger companies will tend to be consistent producers of commodities and modest multiples. Rising commodity prices are likely to be quickly reflected in both broker forecasts and the price. However, at the smaller end, mining companies are likely to be more speculative, with pre-production assets or single assets in risky jurisdictions.
It also seems that the few stocks that have been able to IPO or raise equity at the smaller end of the market this year have been mining, biotech, AI or cryptocurrency-related companies. These typically fare badly on the Value Rank, as they tend to generate poor returns for investors over the long term. It is perhaps no surprise that the median Value Rank for the smallest companies is below 50:
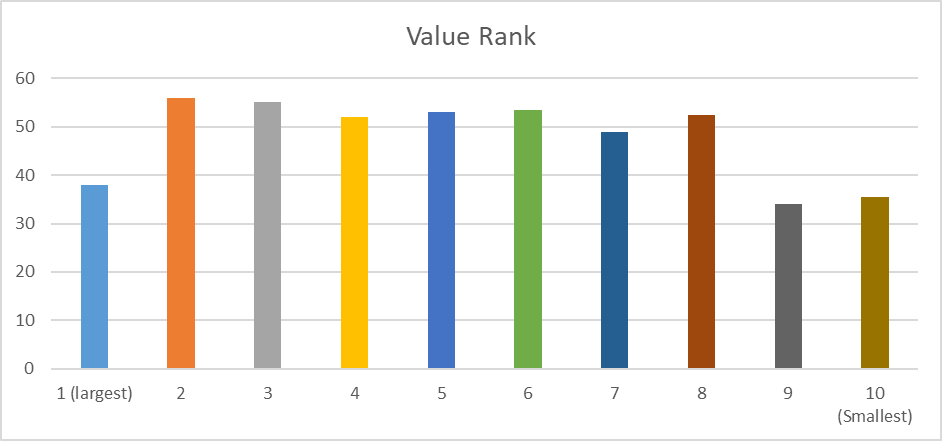
While that may make investors keen to avoid this part of the market, when I look at one of the most popular measures of Value, EV/EBITDA, the picture looks a little different. Here, the median values of companies with positive EBITDA decline almost continuously as you go down the market cap deciles:
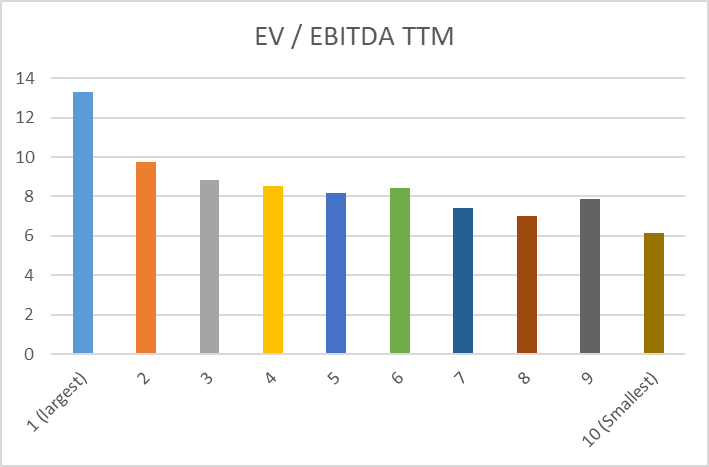
The £100m market cap level is from the seventh decile, so those willing to fish in smaller waters may be getting a bargain.
How did my 2025 predictions pan out?
At the end of 2024, I made four Value predictions. Let’s see how I did:
2025 Prediction #1 - Takeovers will continue to be regular occurrences
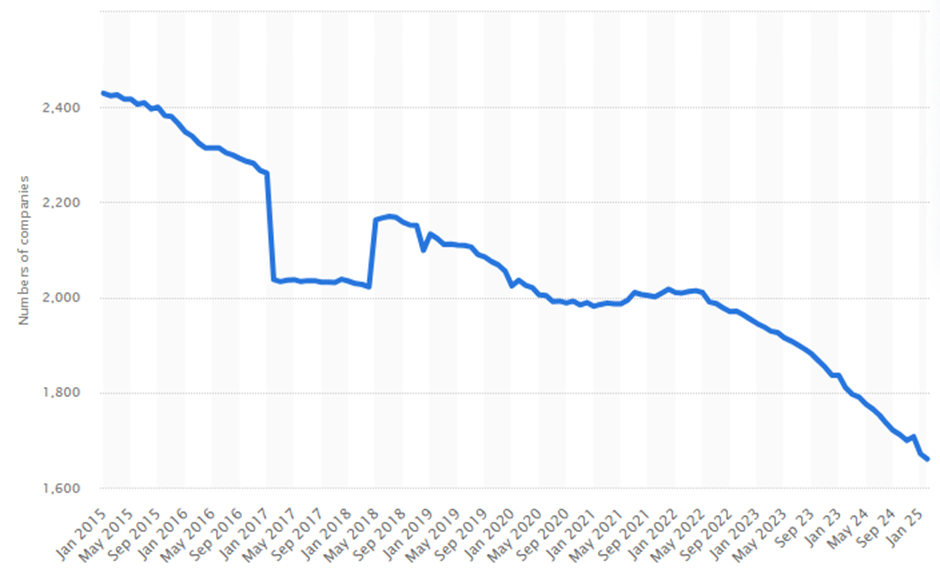
My biggest conviction was that low valuations would mean that we would continue to see takeovers. Anecdotally, this was the case. The continuing reduction in the number of UK-listed stocks also backs me up on this one (although delistings will also have played a part here):
[Chart: Statista]
2025 Prediction #2 - Cash will be king
With continuous outflows from equity funds, I thought it made sense to focus on cash-rich companies that could use their financial strength to buy back shares or pay out large dividends that can be reinvested. Anecdotally, this would seem to have been the case. Often just the announcement of a buyback was enough to increase a share price by 5-10%, as the signalling that the shares were undervalued and management were willing to do something about it, was enough to reverse a falling price. However, when I look at the data, the picture is not as clear. As a whole, companies that reduced their sharecount underperformed those that didn’t.
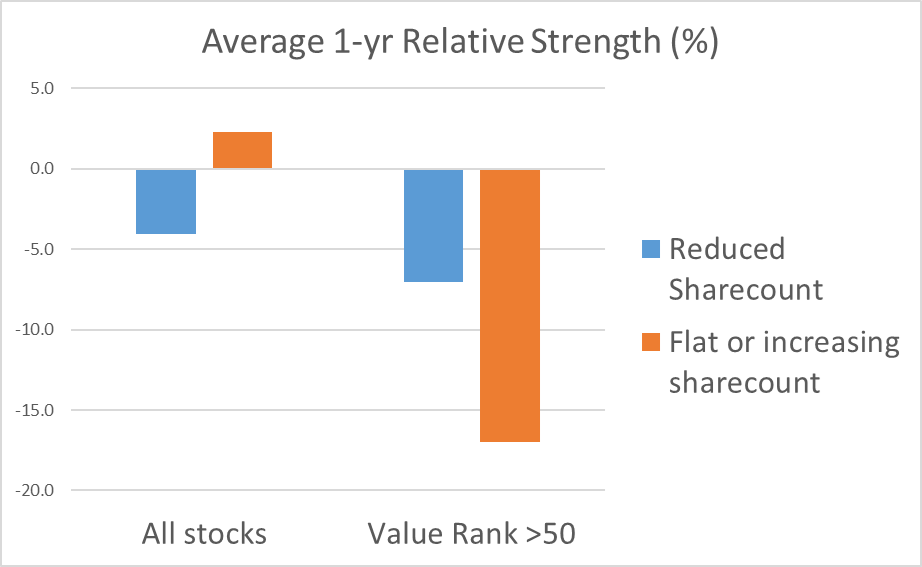
In some ways, the picture is better if I only look at companies with a Value Rank above 50. However, in this case, both sets of stocks underperformed, on average. [Again, this is possible because equal-weight averages underperform market-cap weighted indices when large caps outperform.] The reduced sharecount companies just lost less money. Note that this is the Value Rank now, not at the start of the year, so if a company looks cheap now, it is probably because of share price falls during the year. It does seem that companies with cash that were able to buyback shares into a falling price, helped reduce losses and may accelerate gains if a recovery comes.
2025 Prediction #3 – Volatility will increase
I thought that we should have expected a period of greater uncertainty in the US, which would be reflected in greater stock market volatility, and for this to have a knock-on impact on the UK markets. We certainly saw this with precipitous declines in response to surprise tariff announcements in the US. However, the recovery from this was swift, and markets have been remarkably benign since the summer (at least as seen through the lens of the major indices), despite the political risk probably ramping up, not down:
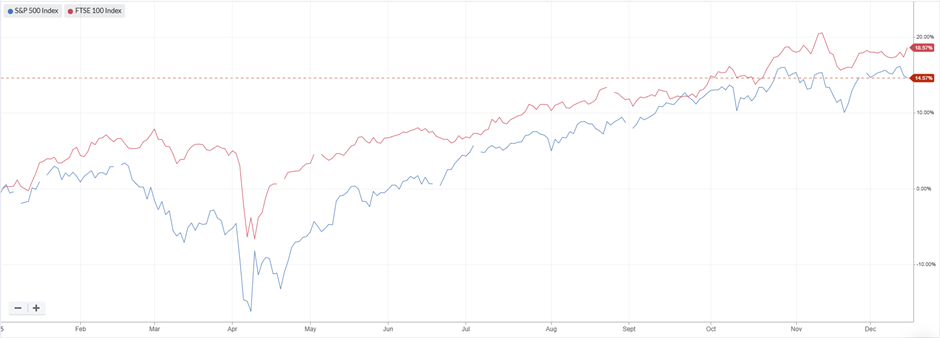
Perhaps we call this a score draw.
2025 Prediction #4 – The smallest companies will finally catch up
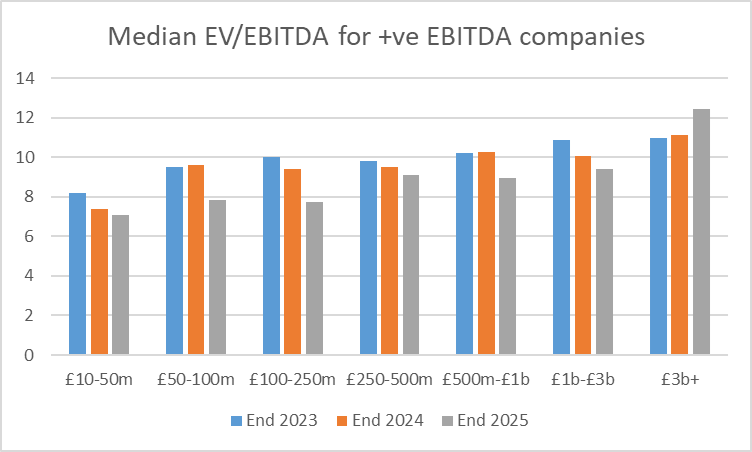
For the second year running, I have been completely wrong about this. Large caps have continued to be the place to be. I’d hoped that 2025 would be the year when the valuation anomaly would revert to more normal times, where smaller companies trade at a premium to larger caps to reflect their greater growth potential. Instead, that gap has widened further:
Predictions for 2026:
1. The smallest companies will finally catch up
Making the same prediction three years in a row, having been wrong for the first two years, risks making me look foolish again. However, the graph above shows the scale of the valuation gap. At the end of 2023, the gap between the median EV/EBITDA for the largest and smallest companies was around 3, and now it is approaching 6. The difference doesn’t seem to be due to any differences in the quality of companies or their growth outlook. While broker coverage is patchy for the smallest companies, the logic that says they have better medium-term growth prospects is backed up by the data. (See my article here for details.)
2. Takeovers will shift down the market cap range.
I see no let-up in the pace of takeover offers, but I expect the valuation gap as we go down the market cap range to bring smaller companies into play. If you run a large or mid-cap business which is struggling for organic growth, then buying out a smaller competitor makes a lot of sense. Historically, businesses may have looked to the private markets to get the best deal. However, paying a 30-50% premium for a listed company, with the ability to strip out a lot of listing and board costs, may actually seem a better opportunity.
3. It will be a shotgun market for Value Investors
I’ve written in the past about markets being sniper or shotgun ones. In a sniper market, there are small pockets of incredible Value, where a sector or company has become unloved for one-off reasons. However, in current UK markets, there are so many opportunities that investors may want to get out their shotgun and blast away with much less discrimination. I don’t see any easy answers to the economic woes that have troubled a lot of companies recently, but these are largely cyclical and will abate over time. Markets are forward-looking, so the moves in share prices are likely to occur before the recovery is visible in the financials. In such situations, which stocks capture investors' imaginations and get re-rated can be largely random. Holding a wider selection of cheap stocks that could jump on any good news (or even a newspaper tip) may make more sense than holding a concentrated portfolio of their best ideas.
Whatever 2026 has in store, Stockopedia will remain your faithful investing guide.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

2 comments
Great piece thanks Mark. I continue to Keep The Faith in the resurrection of smaller companies too!!
Another good article Mark, thank you. It's the first time I've seen a chart showing the total number of UK stocks over time. The decline is stark and very worrying. I've been investing since 2010 and it certainly feels like a much less dynamic market now, compared to 10-15 years ago. So much so that I am investing in other places far more than I ever have done before. I thought Labour showed some signs that they understood the problem before the election, but they've done precious little to support the market since getting in, unfortunately. I'm beginning to doubt whether the UK mid and small cap market will ever regain the depth of quality that it used to have.
This chart from Bloomberg also speaks volumes. The article it was contained in says the UK has fallen outside the top 20 markets globally for IPO activity, behind places like Mexico. Grim, indeed.