#3 - Serabi Gold - mining a rich seam

This is #3 in our "Twelve Stocks of Christmas 2025" Series. You can review the full set here.
The Pitch
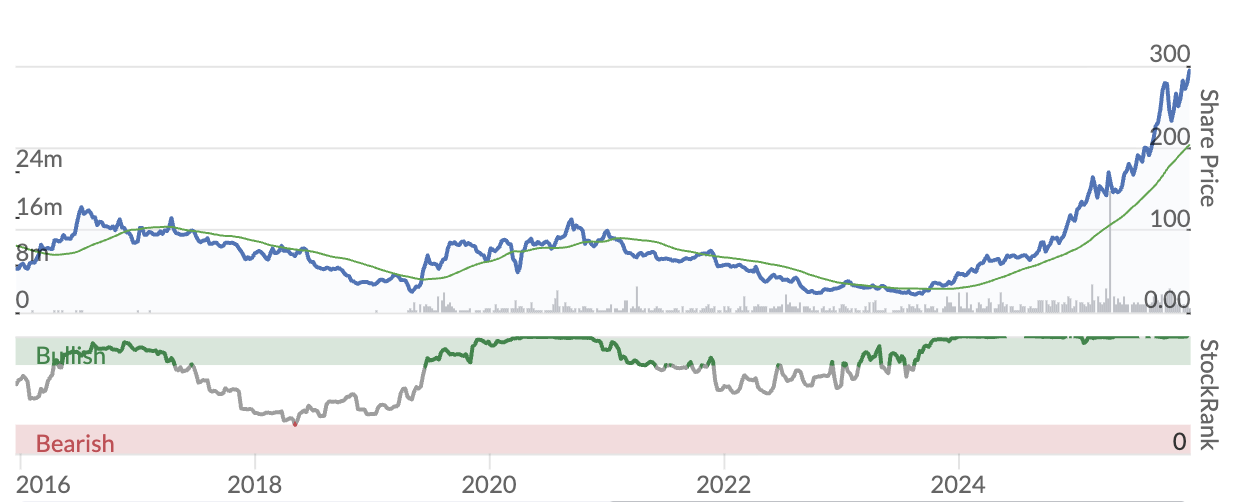
Serabi Gold (LON:SRB) is an AIM-listed gold miner operating in Brazil which has ten-bagged from lows in 2023. It has strong operational momentum with production up, gold grades improving and cash balance growing. With a StockRank of 99, Serabi is high-margin small cap riding the gold price tailwind, surging free cash flow and an exploration push for a 2 million ounce (2Moz) resource. A low valuation and broker upgrades support further price appreciation in 2026.
The Big Picture
Serabi operates two high-grade underground mines - Palito and Coringa - in the Tapajos region of northern Brazil. It's an underdeveloped but very prospective region, until recently dominated by artisanal mining. After a decade dealing with operational setbacks and funding issues, Serabi now stands as the only serious hard rock producer in the region.
- Why now? The company is hitting record production. Year to date output hit 32.6koz, which was a 19% year-on-year rise. It's on track for 44koz+ for the full year, with further growth forecast up to 57koz in FY26.
- Grades improving - plant feed grades jumped 30% in 2025 from 5.4 grams per tonne to nearly 7.0 g/t - which speaks to the efficiency improvements.
- Coringa ramping up - Two new zones are coming online, which would put 60koz production within reach in the future.
Going deeper
Serabi is a high-grade underground mining company which operates at lower tonnage. It trucks ore from Coringa to a central plant at Palito which can unlock growth without too much additional capex.
- Cash generation - Q3 saw net cash inflow hit more than $34M, with year end cash expected at $45M - that’s 15% of its market cap.
- Ore Sorter success - Coringa's ore sorter is now handling higher-grade run of mine ore, which increases gold production and lowers haulage costs by removing waste rock.
- Exploration upside – recent drilling hit "spectacular" grades at Palito Senna Zone. This supports Serabi’s goal of nearly doubling the resource base to 2Moz.
- Undemanding valuation - In spite of a 160% share price rally in 2025, and forecast EPS growth of almost 60% -the P/E remains low, below 4x forecast estimates.
What the brokers say
Serabi is covered by both Zeus and Tamesis. They are both strongly bullish and cite the organic growth, high gold prices, and robust performance as key drivers.
- Punchy price targets - I can be sceptical of broker price targets, but I trust the direction of upgrades. Zeus in October raised their target price to 386p from 282p. Tamesis have held theirs at 400 pence. Compare a 290p share price.
- Shareholder returns - Tamesis expects $72M of free cash flow for FY26 and a possible dividend. Management have flagged that returns of 20-30% of free cash flow could be on the cards.
The bear case
Serabi's recent execution has been very strong, but there are, of course, always risks in small-cap mining stocks. Here are a few specific to Serabi.
- Short mine life - total resources are just over a million ounces, which limits the current mine life to less than 10 years unless exploration extends reserves.
- Coringa permitting risk - the company only has a trial mining licence until January 2027, and a full permit is under review, which could lead to operational delays or worse. There are various disputes over land claims and indiginous Amazon groups.
- Cost creep - as a high-grade underground producer, Serabi has a higher AISC (all-in sustaining costs) than many Gold juniors. Q3 costs were $1,816 per ounce, which were above forecast due to inflation in Brazil. Less room for error if gold falls.
- Gold Price - this goes without saying, but I'll say it anyway. If the gold price catches a cold, all gold stocks are going to see a reversal.
The Bottom Line
Serabi Gold has been executing well in this gold bull market. It's seen grade improvements, strong cash generation and is leveraging the infrastructure it’s already put in place. It's also very well positioned in a region that few have managed to develop. In spite of the 160% share price rise in 2025, there could still be significant upside if production ramps up as planned.
(Disclosure: The author is a shareholder in Serabi Gold)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

11 comments
Serabi Gold (LON:SRB) gave a 'Q4-2024 Production Results and Operational Highlights' update on the 15th January last year. So worth watching out for this year to see if production is still going up.
Serabi production is rising but not as fast as the share price, more a hold than a buy by contrast Amaroq at 100 p is twenty pence cheaper than when it poured first gold this time last year and should be producing 50000 ounces from April possibly 75000 from April 2027
Interesting never heard of them, will check them out
Mr Croft. Thanks for bringing back the "the Pitch".
I will not follow blindly like a sheep, hang on every word like its from an investment Bible.
You can say whatever you like, if the chart ain't working then as the Dragons say "I'm not in".
But love to see what you think may be in play in 2026.
For me Silver continues - tough buying at highs. Gold may consolidate but watch the breakout. Crypto seems to be involved here for some reason.
War (Defence) rubbish in Europe (no money), but US kicking with Space, AI, drones over and under water etc. And mineral exploration with sonar/Lidar tech (not the Ol-timer with river bed filter tray thingy).
Energy is always there - now renewables called out as not the cure we are back in Oil or better LNG. Need to keeps the lights on and data centres searching for your next Amazon xmas present or Grok query whilst waiting for the nukes to turn up in 7 years time.
My main concern with Serabi is that everyone I meet who has at least one UK gold stock seems to have this one - including myself. But it remains a pretty compelling argument, and this is a very well-established company with apparently excellent relations with local government and people. Interesting that the very defensive Ruffer fund have a stake though one should be aware that this is still a pretty small producer and for most purposes a small cap. Which means it could become illiquid if gold does reverse.
To add to that I would say the AISC of Serabi is high enough encourage a rush to the exit if te price of physical gold should drop substantiably.
Thanks Ed, though your piece is a round-up's a little behind the times. I've had a roller-coaster ride going from bust with Hummingbird to boom with Serabi (and others). Here's to 2026 and your NAPS and to those whose gold shares whenever they hit a Stop Loss, BUY.
A big pat on the back for recomending SRB along with MTL in the Naps list 12 months ago. Newly subscribed and wanting to be free of my North American equities, influenced by the potential wasteland of Trump economic influence, I piled in and was delighted to find that the US Dollar was and still is falling in value fast enough to inflate the value of gold, as it is becoming sought after as the logical alternative to provide central bank reserves.
I was able to keep my nerve during the recent price correction believing the rise in price has further to go yet, since all of the factors undermining restricted world trade and the American economy are still in place and have since added THX to an increased stake of SRB.
All news from Gold mining fronts seems positive with MTL overcoming severe weather problems and still moving faster than estimated without losing their high share of institutional investors.
I guess the trick with this category will be to follow news and political shifts fairly closely to avoid missing any sudden shift in momentum.
Happy new year to all fellow investors
Top job piling in to Serabi Gold (LON:SRB) I ignored an alert I set which triggered at 71.48 per share….you can imagine the rest of the story! I am laughing about not buying now and better luck for me next year! Happy 2026 to all.
Mark did a valuation of Serabi Gold (LON:SRB) in October. This showed a dscounted cash flow valuation roughly twice the market cap.
Obviously the share price has risen since then but so has the gold price.
All that glitters is gold (producers) – Part 2 | By Mark Simpson | Stockopedia
FWIW - Just did a chart comparison against £GJGB and £RMAP - You will see the Junior Gold Miners ETF wins for various periods over 2025. Worth noting that Serabi is not listed among the holdings of £GJGB indeed Brazil is only 0.51% of the country allocation. That said - I'm happy to hold Serabi Gold (LON:SRB)