#6 - Smiths News - still delivering for shareholders

This is #6 in our "Twelve Stocks of Christmas 2025" Series. You can review the full set here.
The Pitch
Smiths News (LON:SNWS) is a classic “cigar butt” stock, providing newspaper and magazine delivery to 22,000 retailers across England and Wales. As newspaper circulation declines, it’s thought that businesses like Smiths News are inevitably headed for extinction - but it has proved remarkably robust so far.
With the company still pumping out a healthy level of profits, and revenues declining at only a modest pace, I think it’s worth asking again whether management might yet pull more rabbits out of the hat for investors. If they invest the company’s cash flow wisely, or at least send most of it back to the company's owners, investors might continue to prosper for a surprisingly long time!
The Big Picture
A company with a checkered history: This was originally WHSmiths News, until it was carved out from WH Smith in 2006. It was then known as Connect Group from 2014 to 2020. Shareholders have suffered at various times, including from acquisitions that didn’t work out as planned. Tuffnells parcel delivery is the standout loser in this regard - bought for £113m and sold for £15m.
Learning from past mistakes: CEO Jon Bunting has been with the company since 1994. He was interim CEO from 2019, and then permanent CEO from 2020. He has not made any major acquisitions during his tenure in charge. Instead, the company has focused on paying down debt and on paying increasingly large dividends to its shareholders.
Going Deeper
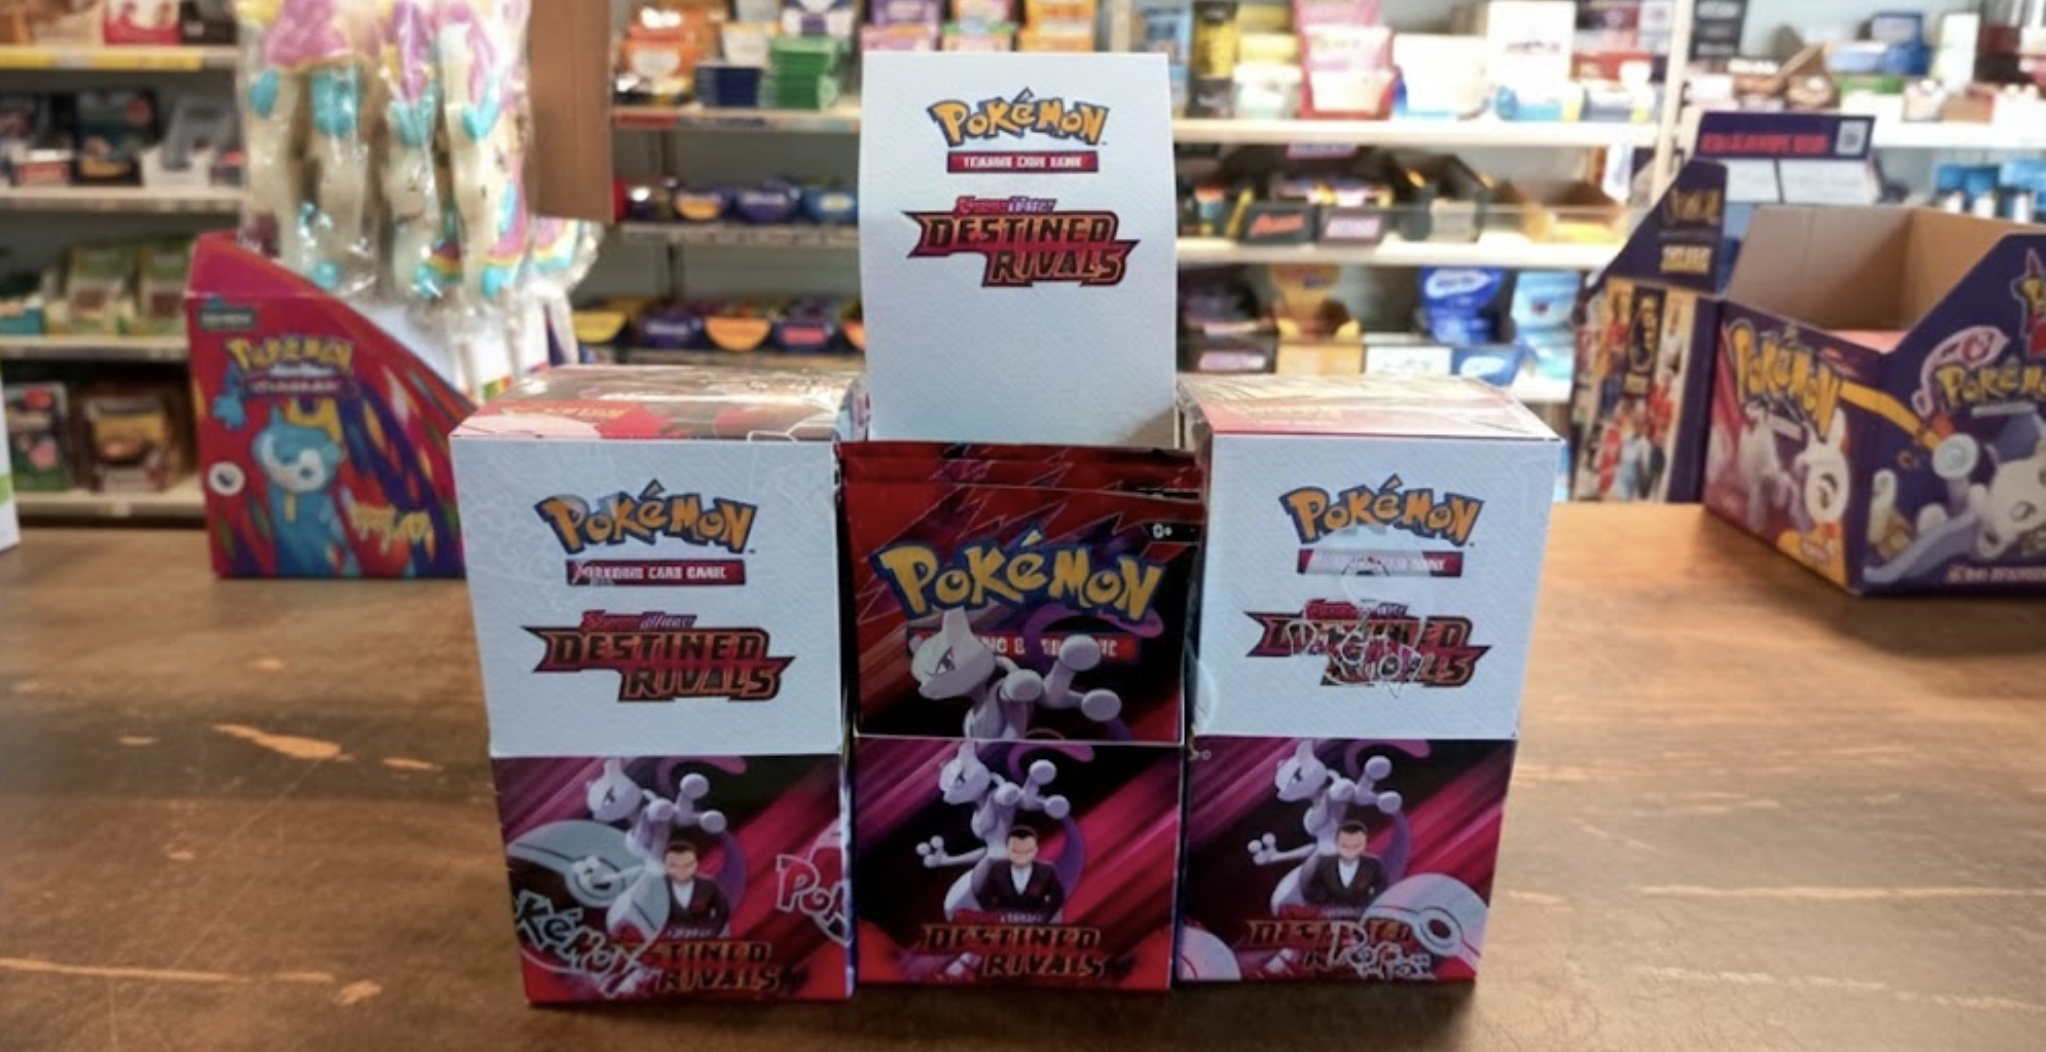
Beating expectations: recent full-year results showed the company replicating last year’s result in terms of adjusted operating profit (£39.1m), and this was better than the market had expected. Excellent growth in the collectables segment helped - products like Match Attax and Pokémon cards.
No funny business: the statutory after-tax profit result (£28.3m) was actually higher than the corresponding adjusted figure (£27m). This was true last year, too. This suggests very clean accounts.
Rewarding shareholders instead of management ego through M&A: the ordinary dividend was increased from 5.15p to 5.55p, while the special dividend increased from 2p to 3p. The total payout of 8.55p was well covered by 11.1p of earnings per share.
Strengthening balance sheet: The company also moved from an average net debt position of £12m into an average net cash position of £3m.
What The Brokers Say
Following the recent results, Canaccord Genuity increased their 2026 and 2027 revenue forecasts, with the result that revenue is now expected to decline by only 3% in 2026 and then a further 3% in 2027.
Investment in new verticals: there is a slight drag on profits from increased spending on new business lines. These include a recycling service and the delivery of books, home entertainment and greetings cards as the company attempts to deepen its ties with supermarkets and high street retailers.
As a result of this investment, Canaccord Genuity did nudge their profit forecasts very slightly lower: adjusted PBT is now expected at £34.3m (FY August 2026) and then £35.2m (FY August 2027), down by just £500k compared to previous forecasts.
The Bear Case
New Capital Allocation policy doesn’t work: the company has failed at capital allocation in the past, and there is always the risk that they will fail again. The leverage multiple they have committed to (less than 1x) is prudent, but where they could really fall down is with their new verticals. These new business initiatives might simply not be profitable or large enough to replace the declining volumes in their core distribution business.
Newspaper volumes shrink faster than forecast: if newspaper and magazine volumes reached some sort of “cliff-edge”, which involved major publications abandoning their print editions, this could accelerate the collapse of the core business.
The Bottom Line
Smiths News has a StockRank of 100 as I write this, with Quality, Value and Momentum Ranks all above 90. The shares trade on a PER of 7x with no adjustment needed for debt, as the company has now moved into a net cash position despite growing its dividends and carrying out the necessary spending on its chosen growth initiatives. With management taking a measured approach to growth, and running the core business for cash flow, I think this continues to be worth a second look.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

17 comments
Don't get too hung up on the newspaper side. I am pretty sure the other stuff they deliver is bigger. eg Magazines. Especially at Christmas when they deliver all of those TV Times and Radio Times special editions etc. We have an ageing population who don't give a damn about 'everything is on the internet you know'
Yep. And the World Cup coming up ought to boost newspaper sales
And football cards/albums
Hi Graham, I hope you had a good Christmas!
Just wondering, when you say above with a link you can find the find the full set here, are there further stocks being added each day, I can see 6 up to now which appear to relate to this?
Thanks and best wishes,
Michael
There will be 12, as last year.
Hi Michael, I hope you saw what we did - we published the other 6 shortly after this one! All the best.
"Tuffnells parcel delivery is the standout loser in this regard" The record of parcel delivery companies seems a pretty bleak one. Lots of tough competition. I don't know what the directors were thinking.
I didn't know what the Smiths News (LON:SNWS) Directors were thinking of when they bought Tufnells. Cou;d they not see it was another GEC? (Go Easy Club) My Smiths News shares spent years in the wilderness as a direct result.
Aren't they already in the delivery business, just need new customers, even at marginal costing contributes to overheads?
surely you know that the delivery business is a race to the bottom right - i am not saying there in no place for company delivering good service deliveris not to be able to make a profit - but you cant argie this has to be one of the most competitive sectors there is - with many tax drivers / van drivers happy to pick up extra stuff for not alot of fees themselves - can they compete on price with one man band who already has their costs covered and would deliver dirt cheap?
I hear what you are saying and maybe the day of the employed delivery driver is under pressure (although the pension scheme encourages driver loyalty). The delivery drivers I speak and my wife is a big online buyer (sadly) is they like the independence even if the hours are long and the rewards are limited. I can see Smiths in future adopting the UBER type model for future business. Notwithstanding I am Smith's holder just for the reliable dividends.
can see Smiths in future adopting the UBER type model for future business.
i am deffo generalisng - even in tough markets there will be winners and losers - so not saying there are not opportunities or that they may not do well - just that it should be any sort of surprise if delivery struggles to deliver decent profits to match what it did.
as you say if they have independents working for them perhaps they can pimp them out .
does delivery contribute much to profits now anyway ?
I bought into Smiths News (LON:SNWS) on the night before the 4th Nov prelims, and doubled up at the open after the release which read well. It is now my largest holding by both book and current value. The reason for this potentially rash and risky decision was down to yield hunting using Stocko screening, to use significant uninvested cash within a family ISA, and having already lumped on to International Personal Finance (LON:IPF) and TP Icap (LON:TCAP). Using Stocko screening, rankings and current / historic data I was able to build up pretty decent conviction on the position.
I definitely did not expect the increase in SP to happen as it has over the last 8 weeks and worries about uninvested cash are now replaced by worries about banking 17% paper profits and foregoing said yield which is around 13% at my buy-in (assuming a 1.75p is added in June 26 to the upcoming 3p and 3.8p divs) - the dilemma of a private investor!
Great to read positive commentary from Graham on this one, and my aim of this post is not to be a smart-a$$ but to show my support of the tools and info available on Stocko which 100% enabled me to find this one. I will be glued to the weekly stock rank changes watching for any significant changes.
I found it using a simple screen which included yield greater than PE. Found IPF as well, though sold that at a good profit although to early given the bid shortly later.
I sold Smiths News (LON:SNWS) in August at 55p after 3 fairly flat years, out of boredom with it really. Error!! Now 75p and with some momentum behind it. But I can't bring myself to buy back in. It does seem fully valued now??
A Stocko value rank of 92 would suggest otherwise, as would a per of 7 and p/fcf of 4.2 for a company returning 92% on capital with c. 7.5% dividend to boot. I hold.
Maybe just my wishful thinking then having sold but for a cigar butt stock a PE of 7 is generally pushing it. Good luck to all though who hold I would not be surprised to see it hit close to 90p with the momentum it has .... (I wish I could remove it from my screen haha!)