52 -week lows – finding promising investment opportunities part 2

In my last article, I started going through the results of my 52-week lows screen. I reviewed the screen results from the Recruitment, Household Goods and Property sectors. The idea was to sort the screen results into stocks that were hitting 52-week lows for good reasons, and those that were languishing simply because they had been overlooked by investors. In the current markets, finding the latter may present a short-term opportunity, as anything that puts these on investors' radars again could deliver a significant re-rating.
This week, I'm continuing the exercise by reviewing screen results from the remaining sectors: Industrials, Extractive Industries, and any other relevant areas.
Industrials
Strix (LON:KETL)
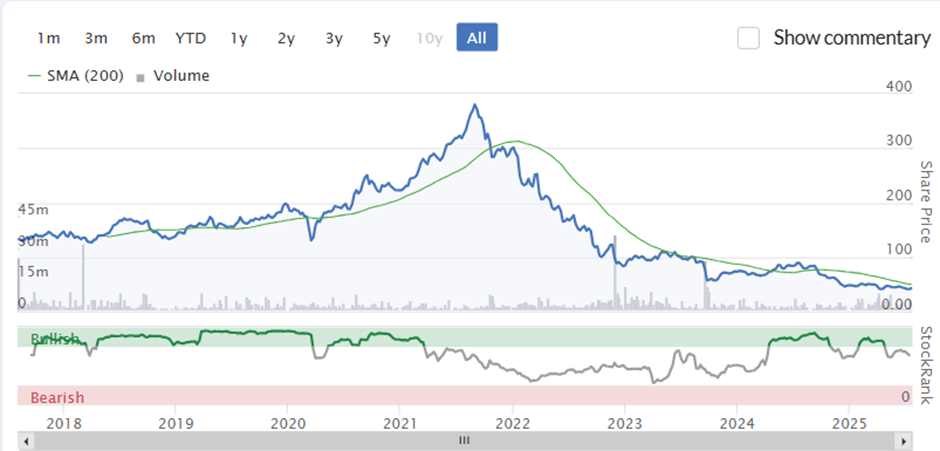
Strix has a rather familiar chart since listing. It was considered a business with a strong moat in kettle controls (hence a ticker that is nothing like its name). Investors got carried away with the valuation of this (and similar businesses) in 2021, and a combination of inflation, weaker demand and debt has seen the shares lose almost 90% of their value:
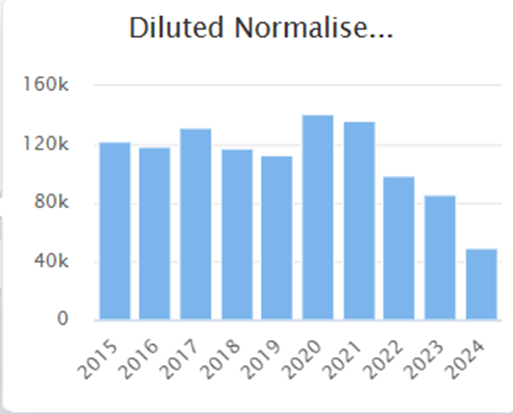
EPS, while clearly weak over the last few years, shows how exaggerated share price moves can be compared to the underlying performance of a business:
Part of this may be explained by the perception of the market that the moat here is being eroded, and kettle controls are now a commodity business. The ROCE has taken a battering recently:
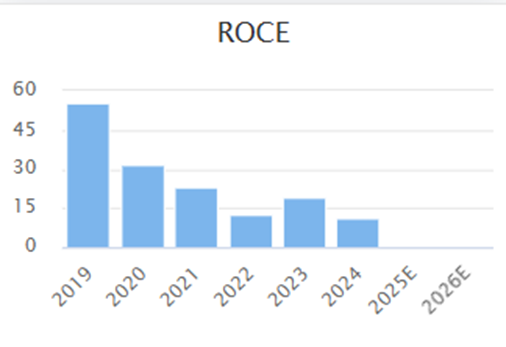
Although part of this will simply be due to lower EBIT, and any recovery here will see ROCE increase along with it. The answer to these trends from management has been to acquire related businesses in growth areas. In 2022, Strix acquired Billi Australia, Billi New Zealand, and Billi UK in a deal worth £38 million. In the same year, they also acquired LAICA, an Italian company focused on water purification. This largely explains the jump in net debt:
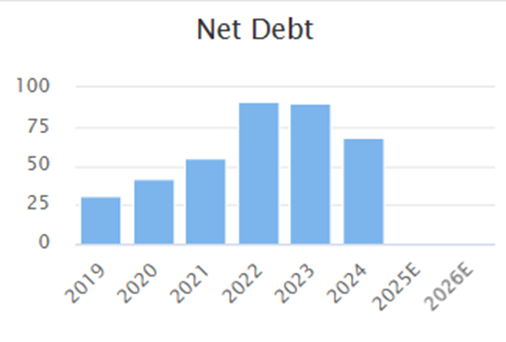
Along with higher net debt and weaker core trading came the need for a relaxation of banking covenants and higher interest costs. This meant they raised £8.7m of capital from the market in 2024 at 80p, representing an additional 5% of the issued share capital. The dilution was relatively minor, and a forecast recovery in profitability in FY25 means that they are on a very undemanding forward P/E:
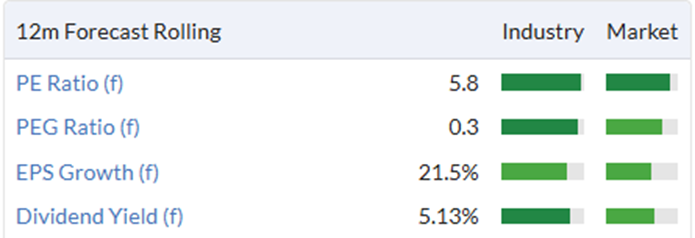
The historical value measures are less impressive, especially once the debt is included in EV multiples:
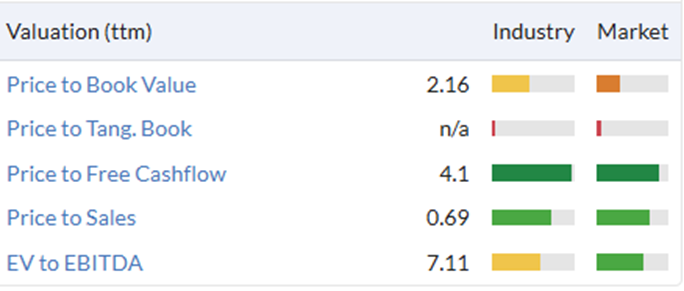
However, this will look better if they meet forecast profitability. EPS was downgraded due to a profits warning at the end of last year, but there have been no recent downgrades:
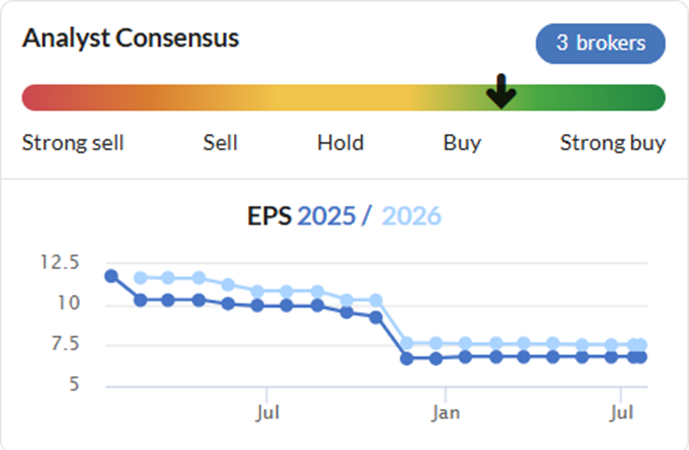
Worryingly, though, the recent AGM statement didn't contain any information about current trading despite being over six months into the new financial year. Instead, they referenced last year's trading and told investors:
The Group confirms that a competitive refinancing process will be formally initiated in the coming weeks to provide cost effective and flexible funding to support the Company's medium-term investment-driven growth aspirations.
This could be code for a further equity raise. However, if this can be avoided and trading is confirmed in line with expectations when they do release their up-to-date trading statement next week (30 July), then we can expect the shares to respond positively to this news.
Dewhurst (LON:DWHA)
This is a slightly strange company which has a voting share that is largely family-controlled and a non-voting share which is economically identical but doesn't carry voting rights. Given that individual investors are unlikely to own enough shares to force changes on company management, and they usually trade at a discount, most individual investors would only want to own the A shares (ticker: DWHA). The discount between voting and non-voting shares can be wide at times:
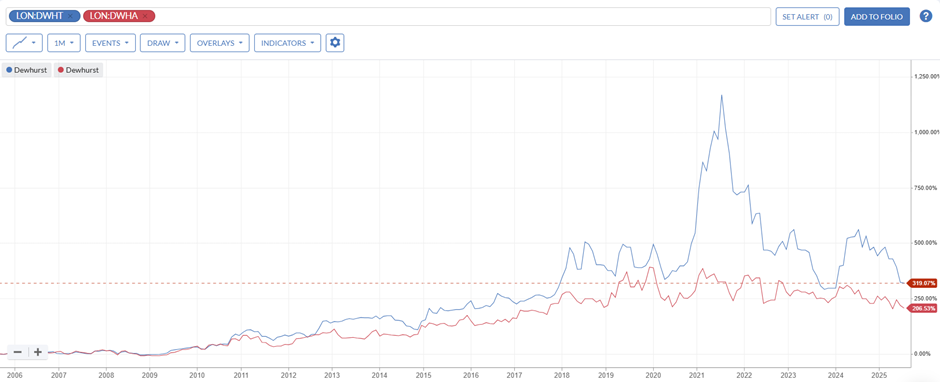
This combination can complicate valuation calculations. One of the big attractions is that the stock trades close to tangible book value:
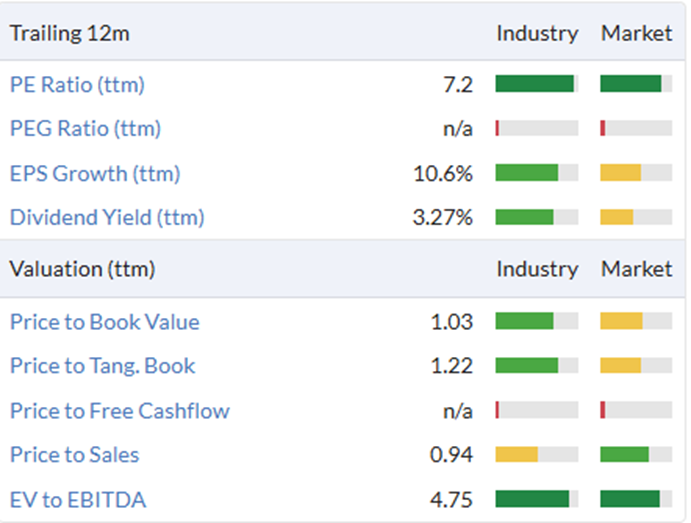
However, investors need to do their own calculations depending on how they choose to account for the two classes of shares. This is how I did it when looking at the stock on the DSMR recently:
Net assets increased to £63.m, of which £3m is the pension surplus, which is not accessible (or perhaps real!), £9.5m is intangibles, the bulk of which is goodwill. Net tangible asset value is, therefore, £50.6m.
Calculating how this compares to a market cap is tricky. There are 3.3m ordinary shares, which trade at £11, and 4.4m A shares, which trade at £5.50. This works out to be around £57m. However, as a holder of the A shares, an investor has economic exposure to the proportion of A-shares in the capital structure x their percentage holding of the A-shares. The effect of this is to take the total share count of 7.85m and multiply by the A share price, which is just £43.2m effective market cap at £5.50.
I think it is fair to argue that a buyer of the A shares is buying at a discount to TBV at the moment, and the buyer of the Voting shares is not. Not that it matters unless those assets are productive, or the non-productive ones, such as cash, are returned to shareholders. Still, it helps gauge how cheap the shares are and the value difference between the A-Shares and Voting-Shares.
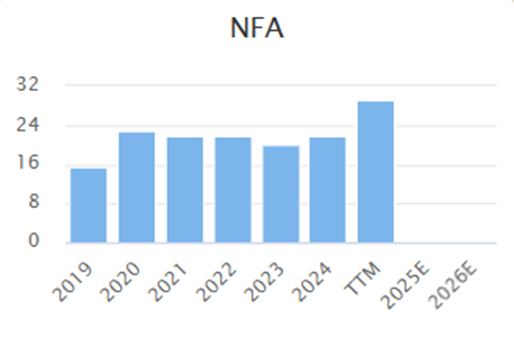
There are no forecasts for this company, so all of the rest of the metrics are trailing twelve months. The EV/EBITDA is perhaps slightly higher because they recently chose to buy the freehold of their A&A Electrical Distributors site in South Woodford, which means that their fixed assets have increased:
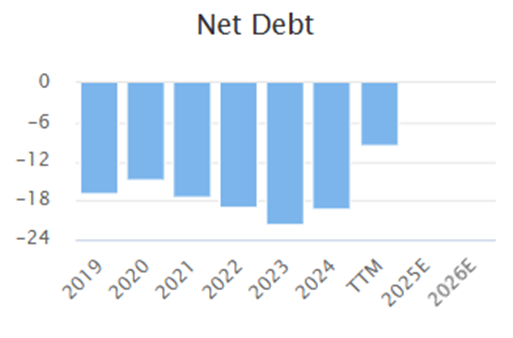
And net cash levels have gone down:
They also made an additional £2.5m contribution to their pension scheme, which is now marked as in surplus on the balance sheet on an IAS19 basis. However, this doesn't necessarily mean that it is on a Triennial valuation.
Much of the short-term valuation work comes down to investors' interpretation of the outlook statement in the Half Year results to 31 March:
The North American market has shown resilience in the first half of the year, but the ongoing uncertainty surrounding tariffs continues to affect confidence levels and cause delays in construction projects. The UK lift market has experienced some softening this year, exacerbated by weak UK economic performance. Persistent inflation, tight public sector spending and current subdued business confidence is also likely to make for a tough second half, however, there are opportunities for growth if the market stabilises. Orders in Australia have been mixed this year, and we are implementing a reorganisation to improve customer focus; this will impact on the second half, but the investment should improve future performance.
On balance, we expect a challenging second half of the year, with headwinds impacting on our growth prospects in several key markets.
This sounds pretty downbeat to me. Investors may also be worried by a Momentum Rank that is so low:
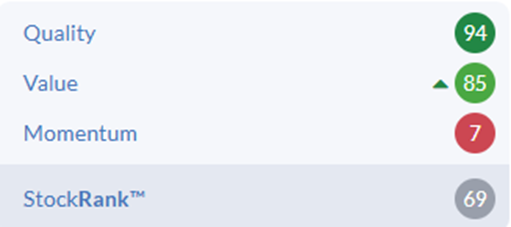
Although this should perhaps not be surprising for the results of a 52-week low screen, my recent research shows that investors may do better by avoiding Contrarian Stocks with the lowest Momentum scores.
Somero Enterprises (LON:SOM)
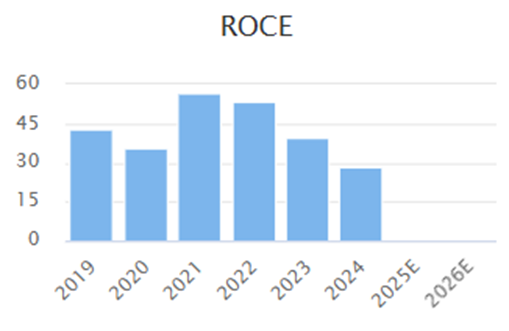
Somero will be well known to Stockopedia subscribers as it has been a well-discussed stock. I wrote a Stock Pitch article on the company here. The attractions are clear – strong returns on capital:
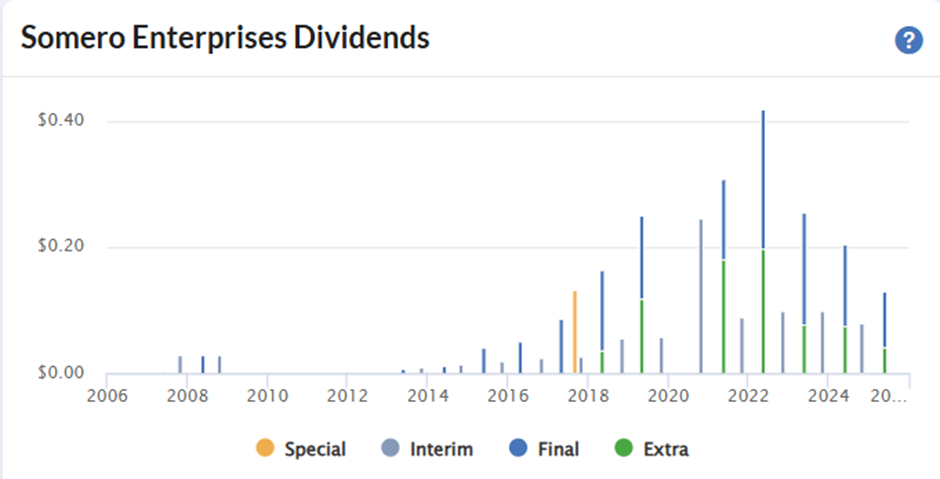
Plus, it is a highly cash-generative business, and hasn't been shy about returning capital to shareholders via ordinary and special dividends:
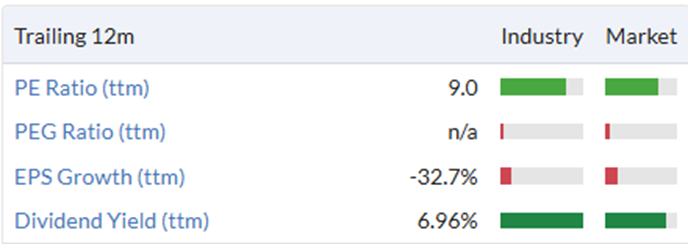
Despite this, the shares are on a very modest rating:
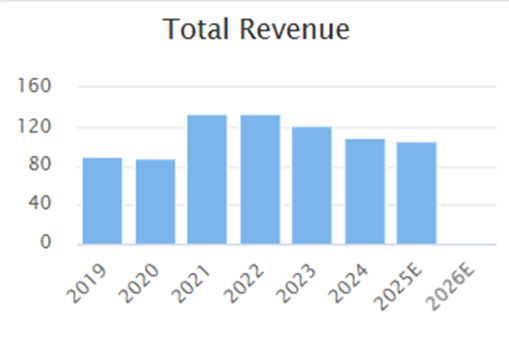
However, the big dividend payments reveal the problem here. The company has been unable to deploy additional capital at anywhere near its historical rates of return. Their new products have yet to reach sales anywhere near their core concrete levelling machines. This means that revenue is not really growing:
Earnings follow a similar pattern:
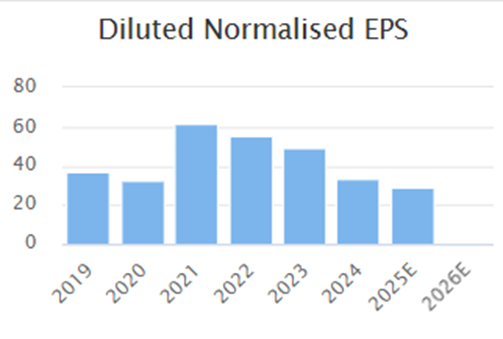
And have faced two downgrades this year:
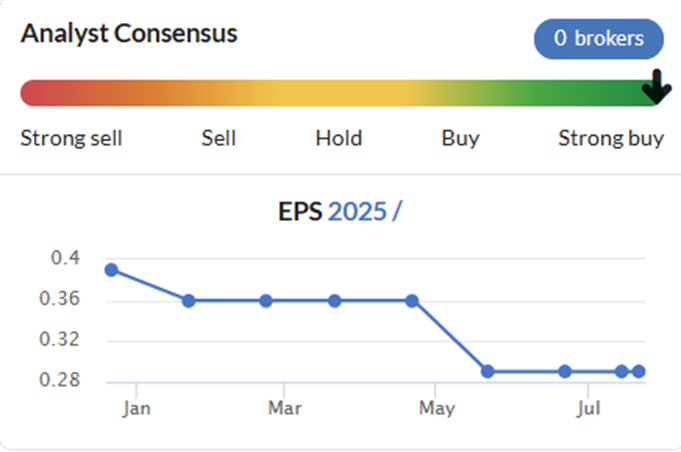
The problem is that they are still highly exposed to Boom Screeds in North America. Their efforts to diversify geographically or in product range are dwarfed by the moves of their main market. Issues with US non-residential construction will always cause a downturn here in the current form. They have been quick to cut costs, and it is clear that they have significant flexibility here. However, this cannot fully offset the downturn.
At the AGM in June, the company said:
The Board continues to expect full-year revenue, profitability, and cash generation to be in line with the revised guidance issued in the 24 April 2025 trading update. Since that announcement, market conditions have remained broadly unchanged. Non-residential construction activity remains steady, underpinned by strong bidding levels and healthy project backlogs, although projects and capital investment decisions continue to be affected by broader economic uncertainty. Looking ahead, the Company anticipates a continuation of these conditions in the second half of the year, while expecting to benefit from a seasonal trading uplift and contributions from new products.
So this sounds in line, but with significant uncertainty on the eventual outcome. We are expecting a further trading update this month. However, they also have no guidance for FY26. It feels like this one could go either way.
Water Intelligence (LON:WATR)
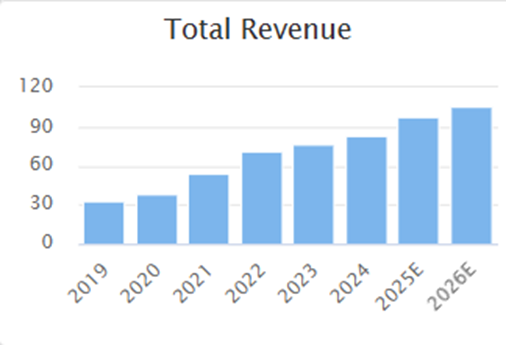
I picked Water Intelligence as my "Growth" stock in the "12 Stocks of Christmas" article series. This company has exactly the type of high, consistent revenue growth of the type that shareholders typically like:
However, the shares have not captured investors' imagination this year:
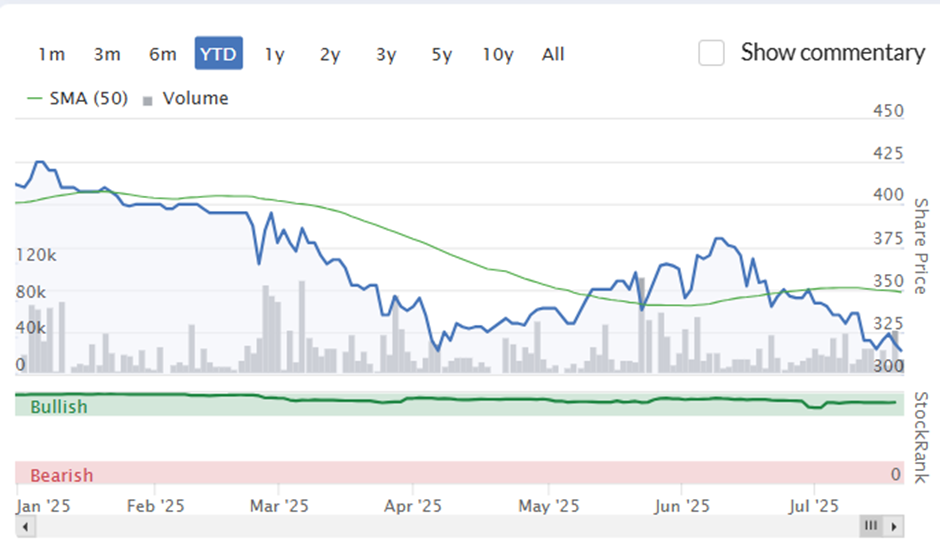
This means that they are on a very low earnings multiple for a growth stock:
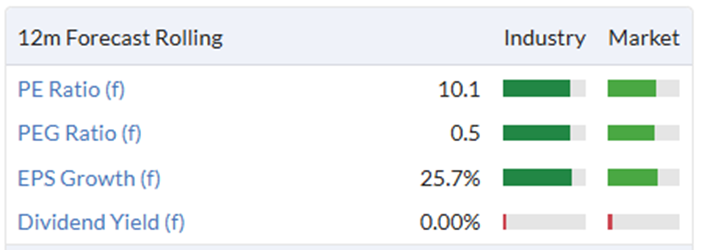
Part of the problem is that the growth in revenue has not translated into EPS. 2024 EPS was at the same level as 2021. The cheap forward multiple is based on them hitting their forward estimates:
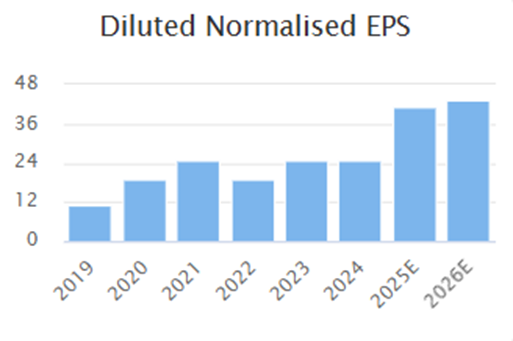
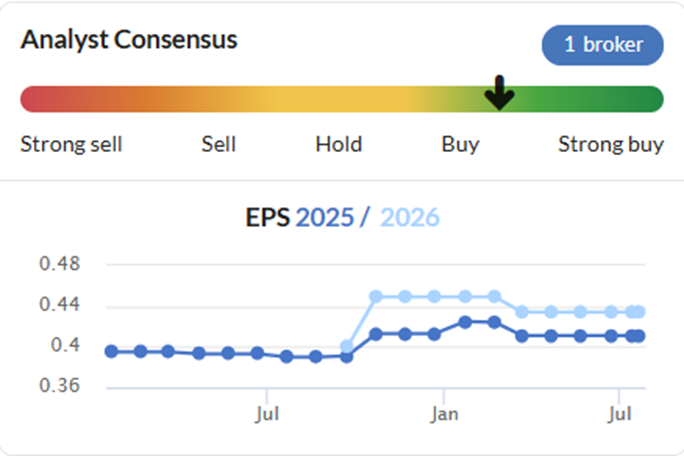
The EPS trend is a little variable and may cast some doubt on that:
What definitely isn't a good sign is that the company waited until the last day before suspension to issue their audited results to 31 December 2024, getting them out on 30 June. While the company is cash-generative at the operating level, they consistently spend significant sums on intangible assets and buying back franchises:
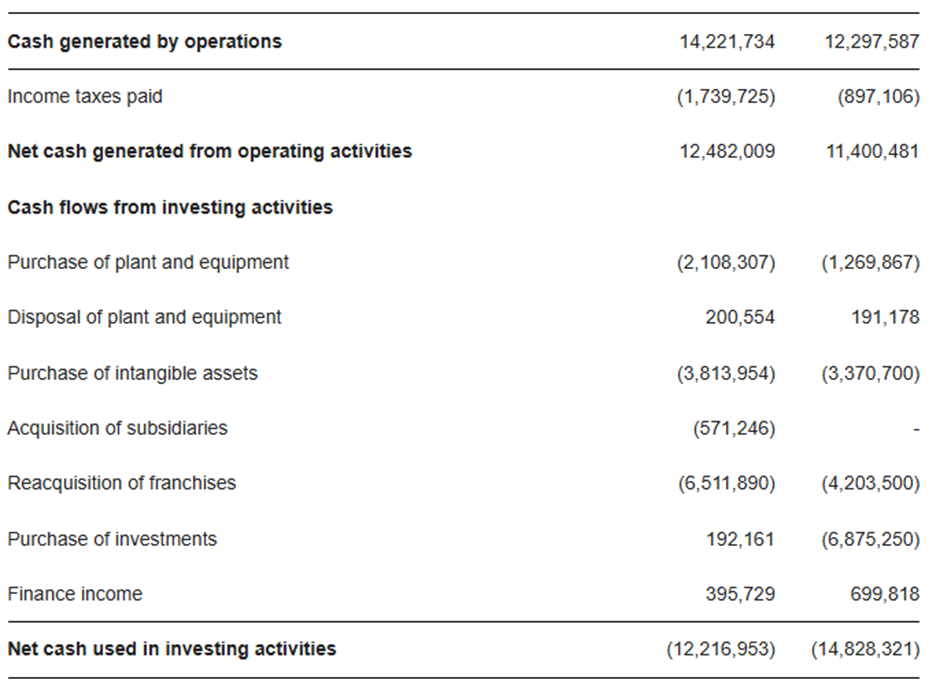
It begs the question – why franchise in the first place if you then spend cash buying them back?
In terms of outlook, they said:
2025 Outlook. The Group's TES platform enables it to be a leader in providing recurring Preventive Maintenance solutions as opposed to reactive one-off Restoration solutions for water loss. The Group is now able to efficiently offer to all customers - residential, commercial, residential - proprietary, technology-driven solutions to wirelessly monitor pipes, collect and analyze data, schedule and dispatch via Salesforce its trained professionals to deploy proprietary minimally invasive leak detection and repair solutions and then provide subscription-based aftercare and follow-on products via video commerce. Based on its Next 50 competitive strategy of Preventive Maintenance and application of its Dallas Template to operations, the Group is excited to deliver for its shareholders a higher organic revenue and profit trajectory.
Sadly, this doesn't contain any statement on whether they are actually in line with expectations or not. If they are, then this could bounce strongly.
Billington Holdings (LON:BILN)
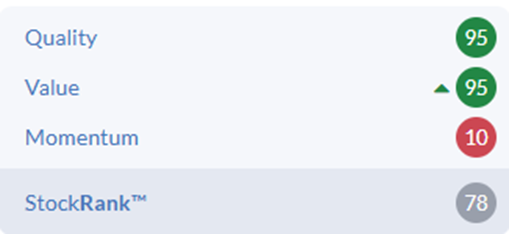
This is another one of my "12 Days of Christmas" stocks. This time, Quality. The Quality Rank here is very high.
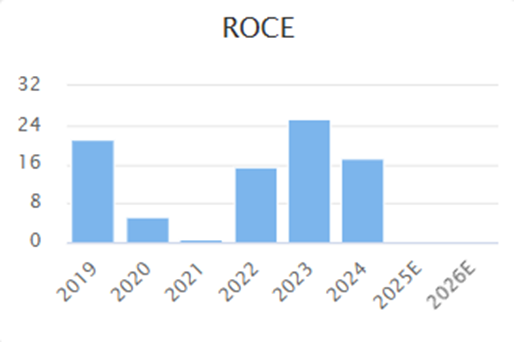
This is due to a decent return on capital:
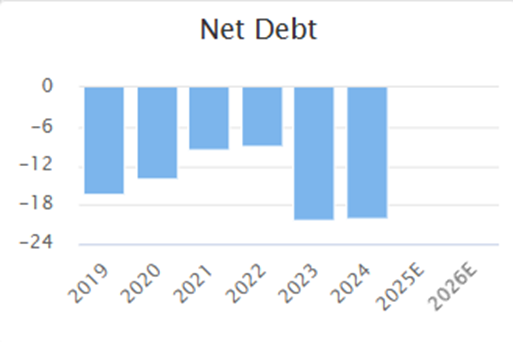
And a rock-solid balance sheet including significant net cash:
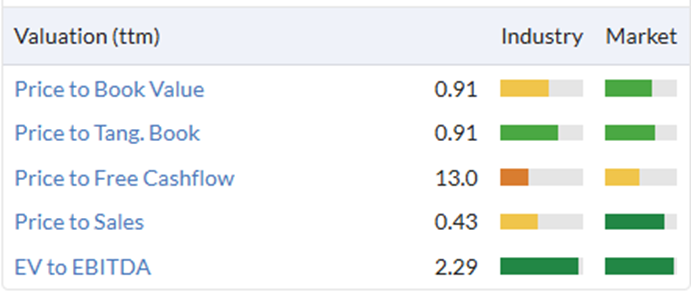
It is rare to be able to buy such a stock below tangible book value, as such metrics usually indicate assets that are unproductive:
Instead, the issue seems to be the recent downgrade in forecasts:
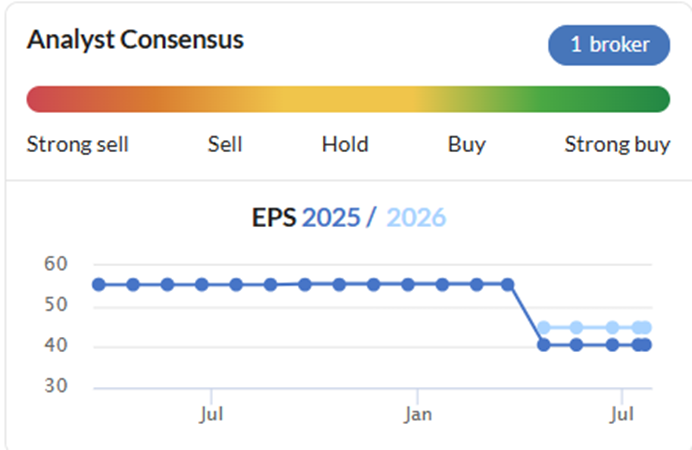
The issue seems not to be demand for the company's products, where they retain a strong order book, but pricing pressure and delays due to the UK government spending review. They say:
The Group has a strong level of contracts secured for delivery during 2025 and into 2026, combined with a significant pipeline of opportunities. However, the overall reduction in industry demand is leading to pricing pressure, particularly as competitors look to secure work to contribute to fixed overhead recovery, and the precise timing of certain projects remains uncertain. Despite these challenges Billington remains extremely well positioned within its industry, with a strong balance sheet, strong product offerings and an ability to weather downturns in a way that many of its peers cannot.
Their long-term track record backs this up:
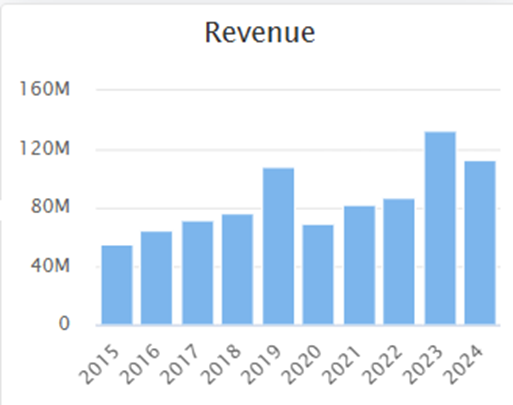
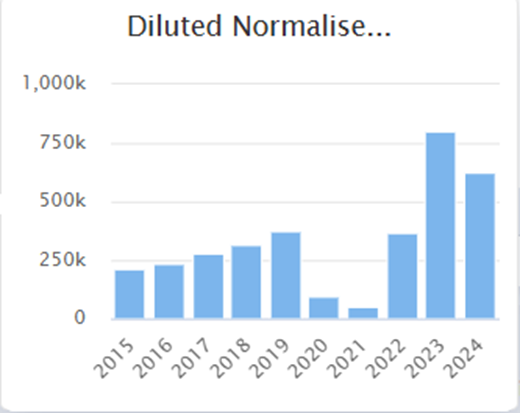
While there is undoubtedly a cyclical element to their trading, a forward EV/EBITDA of around 3 looks far too low for this quality of business.
Brickability (LON:BRCK)
Brickability has seen a modest bounce recently, but it also didn't appear to sell off when other stocks did in April:
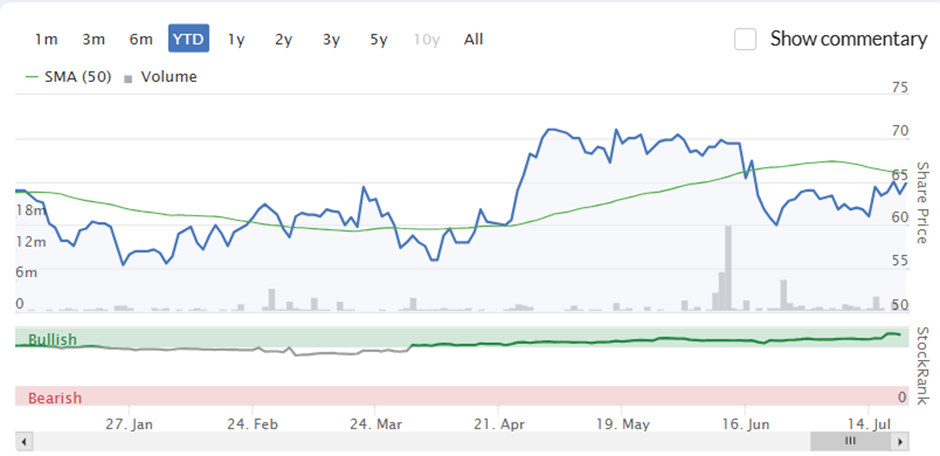
The low P/E perhaps meant that investors were happy to look through wider market troubles:
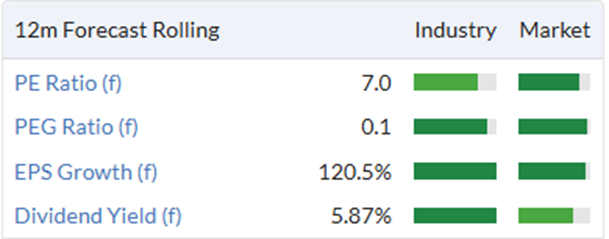
And this was despite broker downgrades earlier in the year:
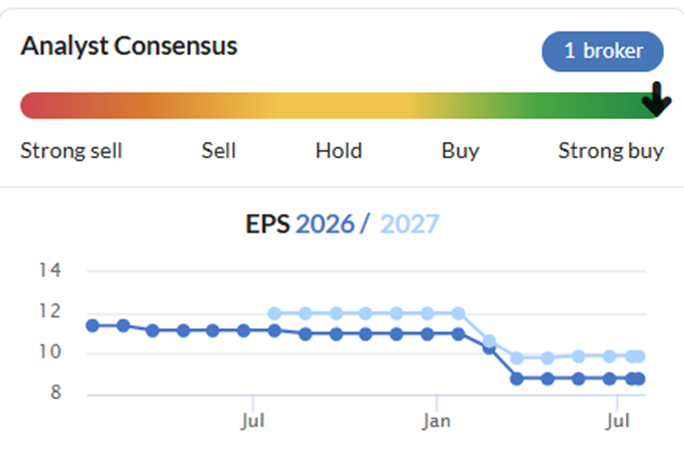
That low valuation also requires a big jump in normalised EPS in 2026:
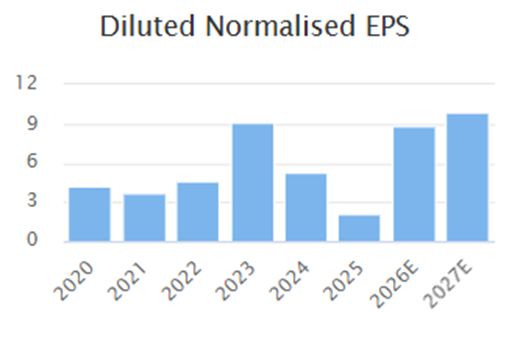
However, it is worth noting that the adjustments done by Stockopedia's data provider don't match those done by the company themselves:
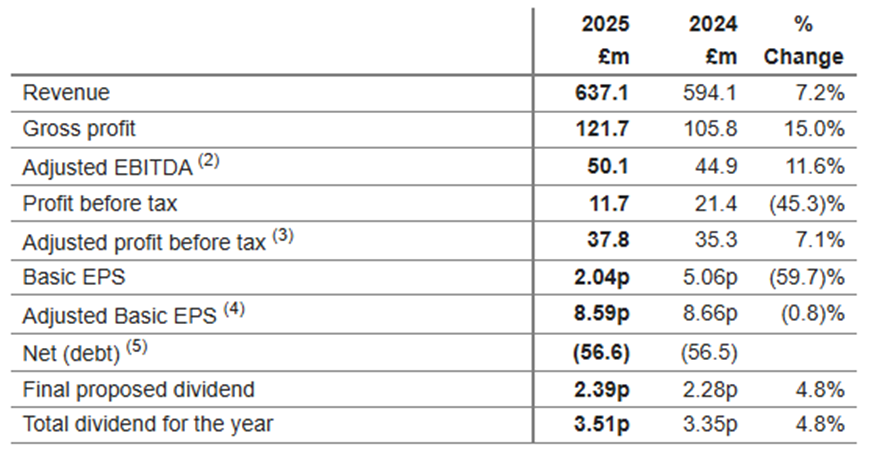
When the differences between statutory and adjusted EPS are large, it is always worth checking these, but here I see these are largely intangibles or accounting for variations in contingent consideration on acquisitions, so these mostly look reasonable to me.
In terms of outlook, there appears to be nothing to worry about at this stage:
• Trading in the current financial year to date is in line with management expectations…
• Well-positioned to benefit when end markets improve given the significant operational gearing
This looks like a good candidate for a continued bounce to me.
Extractive Industries
Goldplat (LON:GDP)
This has been a frustrating hold for me. The value metrics here make this gold recovery company probably the cheapest UK stock overall:
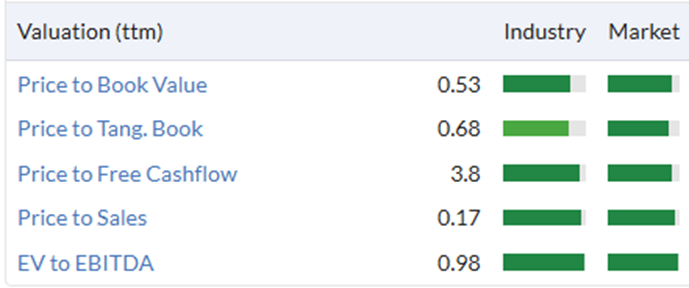
Some would say this is justified, given the risk of operating in this sector in Africa. However, this is a more stable company than the average gold miner as it processes the mine waste from others, so it doesn't have the mine risk. The lowly rating isn't because the assets it has are unproductive, either:
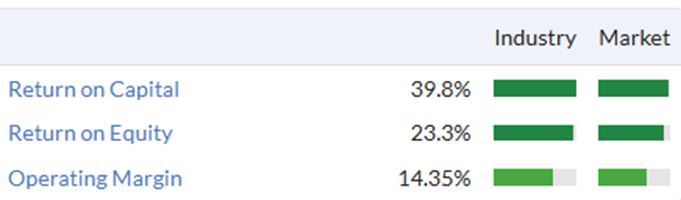
On top of this, it has a gold resource consisting of its old tailings dump, with the contained gold worth over £300m. It wouldn't take much of a recovery percentage or profit margin to move the needle on an £11m market cap.
The issues are that shareholders don't feel they are benefiting (or will benefit) from any success here. The key metric for many is this:

Part of this is that there have been several requirements for short-term capital, for example a shift in the requirement for the company to produce its own gold bars not gold concentrate in Ghana. But while the company is unable or unwilling to return capital to shareholders, many are sceptical about management intentions here.
The second issue is that, while there is no doubt that the tailings reprocessing would generate material cash flows to the company, progress here has been very slow and is bogged down by permitting approvals. While there may be significant undervaluation here, any potential for a short-term bounce is likely to be related to whether the company declares a dividend or makes material progress on its tailings project. The timing of this is hard to predict.
Pharos Energy (LON:PHAR)
This is another share that appears very cheap on a number of metrics:
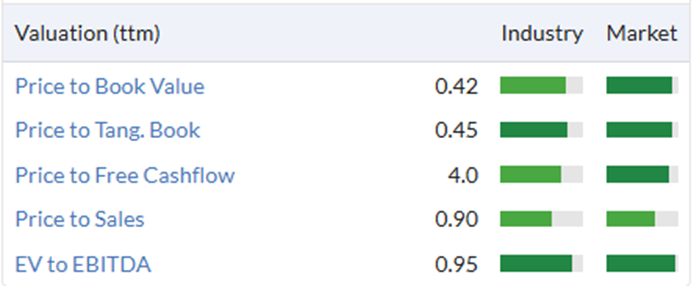
However, I must question the relevance of Tangible Book Value for an oil company, where the bulk of its assets are oil-producing infrastructure in far-off lands. EV/EBITDA is not always a good metric for capital-intensive businesses. It is noteworthy that the P/E is not particularly low for this sector:
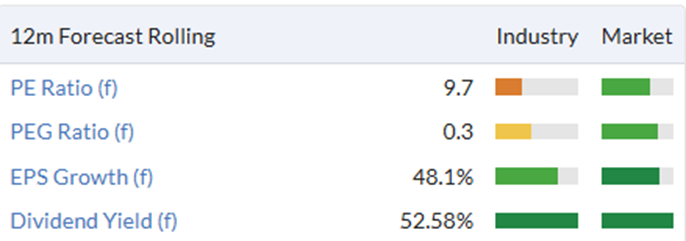
(The forecast dividend appears to be a data error from Refinitiv.)
This company was previously known as SOCO International and was an investor favourite years ago, due to potentially large exploration prospects in Vietnam. These never materialised into commercial discoveries, and the company branched out into the Egyptian market. It was renamed Pharos, reflecting that new direction. However, that strategy was largely a failure, in my opinion. As a recent trading statement shows, the company's producing assets are still dominated by those legacy Vietnam fields of CNV and TGT that started production in 2008 and 2011, respectively:
o Vietnam 1H production 4,183 boepd. Vietnam FY25 production guidance 3,600 - 4,600 boepd net
o Egypt 1H production 1,459 bopd. Egypt FY25 production guidance 1,400 - 1,600 bopd
This has led to largely flat revenue:
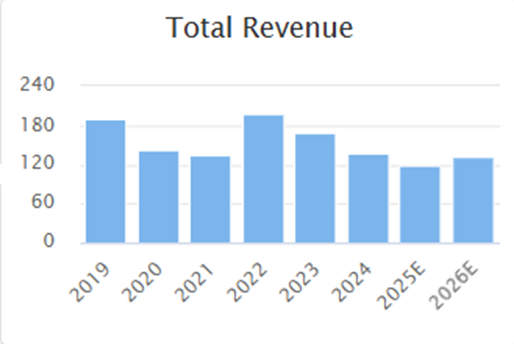
Overall, then I see little to suggest that this company is particularly good value or due a bounce, unless the oil price is unusually strong.
Power Metal Resources (LON:POW)
This is a type of incubator fund, and as such, most of the usual metrics value investors use tend not to apply. The key one is how the fund compares to its assets:
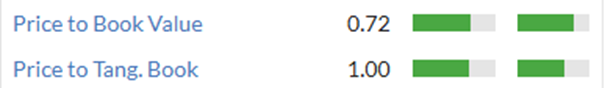
This isn't particularly attractive, as most of the holdings will be marked to valuation models rather than traded prices. The share price has shown a little strength recently:
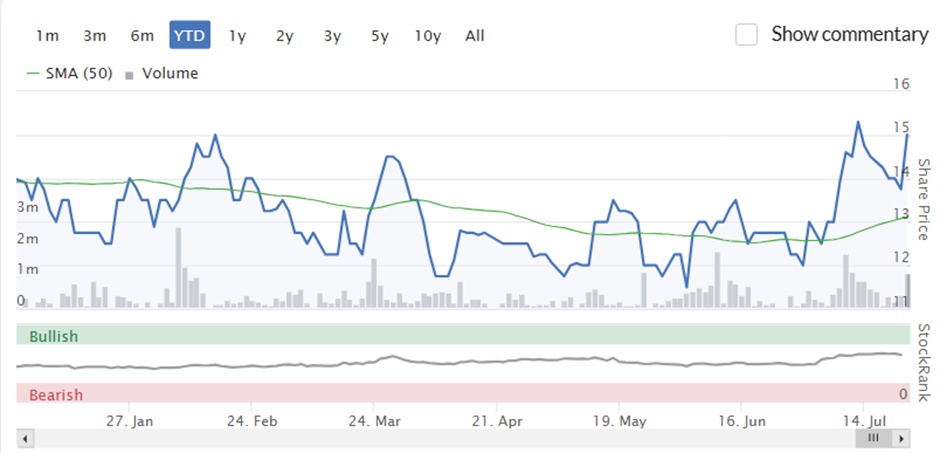
Presumably due to the announcement that one of their investments is about to list on AIM, hence provide a more accurate read-through valuation. However, this looks best left to specialist investors who are capable of valuing the underlying holdings more accurately.
Others
FDM (Holdings) (LON:FDM)
FDM is a sort of consultant factory. It hires, trains and then deploys IT and business consultants to clients for local or remote work. The share price has been in an almost continuous downtrend since small cap shares peaked at the end of 2021:
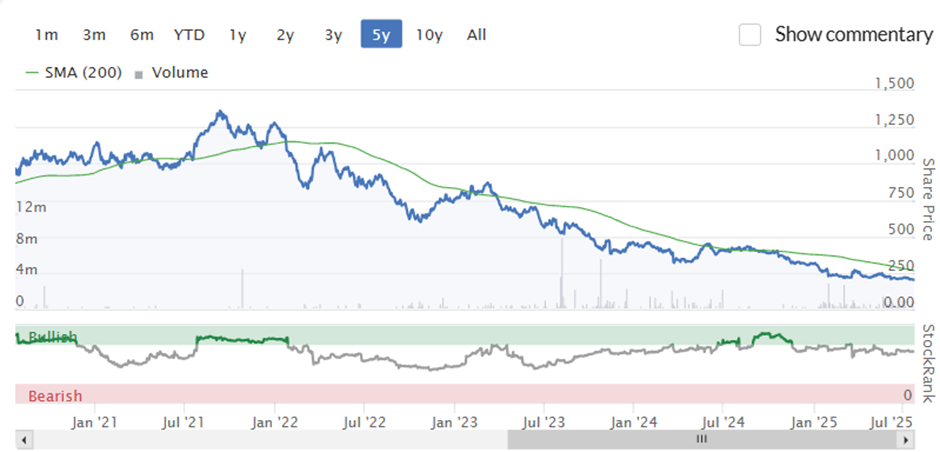
This shows how much sentiment actually matters to Stock market pricing, as at the peak this was on around 40x forward earnings. Today it trades on 11.7x forward earnings:
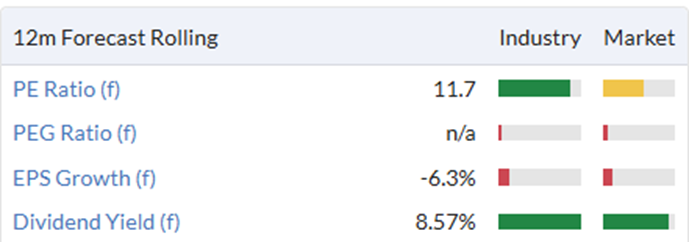
If we assume this is a cyclical business, then this is the P/E on trough earnings, too:
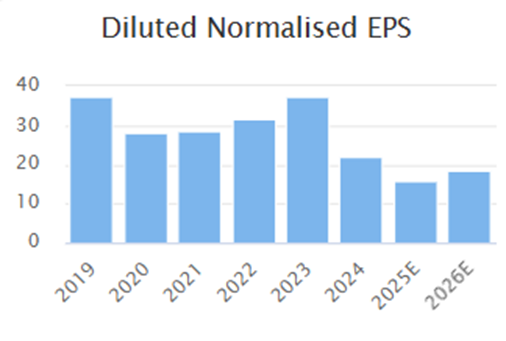
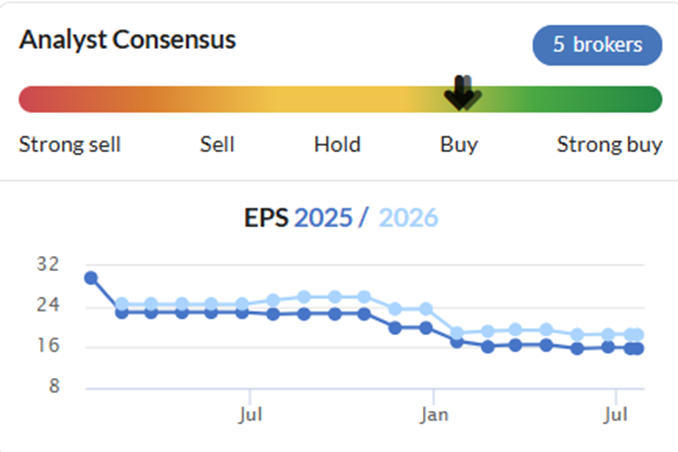
The earnings trend is not encouraging, but there have been no major downgrades recently:
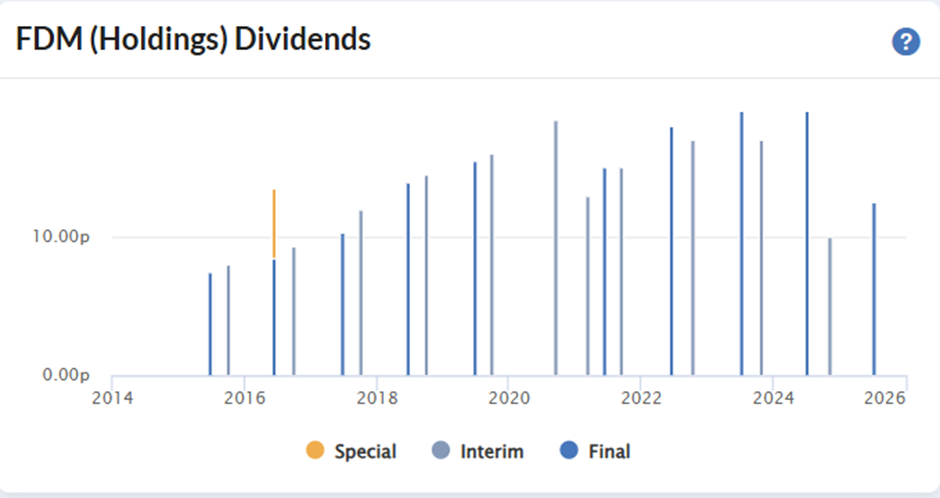
This has always been a highly cash-generative business, as the high dividend yield shows. There is around £19m of net cash on the balance sheet, which demonstrates financial strength. However, this is not enough to really move the valuation needle on a £220m market cap company. However, it is worth noting that the dividend pay out has been cut recently:
Despite a really good ROCE, I'm not sure this is a great business:
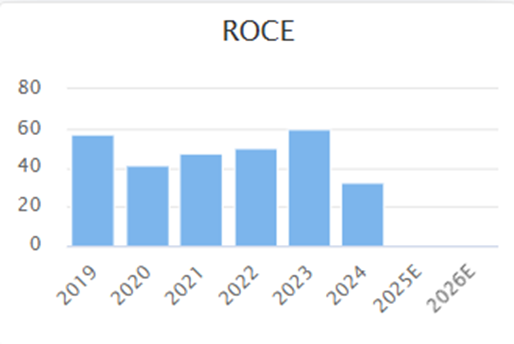
The reality is that it is a people business, and you can easily see that successful, fully-trained consultants will be looking to capture all of the returns for themselves by going it alone. The assets walk out of the door every night, and regularly during the day!
At their AGM, they gave the following trading update:
Trading in the first quarter of 2025 was in line with the Board's expectations.
We reported in our Preliminary Results announcement on 19 March 2025 that, while trading in the early part of 2025 had been encouraging, the Board considered it too early to increase investment in recruitment for a recovering market. Since then, global macroeconomic and geopolitical uncertainty has continued, together with hesitancy amongst some of our customers as they await clarity over USA economic policy.
At 30 April 2025 the Group had 2,366 Consultants assigned with clients (31 December 2024: 2,578. 30 April 2024 3,543)
So quite a bit of uncertainty. This also shows the scale of the reduction in consultant numbers that they have had to make.
The last material buy was made by the CEO in March at £2.53. However, since then, the only other directors' share trades of note have been the exercise of nil cost options and subsequent sale of shares to meet tax liabilities. This perhaps suggests that directors don't see a quick reversal in outlook:
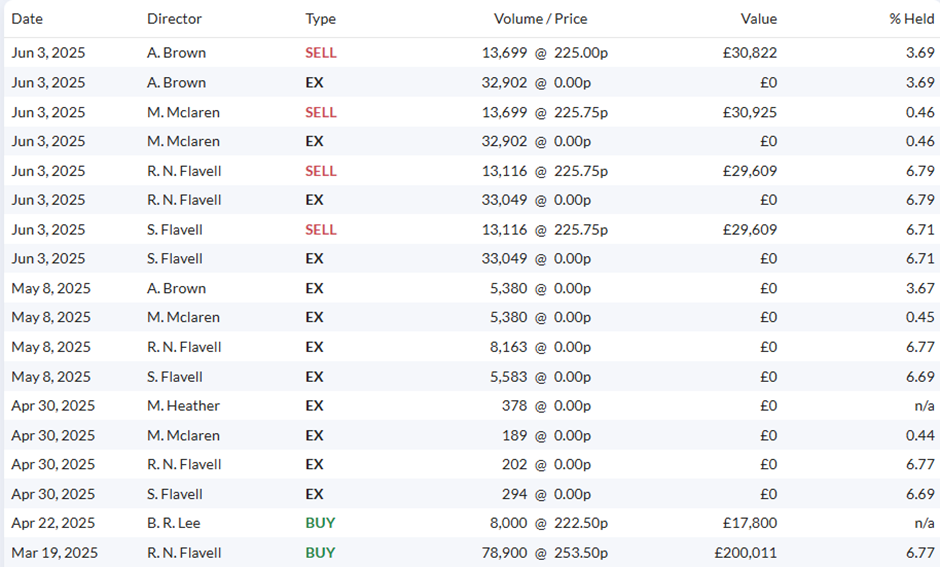
It would seem that given the cash flow and that this is on a modest multiple of what may prove to be trough earnings, that any recovery when it comes could lead to a significant rise in share price. However, it is going to be hard to judge when this is.
Tissue Regenix (LON:TRX)
This stock appears to have already had a very recent bounce:
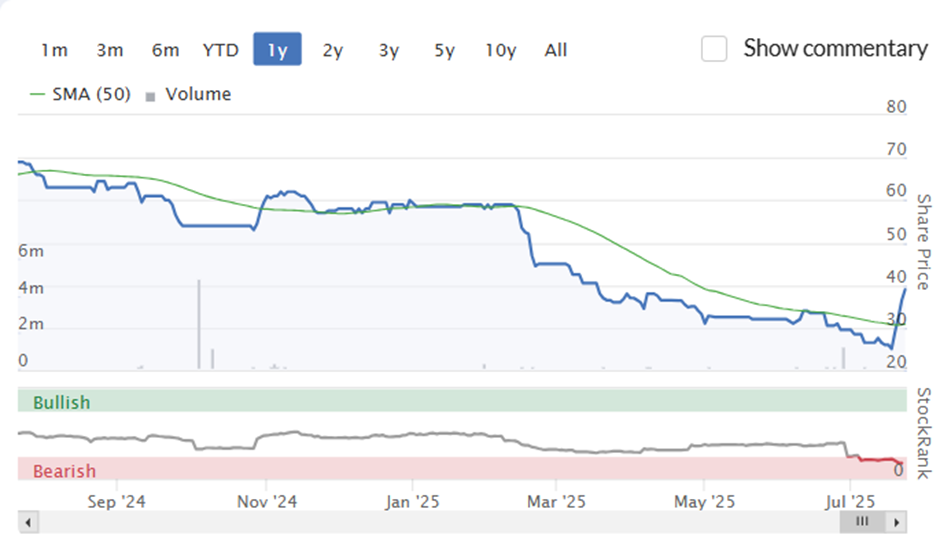
And given that the Value Rank is now below 70, which was my screen cutoff:
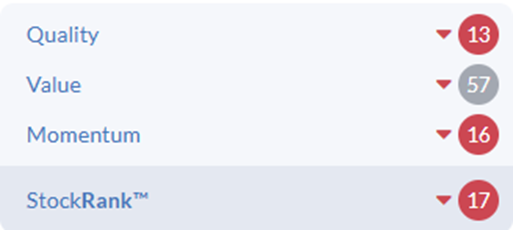
And it is continually loss-making:
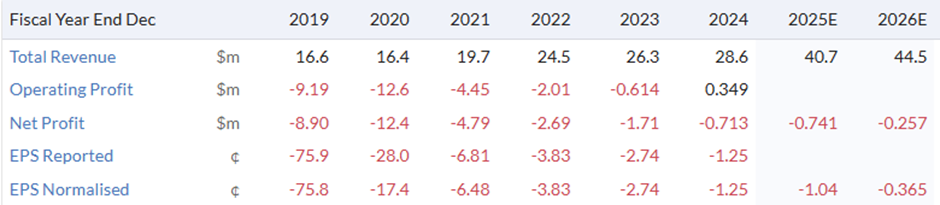
I won't look into this one any further.
S4 Capital (LON:SFOR)
This is another company with a huge fall from grace:
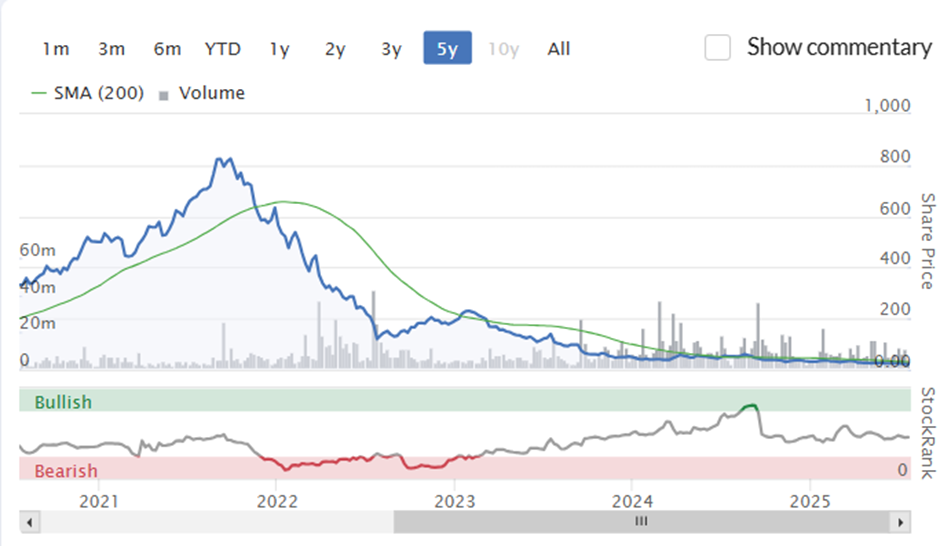
I have to zoom in to get an appropriate scale to judge this year:
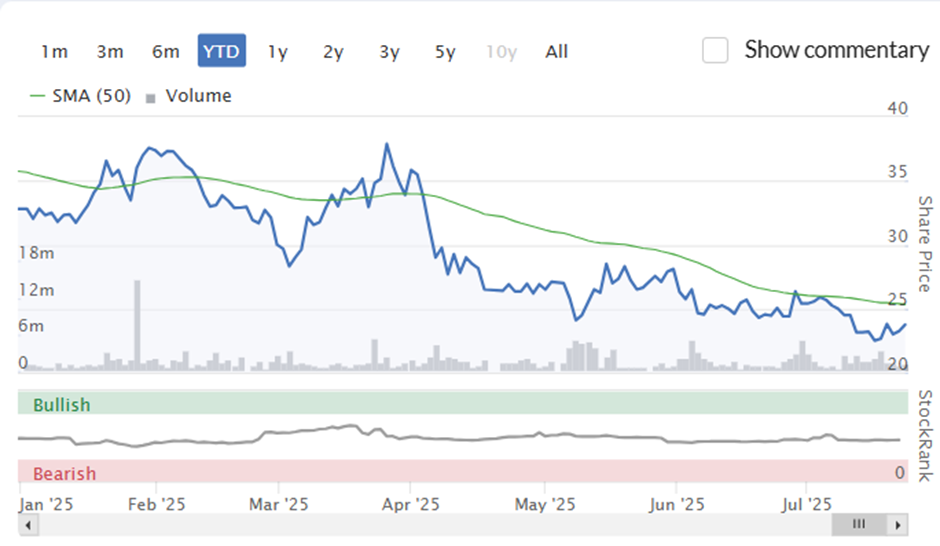
If market forecasts are correct, then this has been sold off to a very cheap multiple of forward earnings:
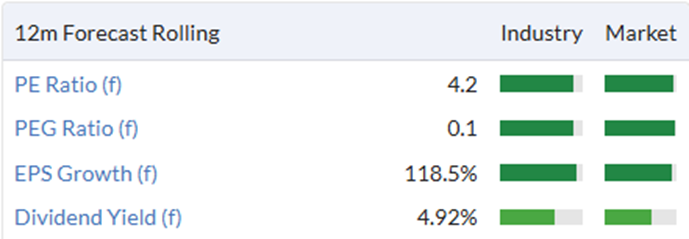
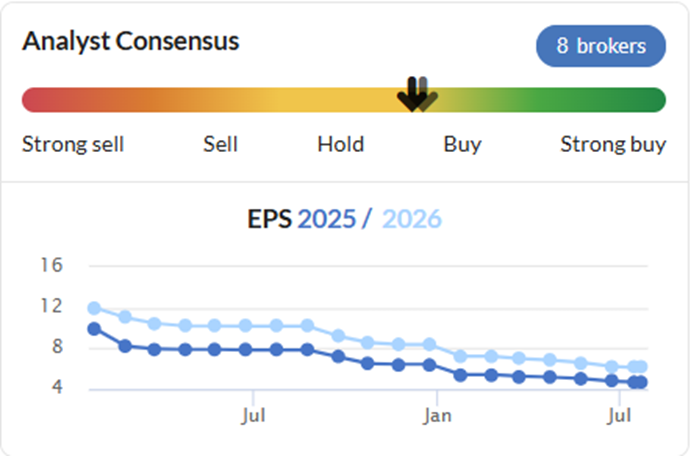
However, how much confidence we should place in a company where the broker trends look like this is questionable:
The real issue, however, is that the company has taken on a large amount of debt in an attempt to scale their business:
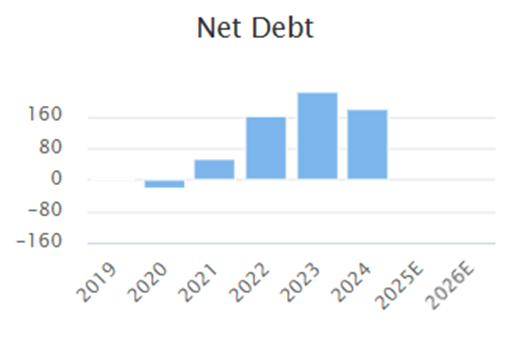
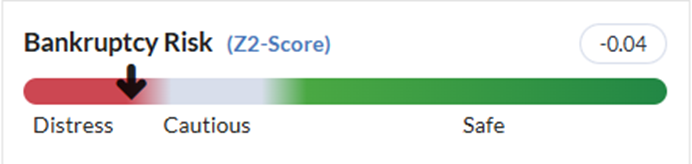
Given that net debt is slightly larger than the market cap, a simplistic view would say that we double the stated P/E, which then, at around nine, doesn't look great value for this sort of people business. There is a high chance that this is close to trough earnings, though. More worrying is that the debt means that this is flagged as in distress:
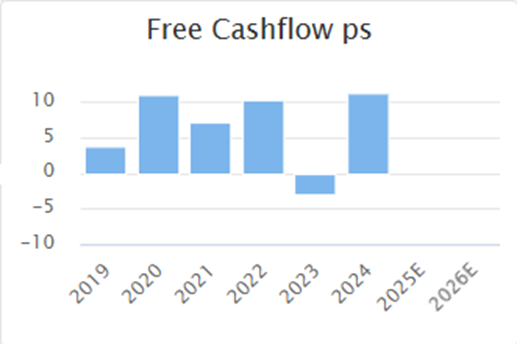
However, even though the EPS has been pretty variable, the cash flow is fairly consistent and strong:
In the company's 4th June AGM statement, they said:
Liquidity continues to improve with month-end average net debt in the first five months of the year down almost 30% from £199 million to £144 million underpinning the Board's confidence to recommend a first time final dividend of 1p per share
This show of confidence may mean that things are now looking up here.
Synthomer (LON:SYNT)
Specialist polymer producer Synthometer is another company that has seen its share price completely collapse over the last few years:
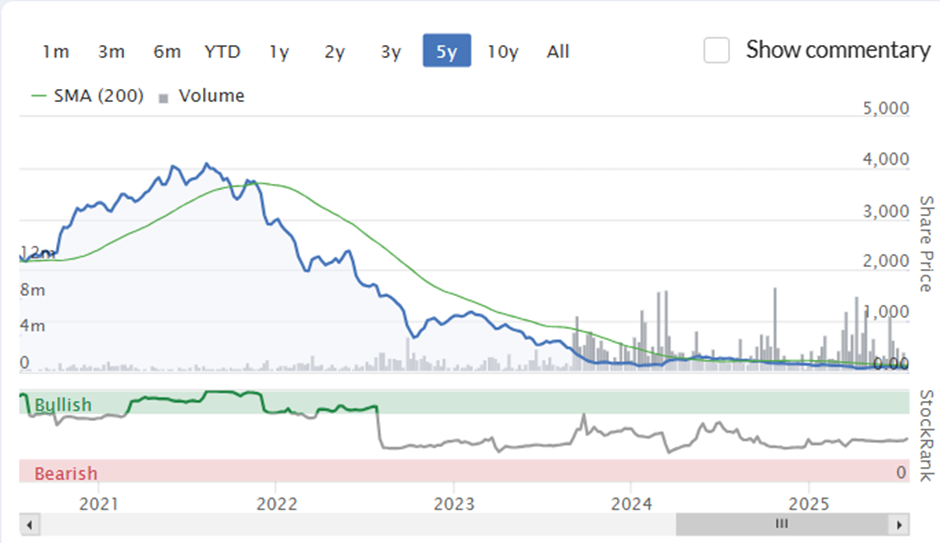
It seems that no matter how well they recover in the future, they will never reach previous heights as they have had a rights issues and divested themselves of many non-core businesses along the way.
Despite this, the company is still heavily indebted, debt makes up the majority of the capital structure at the moment, and their latest announcement is a covenant waiver:
…has agreed with its banking syndicate to extend the period of covenant relaxation through to, and including, the end of 2026. Given weaker macroeconomic conditions than anticipated at the last amendment agreed in March 2024 and heightened geopolitical uncertainties, the extension provides the Group with a longer period of additional headroom to manage the business through to the expected recovery in earnings in the medium term.
Following the agreement, the net debt:EBITDA covenant ratios required under the Group's Revolving Credit Facility and the UK Export Finance facilities have been increased from not more than 4.75x in December 2025, 3.5x in June 2026 and 3.25x in December 2026 to 5.25x, 4.5x and 4.25x respectively. While the Group expects to be within the 5.0x ratio previously required in June 2025, for prudence this has also been extended by 0.25x.
Part of the issue is that the earnings estimates have continuously trended downwards for over 18 months, and are now at barely break-even:
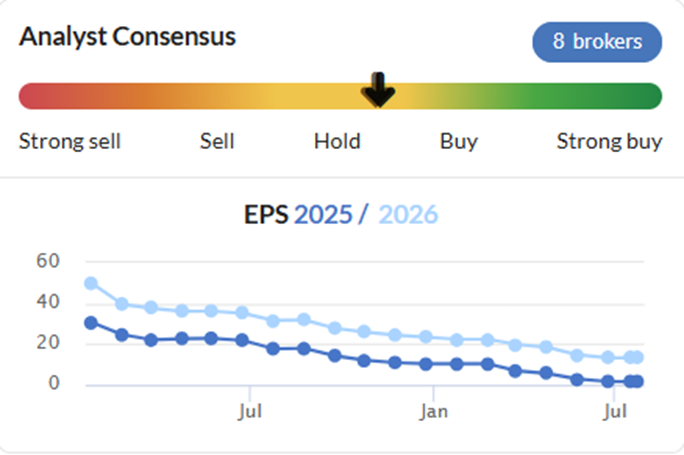
Despite this terrible history, there are signs that there may be some value lurking. Most notably, the slight discount to tangible book value, which is unusual for a business with this scale:
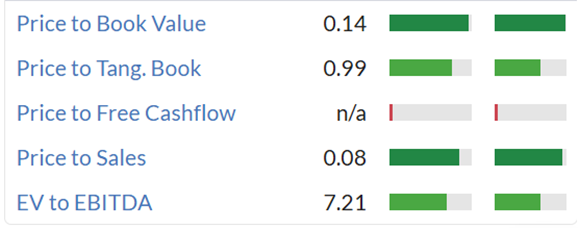
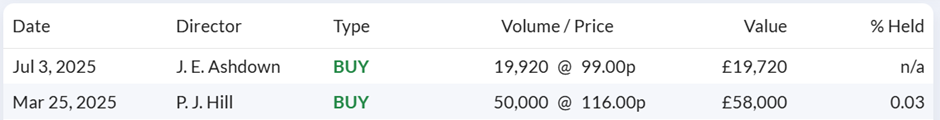
The leverage makes this very risky, and it should never be a large part of anyone's portfolio. However, leverage works both ways and can lead to a rapid re-rating if trading improves. There are signs that the directors may be starting to see value, with the first buys since the rights issue in 2023 occurring this year:
Summary
It is understandable why almost all of these stocks are trading close to their 52-week lows. Many have seen continuous downgrades in their earnings. Others may not have had recent negative news but have not produced a detailed trading update for some time, such as Strix (LON:KETL) or Water Intelligence (LON:WATR) . The direction of near-term news is hard to predict, so has the capacity to make investors look like fools or geniuses, especially for the more highly leveraged plays on this list. When judging whether companies have been unfairly sold off, I think one also has to consider issues of valuation. Billington Holdings (LON:BILN) Goldplat (LON:GDP) look cheap on both tangible book value and earnings, and it is probably unsurprising that I hold these. Water Intelligence (LON:WATR) S4 Capital (LON:SFOR) Synthomer (LON:SYNT) FDM (Holdings) (LON:FDM) KETL Brickability (LON:BRCK) and Somero Enterprises (LON:SOM) are cheap on some metrics, and the market may well have over-reacted and sold these off to unreasonable levels. However, all these have risks associated with them. They are certainly worthy of inclusion on my watchlist (if they aren't on there already), and I will be watching them closely for signs of a turnaround gaining traction or other good news.
[Disclosure: Mark holds Billington Holdings (LON:BILN) Goldplat (LON:GDP) ]
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

10 comments
Mark. Great piece of work! For Water Intelligence (LON:WATR) you ask "why franchise in the first place if you then spend cash buying them back?" I have asked myself this question before and never arrived at a clear answer. I can only speculate on potential answers. It could be that they let the franchisee take the risk of starting the business, and they only buy it back if very successful. How does the cost of buying back the franchise compare to the cost of selling it in the first place? Can anybody else with a deeper understanding of the situation answer Mark's original question?
I sold in April after having questioned for some time where the cash and profits are going and why the ROCE is so stubbornly low: I had initially come to the obvious conclusion that all the profits go into the franchise acquisitions and that these are value destructive. I then spent a short amount of time thinking about why a company might continue to do this over time. Then I sold out.
Correction - was actually May 27th
Should this type of investing be avoided by new investors of unhealthy companies and negative trending eps performance?
Majority of these companies will continue to be in this position unless a massive catalyst to change their fortunes either government policy, economic change or mega fund raise c/w a top ceo / cfo instated.
Why in the UK we encourage this style of investment as many factors against new investors
thanks Marks, very interesting article.
I also hold a small amount of Goldplat, and have held for years, because they always look cheap - maybe a "value trap" as Stocko calls some shares
Hi DVB99,
Thanks. A share price going nowhere for a long time isn't necessarily a sign of a Value Trap IMO. For example, prior to the rise in the last couple of years, Warpaint London (LON:W7L) 's share price was largely static for the first 6 years as a listed company. Investors who saw that as a sign of a poor business model (including myself) missed out on a 6-bagger due to a lack of patience. Instead, I see a value trap as the sort of business which trades at a big discount to TBV, but that losses keep eroding the the book value and the discount stays the same so the price goes down, but the value investor keeps invested as the discount to TBV makes it still look cheap. The value traps them in a declining business. This isn't the case with Goldplat (LON:GDP) , as their book value has been increasing:
Here the issue is that the majority of shareholders or prospectve shareholders don't want the company to be re-investing capital, because they fear that that investment may be wasted. Instead they are looking for signs that the strong returns of the business will be returned to shareholders. To turn things around, management need to convince shareholders that this will happen.
Cheers,
Mark
I used to own Water Intelligence (LON:WATR) earlier this year, but sold after they published their YTD Apr trading update. You can back out that that YTD EPS to Apr is 11p, which is 2.82p per month. Broker estimate is FY EPS of 44p, which means they would have to get to a monthly EPS run-rate for May-Dec of 4.1p, which is an increase of over 40% vs. what they have achieved YTD, despite H2 normally being the slower half. I therefore think this will warn on profits in H2 and see further SP decline...
Certianly a risk when something has a strong H2-weighting. Personally, I struggle with getting my head around all the franchising and de-franchising, and basing the valuation on forward earnings. However, the long-term revenue growth track record is great and I think that does give it long-term potential for those who are better at valuing/more comfortable with growth stocks.
Hi Mark - really interesting article to get some new ideas for potential bounces. On Power Metal Resources (LON:POW) I keep it simple and think this is undervalued just based on the cash at hand, which pro forma for the sell down of part of their stake in Guardian Metal Resources (LON:GMET) earlier this year, should be ~£6.7M. Add to that their remaining stake of 19.4% in Guardian Metal Resources (LON:GMET) at a 14% ABB discount (that's the same discount as in the H1 placing) and you get to a TP of 19p vs. currently SP of 15p. On top of that, you get all the other investments they have for free.
Hi Nurzel, thanks.
Marking to market underlying holdings is certianly a good way of doing it nad you are right it may indicate some upside value from here. The problem I have is that I have no idea if Guardian Metal Resources (LON:GMET) is undervalued or overvalued and that is a fair chunk of the read-through. However for those who want Guardian Metal Resources (LON:GMET) exposure, Power Metal Resources (LON:POW) looks a cheap way in.
Cheers,
Mark