#7 - Marston’s - from debt to dividends

This is #7 in our "Twelve Stocks of Christmas 2025" Series. You can review the full set here.
The Pitch
Marston’s (LON:MARS) is now completely focused as a pub operator (1,300 pubs), having sold its brewing operations (Pedigree and Hobgoblin) to Carlsberg in 2024. On first glance, it seems another debt-laden, ex-growth, “cheap for a reason” stock. But a trading statement in October with “free cashflow significantly ahead of plan” has triggered a re-rating. Debt paydown is happenting at pace, store refurbishment returns are impressive, and shareholder returns may soon be on the cards. If so, and at a StockRank of 97, the shares may be significantly underpriced.
The Big Picture
Marston’s over-expanded when debt was cheap. Lenders happily lent because loans were asset backed - across both brewing and pubs. But COVID hit at peak leverage and cashflow disappeared. Since then management have shown operating discipline, selling the capital-heavy brewing business, and focusing on the higher return pub estate. It’s working.
- Debt is shrinking by design - the business has securitised its debt, which is on a payment schedule. This enforces management discipline, as they have to hit repayment targets.
- Cashflow has crossed a line - improving profitability (+71%) and margins (at 23%) have pushed free cashflow to £53m, well ahead of the £44m fixed debt payments.
- Value is shifting from debt to equity - this is key. As debt is paid down, the business should generate more and more free cashflow to equity. Marston’s last paid a dividend in 2019. If dividends are reinstated, as expected within 18 months, expect a new shareholder base to aggressively buy the shares. It seems some already are.
Going Deeper
Marston’s is now a far simpler operation having exited brewing. Revenue growth is not the primary goal, financial resilience is. Nonetheless, the business is showing skill at implementing their strategy and sweating assets.
- Refurbishment is working - management upgraded 31 pubs in the last year across three smart, localised concepts - “Grandstand” focused on big game sports events, “Woodies” which appeal to families, and “Two-Door” which target drinkers and diners. These upgrades drove 23% revenue increases at a 30% ROI at the venues.
- Disciplined rollout - 50+ refurbishments are planned in 2026, with capex at up to 7-8% of revenue. Importantly, this is funded from cashflow, not new borrowing.
- Doing digital right - Simple things work well - a new “order & pay" platform launched this year which increased spend per guest by 10%, while other wifi/till investments are working
- Small operator pain is Marston’s gain - business rates are increasing, people are drinking less and small operator pubs can’t keep up. Ironically, when demand is falling in an industry, the survivors can increase margins as sub-scale operators exit. Management expects margins to keep rising this year.
What the Brokers say
Marston’s is not widely covered, with only Panmure Liberum notes available on Research Tree. Nonetheless, their leisure sector analyst has Marston's as one of their top three picks for the year.
- Target price - 80p - 35% above the current 59p. This is backed by an NAV (net asset value) of 125 pence per share. The strong asset backing of the company's bricks and mortar estate puts the business on a price-to-book ratio of only 0.47x.
- Upgrades - the broker left their numbers unchanged in the latest update but reiterated their buy rating. I prefer to see upwards earnings revisions, but I'm comforted by the "significantly ahead" announcement the company made against their own internal expectations in October.
The Bear Case
Marston's no longer seems to be living on a quarter-to-quarter basis, but there are always risks, especially in the pub sector, so we can't look past these entirely.
- Execution matters - Management may have chosen the best sites for early refurbishment, and customer excitement may fall, so the early numbers may fade.
- Sector headwinds - Even the best-run pub groups are facing pressure from weaker consumer demand, especially amongst young people who aren't drinking as much.
- Cashflow has to hit plan - The business is still highly leveraged, and any wobble or miss of the repayment plan will slow debt reduction and create concerns for equity holders.
The Bottom Line
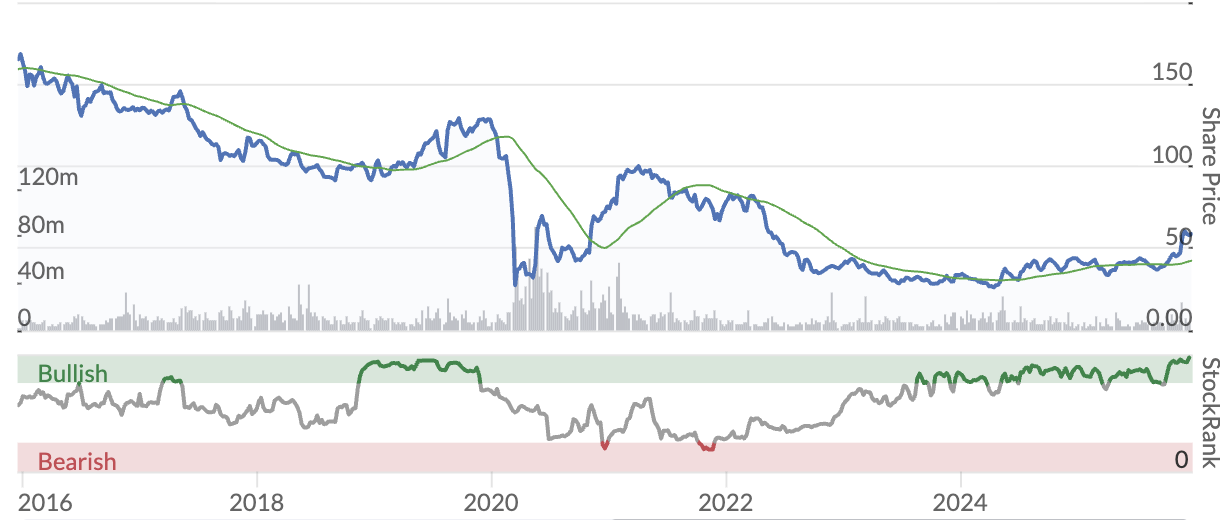
Throughout this year, we've been researching the power of "ahead of expectations" announcements, especially in value stocks. Could the October update have marked the bottom in Marston's and triggered the start of a new uptrend? The long-term share price chart looks like a bowl, and it’s second-highest ranked "value and momentum" share in the UK stock market. Marston’s is now a simple pub business generating real cash, paying down debt on schedule, and promises a future of potentially higher shareholder returns. There's not going to be a straight line here, but it is looking interesting for those with risk-appetite.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

12 comments
https://www.bbc.co.uk/news/art...
Positive article here on the BBC on how the government are 'expected to say it will make changes to how pubs' business rates are calculated, resulting in smaller rises to bills' and 'The Treasury is also thought to be ready to relax licensing rules to allow longer opening and more pavement areas for drinking.'
Probably reflected in the 3% rise today.
how could they get it so wrong in the fisrt place though - it gives one less than confidence if they get it tragically wrong but have to backpedal - if they cared they wouldnt have screwed anyone over in the first place. some may have already closed the doors if they obviously cant cope wiuth ridiculous proposed increases.
If they are going to do an about turn they dont want to fuck around planning it- they want to correct the error like yesterday.
The Treasury is also thought to be ready to relax licensing rules to allow longer opening and more pavement areas for drinking.'
Not sure opening longer is always wanted - since covid councils seem to have massively helped anyway already ref drinking on the pavement - certainly in my neck of the woods . Is this real improvemnt or a puff piece for their labour friend politicians ? where chanages have already been done by many councils ?
the fact that many labour politicians themselves need to go to RR to argue the case show what a shambles it is
to be expected from Socialism, only retreating when the public (potential voters ) protest loudly
i dont like to take sides on politics (dont mind calling out crapness) - i just tend to judge politicians on what they promise and what they deliver - overall other than some stuff thats different at the edges (vat on school fees etc ) - i would be hard pressed to think of much difference for your average person betwen teh two main parties - the conservatives were happy enough to ramp up dividend tax - freeze personal allowances - up corporation tax by 6% - levy double can pickup tax on farmers - increase spending on nhs in real terms - be reasonably fair ref means tested benefits - up spending and taxes as % os gdp.
much of what the conservatives did - had they not been in power to make those decisons they would have been up in arms about saying you are over taxing your average worker and small business blah blah blah
so i see very little of useful difference between the parties and most of what comes out their mouths "we will not tax working people more" is just guff.
in summary i am not convinced one lot are better or worse than the other lot
look at housebuilding - endless promises to have more homes so youngsters arent priced out of the market due to supply demand mismatches - and nothing delivered - will labout deliver 1.5 million homes this parliamt - complete disgrace bearing in mind we have 11 million more people living in the country than we did at the turn of the millenium - whatever nimbies and evironmentalists may want - its super obvious for your average person building affordable housing NOW to catch up should be like number 2 priority for any party in charge
Your right they are all as bad as each other
i think its nice to have something everyone can agree on - if its a little bit sad :)
There was a small piece on Marstons in the most recent MoneyWeek magazine. "Christmas bookings were up 11% on last year's levels at the end of November".
I also conducted some serious research over Christmas break, spending a lot of time in pubs purely for research purposes. I would say that they were as busy as ever, especially with work events.
Now, that's commitment!
Marstons (LON:MARS) Surely the World Cup will have a beneficial effect on cash flow over the coming 8 months.
This wins easily against Fuller Smith & Turner (LON:FSTA) and J D Wetherspoon (LON:JDW) when using the 'compare with' tool but would appreciate commentary - i.e. human touch - why Marston's chosen against these well known names.
Hi Bohenie,
I suspect the answer lies here: https://www.stockopedia.com/co...
The companies you mention perhaps didn't make the cut...
Marstons (LON:MARS)
marstons has struggled for many years to make any natural progress ref debt - the debt it has repaid is pretty much solely down to sale of the brewing arm - you can only sell the crown jewelse once.
I think its just not as quality a business operationally speaking as the other two historically.
it does seem it a reasonably sweet spot right now though - so i suspect part of the "lower" rating reflects the fact thats its not really delivered as consistently as the other too over time so is tarred with the past sins - of the 3 ref debt i would still think marstons is the highest risk of the 3 debt wise too and that may be a bigger factor.
Ref world cup providing windfall - to events that repeat every 2-4 years regularly add much to the overall company valuation ? probably not - i am not even convinced that a world cup in the USA helps much - eg if you look at Scotlans fisrtg 3 games (no witty jokes please) - they are 11pm , 11pm and 2 am - ok a bit of extra revenue perhaps but probbaly more hassle soting out extra opening hours than anything else. With stuff likle this one years tailwinds and next years headwinds too !