A Primer on Covid-19 testing in the UK (Part 2)
The promising vaccine news from Pfizer earlier this week has been welcomed by global financial markets, but has inevitably also impacted certain segments of the market, notably Covid-19 testing stocks. Whilst the vaccine has proven that there is indeed light at the end of the tunnel, there are still a few hurdles we need to overcome before we can return to previous levels of normality.
Below is an image of how the Pfizer & BioNTech Covid-19 vaccine stacks up against traditional vaccines. As we can see, the 90% effectiveness is remarkable, given this is an entirely new vaccine design, using RNA for the very first time.

However, the vaccine will need to be stored at -80C, which complicates the logistical process of getting the doses to reach billions of people. Pfizer has also stated that it will only be able to produce 1.3 billion doses by the end of 2021, which would mean 650 million people will be vaccinated. If other vaccines are not proven to be effective, it may take several years before the global population of 7.8 billion people is vaccinated.
The full Phase 3 results data from Pfizer are also yet to be published, so we are currently unaware of how long immunity will last for, or how effective the vaccine is across different age groups. There is also the risk that the virus mutates and makes the vaccine redundant altogether, although this is unlikely.
Despite the encouraging signs emerging from Covid-19 therapeutics and vaccine developments, it may take some time for the world population to experience these benefits. Mask wearing, social distancing and mass testing is likely to remain at the forefront in our battle against Covid-19 for the foreseeable future.
In this article, we will assess some of the UK listed Covid-19 testing stocks, which include: Novacyt, Avacta, Omega Diagnostics and Genedrive. It is important to note that whilst some of these companies stand to benefit from the influx of government spending, others might ultimately fall short. As always it is essential to DYOR and tread carefully, the markets are particularly volatile in the current climate, especially Covid-19 stocks!
Novacyt (LON:NCYT, EPA.ALNOV)
Share Price: 871p
Market cap: £619m
StockRank: 83
Test type: PCR, RT-PCR, ELISA Antibody
Novayct, through its PrimerDesign division is a world-leader in the provision of PCR testing. If you would like to read more about the company, you can read through my Stock Pitch published at the beginning of October. I have attached a link here.
Avacta (LON:AVCT) - Biotechnology & Medical Research
Share Price: 111p
Market cap: £280m
StockRank: 13
Test type: Affimer based LFT for antigen
Business & Model
Avacta, through its two proprietary platforms: Affimer® and pre|CISIONTM has been able to develop new cancer immunotherapies by combining these two innovative products. The company has also been able to focus its efforts on creating a diagnostics, bioprocessing and research division as a result of its Affirmer reagents technology.
Through the company’s pre|CISIONTM targeted chemotherapy platform, it is able to release the drug specifically in a tumour, which acts to limit the risks of chemo destroying healthy cells in other parts of the body. Avacta plans to initiate a phase I study for its pro-doxorubicin, the first pre|CISION pro-drug for cancer immunotherapy in the first half of next year.
Source: Avacta
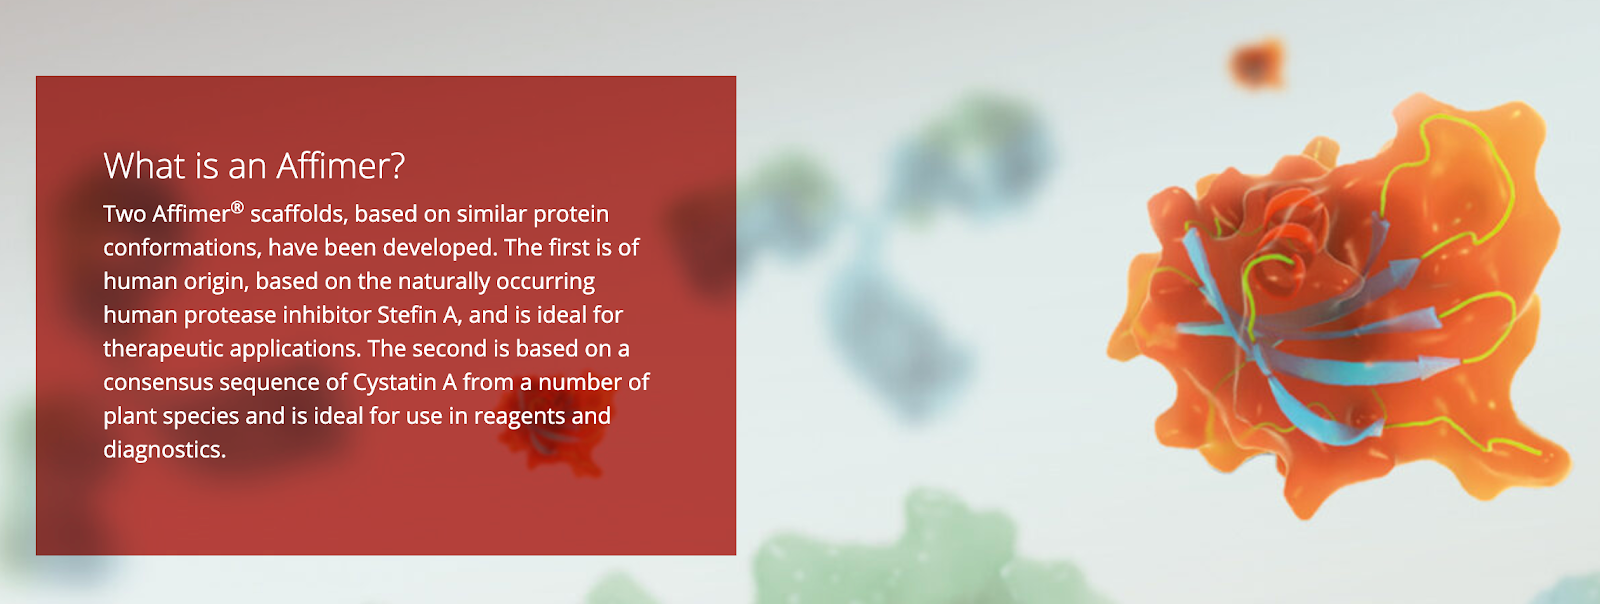
The Affimer technology developed by the company benefits from being able to be used in a wide range of applications. The Affimer reagents are essentially non-antibody binding proteins that can be engineered to detect a particular substance. There are a few key advantages of this approach, where antibodies have certain limitations, Affimer benefits include: Rapid Development, Engineered Specificity, Flexible Functionalisation, Ease of manufacturing and no immune systems limitations.
In April this year, Avacta announced a strategic partnership with Cytiva, formerly known as GE Healthcare Life Sciences, to develop a rapid point-of-care Affirmer based Covid-19 test for mass population screening. The company has made good progress to date, with Affimer reagents demonstrating great results in detecting the virus spike protein. The saliva-based lateral flow test using these Affimers is expected to generate accurate results within minutes.
Since April, Avacta has entered into a range of further strategic partnerships to expand the use of its proprietary Affimer reagents in Covid-19 diagnosis. The company announced a collaboration with Adeptrix in the US to develop a high throughput Covid-19 antigen test using Adeptrix’s proprietary bead-assisted mass spectrometry (BAMS™) platform. It has also announced an exclusive distribution agreement with Medusa19 for its saliva-based rapid test.
To add to this, Avacta also informed the market that a collaboration with Centre for Virus Research at the University of Glasgow had found that ‘certain Affimer reagents which bind to the SARS-CoV-2 virus spike protein prevent infection of human cells by a SARS-CoV-2 model virus, and therefore provide a potential therapy for COVID-19 infection.’
At the start of September, Avacta announced the launch of a SARS-CoV-2 ELISA Laboratory Test to detect current infection in individuals. The company stated that it will use the ELISA tests for its own clinical validation of its rapid point of care saliva based tests in addition to being manufactured for sale.
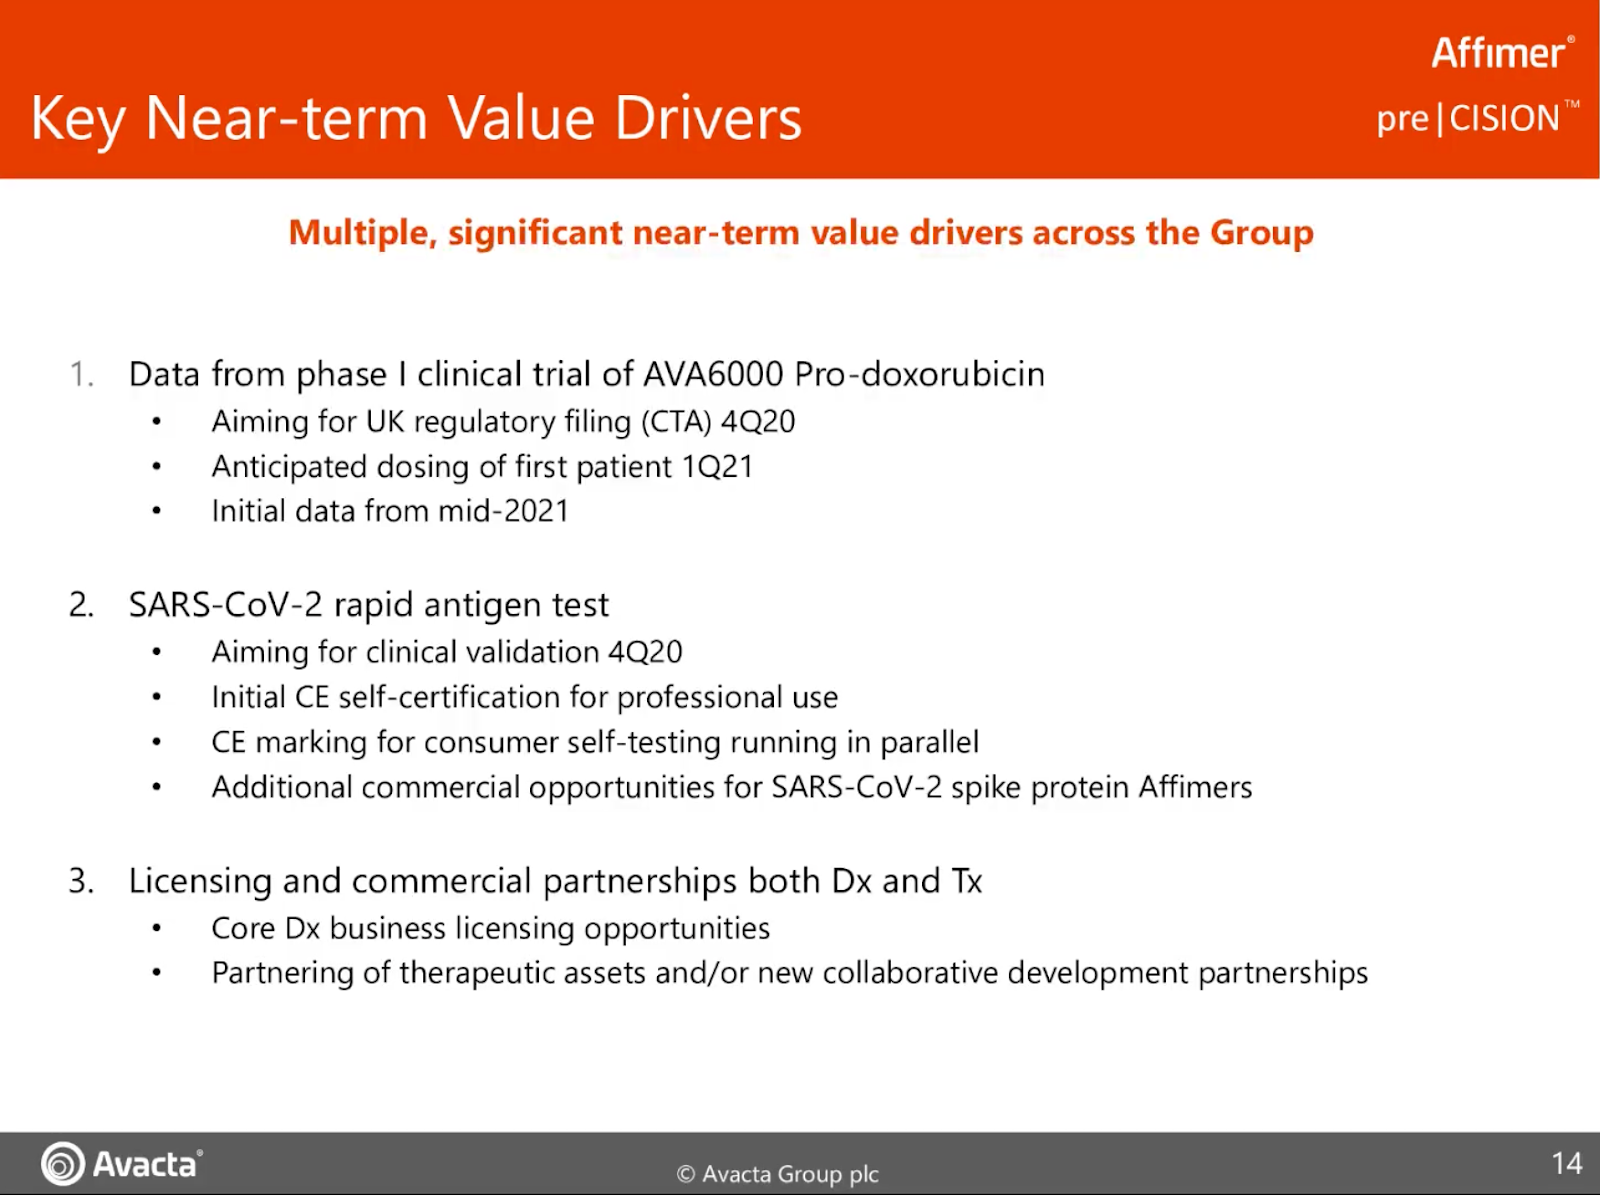
Whilst Avacta’s Affimer technology seems highly promising, it is still awaiting clinical validation of its products in the Covid-19 setting. The image below was taken from the company’s investor presentation on the 29th September, detailing the Near-term Value Drivers.
Source: Avacta
Financials & fundamentals
Although the company has been successful in growing its revenues in recent years, losses have been mounting. Revenue stood at £1.8 million for the 6 months ending June 2020 and reported losses totalled £7 million after factoring in R&D spend. It is very difficult to value the company due to the uncertainty over its future revenue streams and levels of profitability from its product range.
In the near-term a lot depends on the success of its Covid-19 Affimer reagents. This could be financially transformational for the company. In the most recent Interim Results, the company commented that ‘In the UK alone, the demand for antigen testing in the community could be as high as 100 million tests per month in the medium-term.’ However, there is no guarantee that the tests will meet the rigorous clinical standards that are expected or that the company will be able to rapidly scale up production in time to meet this demand.
Biotech companies commonly burn through cash quite quickly throughout the clinical development phase and Avacta is no exception. The company has had to make a series of equity raises over the past few years, to meet the cash flow requirements of the company. The Interim Results in September confirmed that the company had managed to raise £53.8 million over the 6 month period to 30th June 2020, which allows the company to expand its Diagnostics and Therapeutics programmes. The company ended the period with a cash balance of £54.5 million.
Genedrive (LON:GDR) - Healthcare Providers & Services
Share Price: 60.5p
Market cap: £34m
StockRank: 4
Test type: PCR, RT-PCR
Business & Model
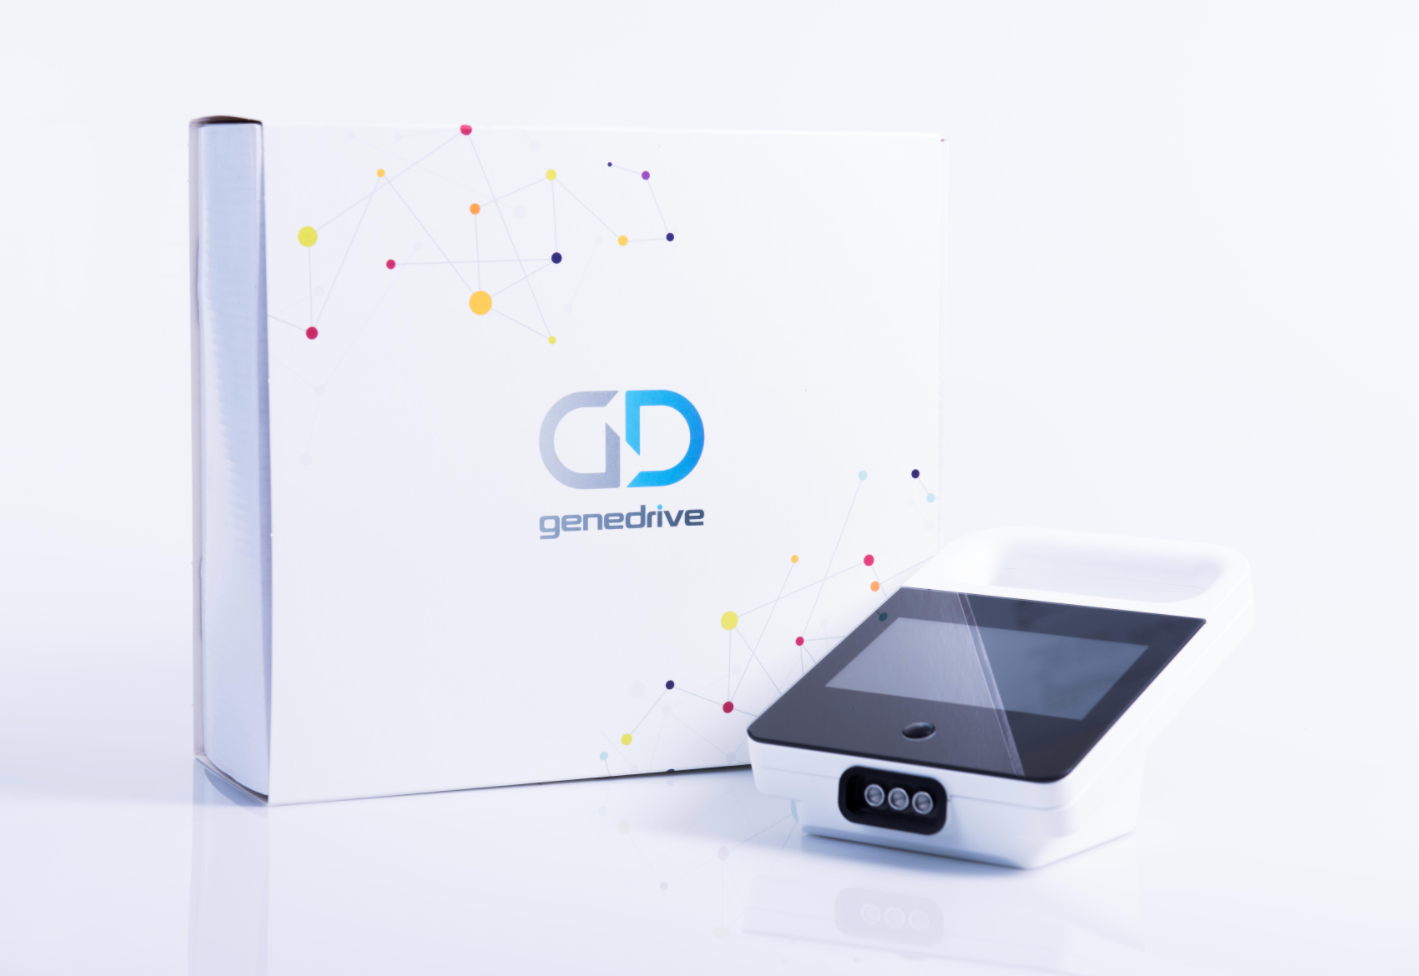
Genedrive® is an innovative portable PCR platform that can use a range of different sample types including plasma, sputum and buccal swabs for rapid nucleic acid amplification to generate results. The platform is optimised for high level molecular diagnostics analysis at low throughput for decentralised laboratories. The simplicity of the device is a key selling point, with no need for specialist knowledge, data interpretation or routine maintenance.
Source: Genedrive
The Genedrive platform can be used for the detection of not just infectious diseases, but also human genotyping, animal health, pathogen identification, and other applications. The Genedrive® Connect app can be downloaded to manage patient data and transmit test results. The company lists the following key features of its product:
- Affordable platform that facilitates testing in low throughput settings.
- Decentralised testing.
- Rapid results.
- Single test throughput.
- Easy to use single button operation with simple software.
- For various sample types.
- Single use consumables.
Genedrive has also developed a range of test kits that can be used on a variety of platforms. It has received CE-IVD Certification for its HCV-ID test, MT-RNR1 ID test for the detection of the single nucleotide polymorphism (SNP) and more recently its 1-step PCR beads test for SARS-CoV-2 detection. The company also provides a customised pathogen detection product called Genedrive® BioPlex, for the US military.
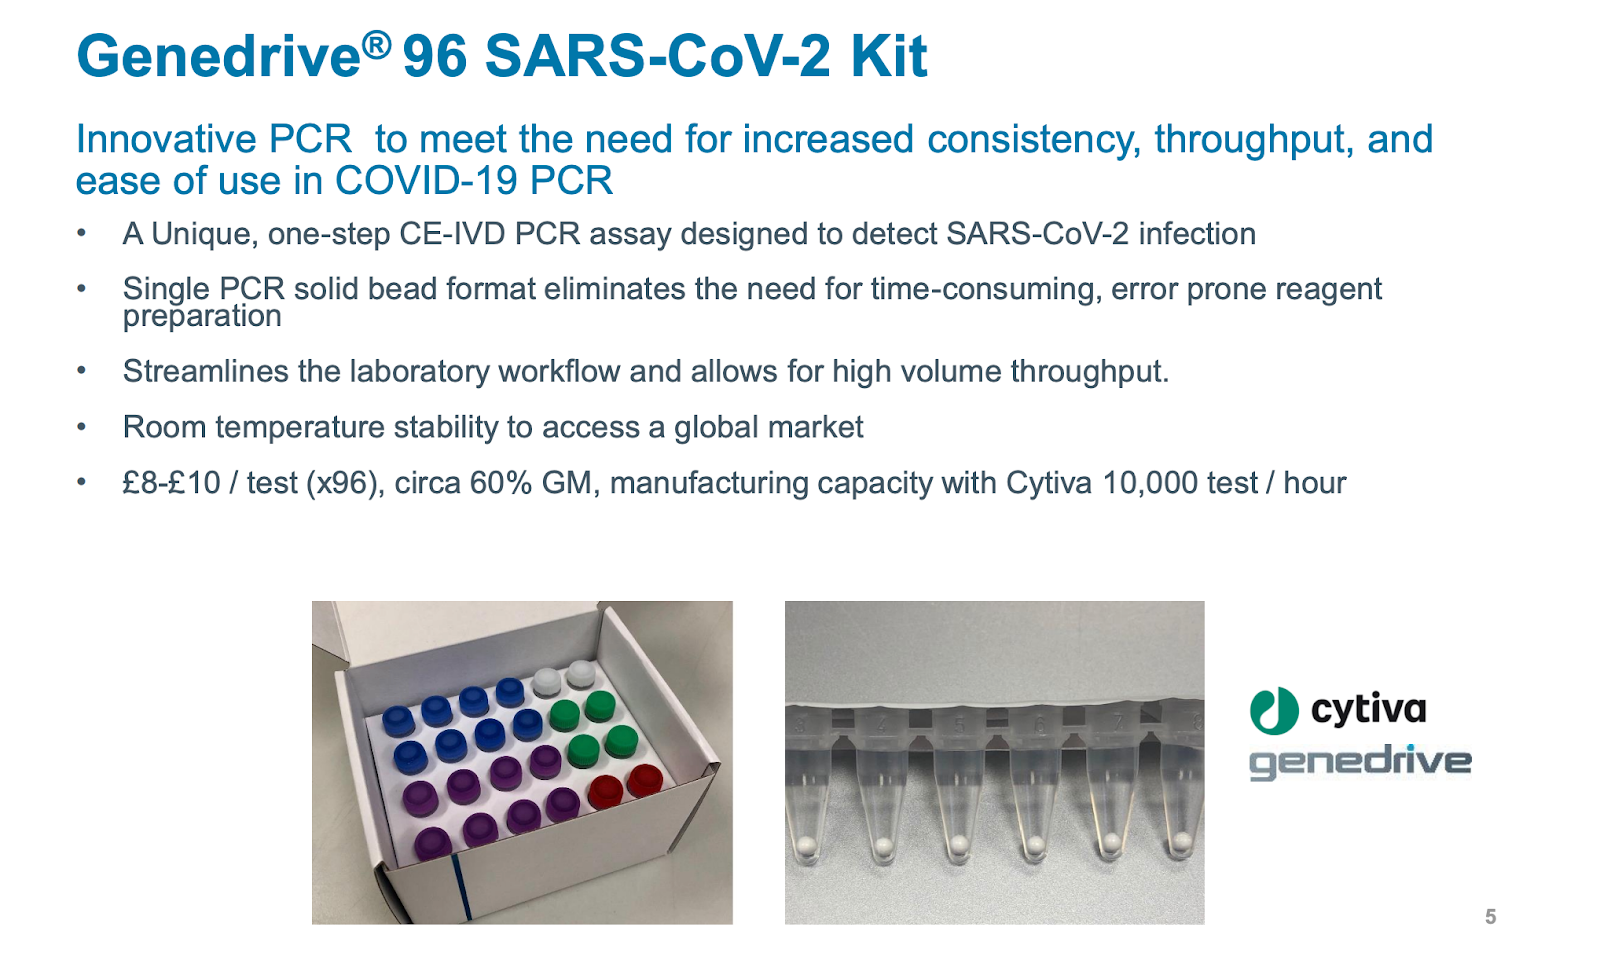
Genedrive’s 96 SARS-CoV-2 Kit received the CE-IVD mark in May this year. The kit is in a 96 well format for high throughput testing and can be stored in ambient temperatures. The tests have been developed to be performed in a 1-step process, as no reagent preparation is needed and results are generated in under 100 minutes. The company now sells its test in several countries outside the UK and Europe through its existing distributor network. Genedrive recently received approval in South Africa, and is waiting on applications made for the US and Indian markets.
Source: Genedrive
Moving forward, the company has announced its intention to develop a test for tuberculosis (mTB) detection and is also developing a point-of-care solution to detect SARS-CoV-2 virus in saliva, which would generate results within 15-20 minutes.
Financials & fundamentals
Revenues have fluctuated over recent years and settled towards the lower range at £2.36 million in 2019. Losses also varied over this period, reaching £3.64 million last year. In the most recent trading update published in July, the company said it expected to generate revenues of £1 million for the year to 30 June 2020.
The company did disclose in the trading update that it has received over £1.0m of indicative orders for Genedrive® 96 SARS-CoV-2 kit, which depended upon pending regulatory approvals. It also stated that ‘Further orders for the CoV-2 test are anticipated through a widened network of distributors’. The margins for these kits are around 60%, so this could be a significant profitability driver in the coming months. If the point-of-care SARS-CoV-2 test currently under development also meets the necessary requirements for approval, further revenues and profits should be expected from this.
Genedrive ended the 30 June 2020 financial year with a cash balance of £8.2 million, after an equity fundraise in May 2020.
Omega Diagnostics (LON:ODX) - Healthcare Equipment & Supplies
Share Price: 47.5p
Market cap: £85m
StockRank: 24
Test type: LFT antibody, ELISA antibody
Business & Model
Omega Diagnostics is a medical diagnostics company, which operates through three main segments: Global Health, Food Intolerance and Covid-19.
The Global Health division is currently focused on supporting diagnostics for patients with HIV. Omega’s VISITECT® CD4 Advanced Disease lateral flow assay allows rapid testing to take place to detect individuals with HIV. The tests can be used in a decentralised setting, at the point of care, which allows for faster, more efficient and lower cost testing.
Omega Diagnostics has developed two innovative technologies for allergy detection in food. Food Detective® is a point of care test that screens for the presence of IgG antibodies in 59 common foods and provides results within 40 minutes. The FoodPrint® platform is a lab-based ELISA test, which measures food specific IgG antibodies for over 200 different foods to pick up on any immune system reaction.
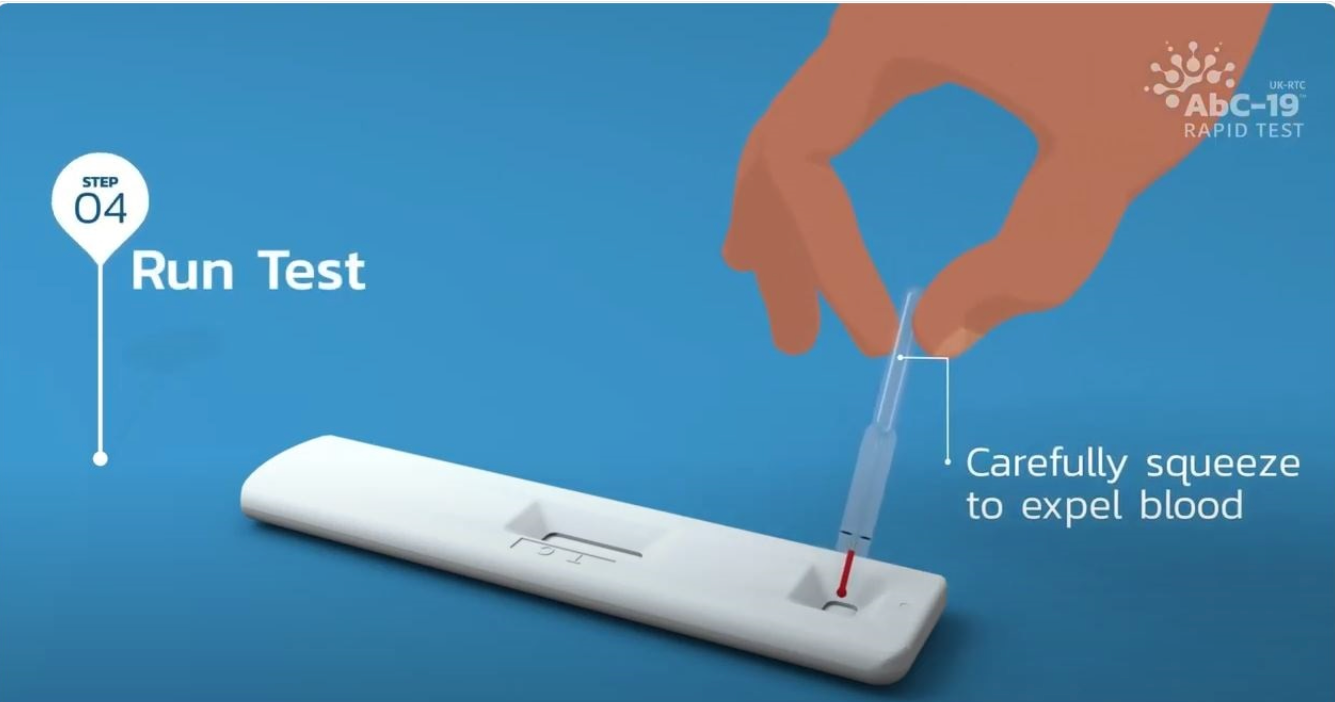
Using the company’s notable antibody expertise, Omega has been able to develop and manufacture a Covid-19 point of care antibody test as part of the UK Rapid Test Consortium, on behalf of the UK government. The test, referred to as the UK-RTC AbC-19™ Rapid test, has now received its first orders from the UK Department of Health and Social Care (DHSC). Omega has also entered into a partnership with Mologic to provide manufacturing capabilities for its Covid-19 ELISA antibody diagnostics test.
Source: Abingdon Health
Through its partnership with Mologic it also agreed to sell an Omega CE marked Mologic lateral flow antibody test, under Omega's VISITECT ® brand. The antibody test differentiates itself from others by testing for three types of antibodies IgA, IgG and IgM. This means that the test can detect positive patients at an earlier stage than other antibody tests. The test was commercially launched at the start of October.
The company has also noted the need for a point of care antigen rapid test for Covid-19. It is working with Mologic through its material transfer agreement that it signed in June this year, to potentially manufacture their lateral flow antigen test. The company made the following comment with regard to these developments, “Mologic is currently evaluating a prototype in a number of healthcare settings and the results to date look promising. If this continues, then by the end of November, Omega would look to commence technical transfer of the test prior to commencing manufacturing.”
Financials & fundamentals
On 28th October 2020, Omega Diagnostics issued a trading update and notice of interim results for the six months ended 30 September 2020. Revenues are expected to come in at £3.16 million, which represents a 29% fall from the prior period. Losses will amount to approximately £1.3 million for the period. The company cited that although the results were in line with management expectations, the company was affected by short-term performance issues with its food intolerance business as a result of the pandemic.
However, management provided a more upbeat note on forward guidance, saying that “The Board remains confident in the Company's prospects and has made substantial progress over recent months in positioning the business for a significantly improved performance in the second half of the financial year.”
In June, the company sought to raise capital through an £11 million equity raise. At the end of September 2020, the cash balance stood at £6.95 million after capital investment in plant and machinery for Covid-19 related opportunities.
Part 3...
In the third part of this series, we will be taking a closer look at Braveheart Investment Group, Yourgene Health, SourceBio International and drawing some overall conclusions. Stay tuned!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
21 comments
Novacyt had an RNS today with an R&D update:
https://www.stockopedia.com/share-prices/novacyt-sa-LON:NCYT/news/novacyt-sa-rampd-update-urn:newsml:reuters.com:20201116:nRSP3501Fa/
I hold.
Has anyone seen Dr. Reiner Fullmich's video outlining his intention to bring a class action against PCR testing?
This appears to be going after certain individuals but I wonder whether there could be any risk for PCR manufacturers such as Novacyt?
The CEO of Novacyt and a consultant to the board have acquired about £500k and £90k worth of its shares respectively over the last two days:
https://www.stockopedia.com/share-prices/novacyt-sa-LON:NCYT/news/novacyt-sa-directorpdmr-shareholding-urn:newsml:reuters.com:20201112:nRSL0564Fa/
https://www.stockopedia.com/share-prices/novacyt-sa-LON:NCYT/news/novacyt-sa-directorpdmr-shareholding-urn:newsml:reuters.com:20201113:nRSM3414Fa/
Those very significant purchases make me feel much more confident in continuing to hold my Novacyt shares, despite their 33% drop in price on Monday followed by a partial recovery later this week.
I agree. I was close to dumping my holding prior to that news. The other UK covid plays look risky in comparison, particularly those with no product yet approved.
Are we expecting a juicy special dividend next year from Novacyt Sa (LON:NCYT) - despite the tax angle, some might prefer that to spending the entire cash pile on possibly less profitable business generation/acquisitions?
Another tangential idea for a covid play - Palantir. From today's TechMarketView email ''Demand for Palantir's software has increased as a result of economic and geopolitical uncertainty, and more recently it has benefited from the COVID-19 pandemic.........In the UK, Palantir has made headlines due to its role in supporting the Government's response to COVID-19. Its Foundry platform has been connected to NHS England and NHS Improvement data to provide a consistent operating picture—“single source of truth"—for managing the pandemic. It is also being use to manage the supply and demand of critical NHS resources including PPE, ventilation and oxygen equipment, and ICU consumables. It secured a £20m call-off contract as part of the Home Office's Border Flow Service (see Palantir secures £20m deal to help monitor the UK border) and, according to recent media reports, is in discussions with the Government to support NHS Test and Trace.'' They lPO'd only in Sept, but with $26bn market cap these UK NHS contracts seem small beer.
Thank you for a interesting summary.
I hold both Avacta (LON:AVCT), Novacyt Sa (LON:NCYT) and Synairgen (LON:SNG) (the latter is my smallest holding by some way and Novacyt Sa (LON:NCYT) nearly my largest.
I agree with the general sentiment here that a vaccine is very positive for Novacyt and makes them even more of a bid target (for Pfizer?) than they were before.
Couple of points
I did not top on Novacyt earlier this week as even with the fall, which has been painful, it is still a 10% holding.
Regards
Michael
I saw this morning on CNBC from an epidemiologist that the vaccine wouldn't be effective if 30% of the population where not to take it. Just do a survey of your friends to see who would be first in line to get the vaccine. From my inquiries I am beginning to wonder if people are being a little too optimistic. I would love to here feedback from others
Excellent concise article......await next episode as hold a couple of these ...have held NCYT in the past and just topped up with a few SYNG as the treatment aspect is also vitally important from an ill covid positive patient point of view and the phase 2 trial results have been published and are good.
Did I miss something? I thought GSK was one of the leading players in this game?
Great write up, Thank you. Could you also have a look at CTEA for part 3? They have the COV-ID app and a link up with BHA to provide the healgen test which is on the governments short list of lateral flow tests.
Interesting free-to-read article on rapid tests and their accuracy
https://www.economist.com/scie...
Thanks Keelan,
I watched £SBI on Investor Meets Company last night. I assume the recording will be up.
It's clear they are not just a testing company but have seen an opportunity which they think they can monetise. Their margin on testing is currently 40% gross. They expect the business to peak in 2021 but didn't view the vaccine news as negative but something to drive testing shorter term .Its clear they are going to look at bolt on acquisitions to bolster their other business areas. It also seems to be the game of some of these other players to use the cash flows elsewhere.
They did have some other interesting businesses including storage which is clearly very high quality returns and very relevant post the Pfizer announcement. They spoke about 80% gross margins and 90% recurring revenues which caught my attention!
Hi Alex,
In my opinion we always knew there would be vaccine news and in fact it was estimated by Numis to be due In November. So there shouldn’t really have been any surprises for the market. There will be more vaccine news Too And its a good thing for humanity but its also a good thing for the testing market too. We will roll a vaccine out and testing will be a regular part of that roll out. You need to know you dont have it before you take the vaccine. So that requires a test. 7 Billion people on the planet. Secondly it takes time to create all those vaccines and roll them out so we probably have 2-3 years whereby we cant achieve herd immunity.
We also need to know how long the vaccine works for (we dont know that yet). So testing will be ongoing. Every time someone gets the flu, we are going to need to test. Then finally with all this investment perhaps see continued innovation. The Q16 & Q32 diagnostics equipment that NCYT are putting into the field are capable of a lot more, legionella , clostridium, norovirus who knows perhaps we could try and eradicate flu because we will have the equipment in the field and diagnosis can be quicker before these diseases get passed about.
I’ve taken the opportunity to get some Novacyt SA (LON:NCYT) at what I believe to be a decent discount.
Firstly, it’s the only one of the stocks generating real and large cash flow. They were one of the first to market and trust is everything when it comes to medical products. When this is all over, if testing has ‘had its day’ they will likely have >£200m cash in the bank. Every PI seems to be an expert virologist / immunologist these days. I am not, therefore I’m putting trust in the numbers rather than what some of these companies may speculatively deliver over next 12-18 months.
Secondly, a number of funds have bought in at these levels. They only make ‘long term’ decisions and would have factored in a vaccine into their models. II support provides a stable investor base for the future.
Thirdly, I believe it is an attractive takeover opportunity for big pharma given product already to market and strong earnings. Would not be surprised to see it snapped up over next 12 months and this gives some protection on the downside.
Finally, there are some near term catalysts as we wait for the approval of their winter Covid flu product (of course this is binary and can go both ways).
Another interesting article - thanks!
If you want a smoother ride do consider $ABT - share price barely batted an eyelid on Monday (I panic sold then but may re-enter). Partly because diagnostics is only c. 30% of Abbott's business, and covid testing only part of this. But they do have most bases covered and, crucially, global reach and reputation. Roche and Thermo-Fisher I believe are other 800lb gorillas though I haven't investigated.
The list of UK contracts awarded is updated weekly I think
https://bidstats.uk/tenders/me... I sense the DHSC's latest focus is on rapid testing, perhaps with positive cases then confirmed (or not) with a pcr test. The table suggest £496m contract was awarded to Innova Medical. This follows a large award to Oxford Nanopore for their quicker LAMP tests. It's a mistake to think that UK quoted companies will necessarily be the main beneficiaries of the huge testing spend.
Myself, I'm wary of Avacta (LON:AVCT) and now put it in the crap-shoot bucket. They announced their 15-min test back in May, but there seems little real news subsequently on certification/ validation and there's perhaps a worry that they're missing the boat as they appear not to be part of any of the large scale rapid test pilots in Liverpool etc. I believe they claim to have large manufacturing capacity though.
PS petty comment - the article uses the word Affirmer in many places; I believe Affimer is the term Avacta use
PPS just heard on the 7.00 pm news a northern UK firm, Croda (?) talking about preparing to transport the Pfizer vaccine from mid-December. In fact, I do wonder if $BNTX might be a better way of diversifying exposure as the world transitions from testing to vaccinating? BioNTech SP is now only 10% above its Friday level and equal to the highs of July. I do feel the US markets in this area are far more stable than the 'wild west' AIM market. I read that Pfizer/BioNTech is a profit-making enterprise (unlike the 'humanitarian' ethos that is common in the vaccine field) as they funded their $2bn research effort in-house. Obviously they may be vulnerable to a better/cheaper/more user-friendly vaccine competitor but it sounds like they'll have a strong order flow initially as govts' priority will be speed. Sorry for veering off on a tangent!
Excellent article Keelan, much appreciated.
What a difference a few days makes. When the vaccine news came I was set to sell all my NCYT on fear that Covid testing had had its day, but I missed the opportunity. So ended nervously buying more at £7. And then the director buys £500,000 worth at £8.17!! He obviously know what’s to come. That’s a years salary he has just reinvested.
There is a bigger picture here developing, antibody testing and pcr testing are going to be a big part of any vaccine roll out and beyond. So testing will be around beyond 2021 albeit in smaller quantities from 2022
We are also creating a diagnostic infrastructure that can deal with future pandemics as well as provide fast and reliable testing of a whole host of diseases. Imagine how better we could have dealt with the pandemic if we had already had the diagnostic equipment in place in every GP’s surgery/ care home and could have been mass testing from day 1. imagine if that equipment could be used to test for a whole host of ailments.... perhaps reduce some burden on the hospitals
An evolution in diagnostics ?
Hi. What will happens if some new Vaccine news will be announced? How deep Novacyt will fall then?
Hi. What will happens if some new Vaccine news will be announced? How deep Novacyt will fall then?
Who can tell?
What we can say, with quite a lot of assurance, is that positive announcements about vaccines were expected in the last two months of the year. There was a small risk they would all fail, but it wasn't very high. So the big stock gyrations this week were on news that really ought to have been baked in to prices already - basically there was a lot of hot money in the market, there were a lot of undervalued companies out there and a few overvalued ones, of which Novacyt Sa (LON:NCYT) was probably one at its highest points.
We also knew, before the Pfizer announcement, what the likely trajectory would be for rolling a vaccine out and, roughly, the impact on testing. We'd expect the vaccine to be given to key workers and the most vulnerable over the first six months of the year, and then to the rest of the population beyond that. So we know that the big peak in CV-19 testing will be over the next six to eight months and it will decline thereafter.
However, we don't know how much it will decline. We don't know how effective the vaccines will really be, whether vaccinated people are still infectous and how long they'll need before they need a booster. We don't know what the uptake will be. All of these things will impact future demand for testing.
From a Novacyt Sa (LON:NCYT) perspective we can say two things - one, this was all entirely predictable and, two, given that it was predictable (so that future test demand was bound to decline) the vaccine announcement is good news. Why? Because potential competitors are now going to find it harder to raise funds by pointing to hockey stick models of future demand - which is an advantage for scale players who are already deployed. Keelan's excellent post brings this out, I think.
Hence - if you're rational about this, positive vaccine news is good news for Novacyt. Obviously, if all you're concerned about is scalping profits then it's a problem.
The big gyrations in Novacyt this week were because the price had got ahead of itself, because there was a lot of short term money in the stock that fled when the price tanked and, you'd have to suspect, because a lot of private investors had made life changing amounts of money by backing it from very low levels and were desperate to get out as they saw that dwindling before their eyes.
From a long term perspective I could make a case for Novacyt's price at half its current level or four times it. Those are odds I like. A lot of cash is already guaranteed in the coming year and CV-19 has catapaulted the company across the funding chasm that many good but cash poor firms suffer from. CV-19 testing will probably decline over the next year or so but will likely end up as an attractive long term annuity revenue. In the meantime there's a chance of more big contracts.
More positive vaccine news is now virtually guaranteed. The Pfizer announcement shows the virus can be blocked - if one can do it, so can others, hopefully including some of the free to market ones with less deployment problems. This is universally good news for humanity and a triumph of science that wouldn't have been imaginable even half a generation ago.
Most likely, I imagine, further positive news will have further negative impacts on "Covid-secure" stocks. Good. The market eventually rewards rational agents over irrational ones. The opportunity for Novacyt now is in the hands of its management - it has the funding and it has the scale to become a world leader in diagnostics. And it's far from being a CV-19 only stock.
It may fail, of course. But in a lifetime in investing I know that opportunities like this don't come along very often. I'm very happy to have hitched a lift on the ride and if it ends up crashing and burning then so be it. But I think the odds are in my favour, which is the best you can ask for when it comes to investing.
timarr
Thx Tim great post.
Keelan,
I am interested in your view on therapeutics. A few weeks ago a Virologist turned fund manager, Mike Taylor (https://twitter.com/biotequity... ) , recommended a Swiss therapeutics company called Molecular Partners. They seem to have the basis for a monoclonar antibody treatment that is capable of small volume injection.
https://www.molecularpartners....
https://www.molecularpartners....
I watched live on 15th October when the share price was 15 SFR. Didn't buy the next morning on the European open and then sat and watched the price surge on the USA market open. Of course it has gone onto 21 SFR on partnering announcements!
Essentially, what do you think of Mike Taylor's ascertion that the vaccines may not be that profitable whereas therapeutics providers will have more freedom over pricing and hence enjoy larger profit streams?
Also, what do you make of their approach technically?
M.
Excellent work Keelan - well done and many thanks. A quick glance at the accompanying charts certainly shows the hammering these securities had this week with only Novacyt Sa (LON:NCYT) showing any sign of recovery at present. This security would also be the most attractive of the quartet, if we were judging strictly by Stockopedia rankings, which I for one am tending to do amid all this uncertainty, but I am sure it is not as simple as that. I am really looking forward to part 3 so we can have the total picture and then maybe someone more technically qualified than me might perform the necessary compare and contrast between them all which I am sure would be widely appreciated.