A tech stock that went up in 2022

In 2022 the S&P/ASX All Technology index declined by 33%. One of its constituents that defied the trend was Data#3 (ASX:DTL) rising 15% over the course of the year.
Data#3 provide IT services to corporate and public sector customers. They work with clients to provide IT infrastructure such as cloud solutions, cyber security, data and analytics and connectivity through projects and ongoing support. This includes partnering with leading equipment and software vendors. They are the number one partner in Australia for Microsoft, Cisco and HP and a top five partner for Dell.
Outperformance was not limited to 2022. They have been a very strong performer over the past five years. In that time, revenue has doubled and the share price has increased 3.5 times. They are now a $2 billion company in terms of revenue and $1 billion in terms of market capitalisation with over 1,300 staff.
Revenue growth has been very strong over the last six years with compound annual revenue growth of 14.3% p.a.. This includes revenue sourced from public cloud work which has increased by more than a factor of 10 over that period to be worth over $1 billion.
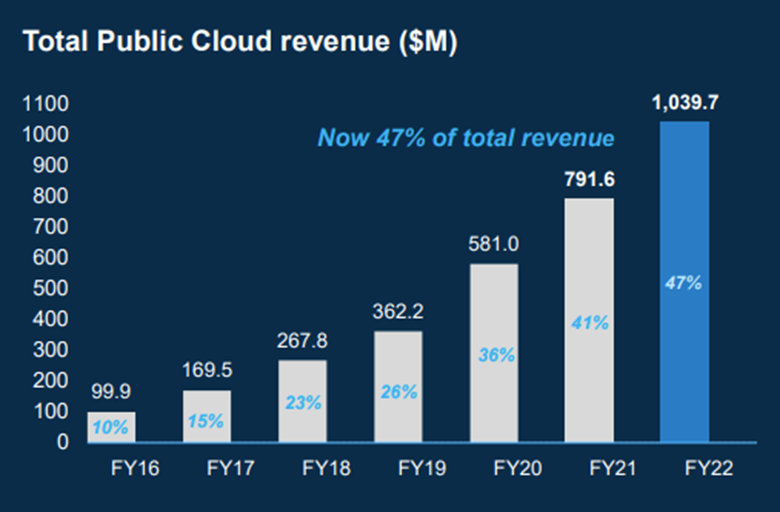
Source: FY22 Results briefing, 18/8/22
Data#3 are a well established player in a growing industry. Australian IT spending is growing at 6.5%p.a. with very strong growth in cloud computing. They are also well positioned to benefit from the growing emphasis on cyber security as well as data analytics and digital transformation.
The revenue base is solid and well diversified. Revenue is sourced 55% from government and 45% from commercial clients. Canberra is the biggest source by geography followed by Victoria, Queensland and NSW.

Source: DTL Investor Briefing, 17/11/22
There are over 2,000 customers with the top 100 accounting for 65% of revenue. Whilst this may sound concentrated, it is really quite diverse. By way of contrast, until recently Appen (ASX:APX) derived 88% of revenue from five customers. 66% of total revenue is recurring and many clients are long term.
% of revenue accounted for | Number of customers |
100% | 2125 |
90% | 430 |
80% | 218 |
65% | 100 |
Source: DTL Investor Briefing, 17/11/22
Unlike many technology firms, Data#3 trades on thin gross margins which have declined from 15% to 10% over the last six years. This reflects the business model whereby they are selling partner equipment and software to their end clients, but the mark-up on these is very small. They make their money through their expertise in putting the whole thing together, designing the process, managing the project and integrating it all.
Consulting is a higher margin and faster growing aspect of the business, but for now only accounts for about 16% of revenue.
Once wages and other overheads are covered from gross profits, less than 1.4% of revenue is left as a profit margin. However in the context of the business model, this is not necessarily problematic. Net profits after tax have doubled in the last six years as the margins are fairly consistent.
Net profit after tax in FY22 hit a record $30.3 million. This was somewhat dampened due to the global shortage of computer chips pushing out the timelines on some projects. The chip shortage is expected to ease in 2023 highlighting the opportunity for further profit growth. Earlier this week they announced profits for this half should come in near the top of the guidance range. Market analysts are forecasting 23% EPS growth in 2023.
Operating cash flow from year to year is quite volatile. It has been negative the last two years but was seven times net profit in 2020. The cash balance is high at $149 million. This again reflects seasonality with the June 30 cash balances far higher than the 31 December balances, but overall, it appears that cash flow is well managed.
The business requires very little in the way of fixed capital and consequently return on equity is high at 51%.
They have a strong balance sheet with no debt and plenty of cash. Receivables and payables are high at financial year end, but this reflects the seasonality around financial year end. Their working capital cycle is self-funding.
Data#3 rank just outside the top 50% of ASX companies according to the Value Rank. The strong share price performance has resulted in a deterioration of their value metrics. They are more of a growth stock, when compared to the broader market, however, still compare favourably with other stocks in the technology sector on a value basis. For example, the forward PE ratio is quite high at 27.5 but out of the 42 companies in the Software and IT Services segment they are in the lowest 40%.

They pay a high portion of their earnings out as dividends and DPS has also been growing strongly. The forecast dividend yield is 3.0%, fully franked, which again is high compared with the industry. Their earnings are sufficient to cover both dividends and re-investment in the business with no need for any capital raising over the last five years which would be dilutive for shareholders.
Despite the market’s current travails, especially for growth stocks, Data#3 is in a strong position. Their customer book which is heavily weighted towards government means they are likely to be far more resilient in the face of an economic downturn. This along with their strengths in delivering technology solutions should put them in a good position to continue prospering irrespective of what happens in the broader tech sector.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
2 comments
Thank you Chris. A nicely balanced report
Thank you, Chris. I made an entry(DTL) this week, has come off a bit since. Reports on the 16th of next month, so not too long to wait !!