All that glitters is gold (producers) – Part 2

Given the current strength of the gold price, companies that explore for, develop mines, or produce gold are receiving increased attention from investors. Analysing and valuing exploration companies is particularly challenging for non-specialists, and I believe that the majority of investors seeking exposure to these types of companies will be better off with a fund or ETF that specialises in this area. This can also be a suitable option for investors seeking to invest in gold producers, as it is likely to provide investors with geared exposure to this sector. They may still benefit from the tendency for gold producers' share prices to lag the spot price (see my first article), but this is essentially a sector bet. Many investors, such as myself, are more interested in identifying specific valuation anomalies. This is why I introduced some of the key metrics that are often used in my last article. However, these are blunt tools at best, and one of the advantages of commodity stocks is that they are relatively easy to model. Before I go into that, there are a few comments from the first article that are easier to address altogether here:
Company selection
I tried to pick the mostly pure-play gold producers listed on the UK market that had significant historical revenue, hence indicating that they have been producing gold for a while. The idea was to exclude companies where most of the value is in exploration or development. However, this may miss companies that have only recently entered production. Anything without a long-term production history should be considered significantly riskier than something with a proven history of successful operations. (My own cautionary tale of investing in Hummingbird Resources last year shows the risk that new mines represent during production ramp-up, especially if these developments are debt-funded.)
Why the UK? Well, since almost all subscribers have access to UK market data, investors will be able to access the companies' stock reports. This doesn't mean the best opportunities are in UK-listed businesses. Indeed, the broader range of companies listed in Canada or Australia may offer better investment ideas. However, it is also possible that companies listed on exchanges where investors and institutions are accustomed to valuing gold producers may result in fewer valuation mismatches.
At the end of the day, my company choice was intended to show how the typical industry metrics can vary significantly between companies and that investors need to use these to identify areas where they need to do more work. The tools I introduced in my first article will be helpful for investors to analyse gold producers wherever they are listed.
Country risk
Another concern some investors had was regarding the operational areas of the UK-listed gold producers. There is no getting around that many of these operate in high-risk jurisdictions. Part of this is because the easy gold in low-risk areas will have been accessed a long time ago. It may also be partly the "resource curse", where countries with large natural resources tend to have higher corruption and conflict due to competition over access to those resources.
Even within safer jurisdictions, gold production can be a risky activity. The role of investors is to assess if the risk-reward at any point in time makes an investment worthwhile. The country of operation will just be one of those risks. The good news about the country risk is that it tends to be diversifiable. Owning several undervalued gold miners across multiple areas of operation should be lower risk than owning just one.
Modelling the impact of gold price rises
Short-term models
Every investor knows that markets react to short-term beating of expectations. However, market expectations are set by brokers who typically update their models when there is specific news, not when commodity prices change. I am a big believer that the best guess for future short-term commodity prices is today's price, meaning that short-term numbers can be estimated using the current spot gold price. I'll give an example using Serabi Gold (LON:SRB) , since I already had a go at modelling this for the DSMR.
Production
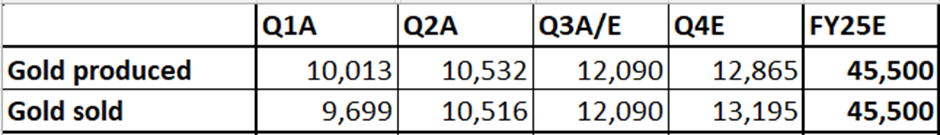
Almost all companies will provide production guidance as a range. Serabi is no different. This is what they reaffirmed in their Q3 production report:
The Company remains on track to achieve 2025 consolidated production guidance of 44,000 – 47,000 ounces gold.
When I reviewed this, following the H1 results, they had a strong H2 weighting, so I chose to take the lower end of the production guidance. After the Q3 production report this week, I am revising this up as a higher figure looks more reasonable. Others may choose to take the midpoint, or even model the range to give a range of outcomes, but for simplicity, I am going for what I think is achievable: 45.5 koz. There is no right way of doing it; we just have to remember the assumptions we make at the start when reviewing the output.
Another factor that can impact revenue and profits is any timing differences between producing and selling gold, as revenue is typically booked when gold is sold. Even with regular shipments, some variations can occur, although they even out over time. Therefore, over a year, I tend to assume the two are equal, and model any catch-up over the remaining quarters:
Revenue
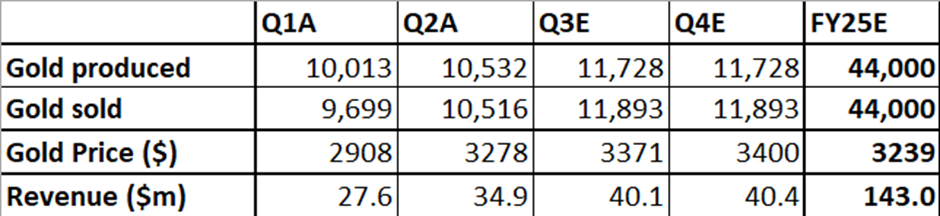
This is simply the gold sold multiplied by the gold price. This is what I had following the H1 results:
But we can really see the positive impact of the recent gold price moves, even as we only have one quarter left of the financial year:
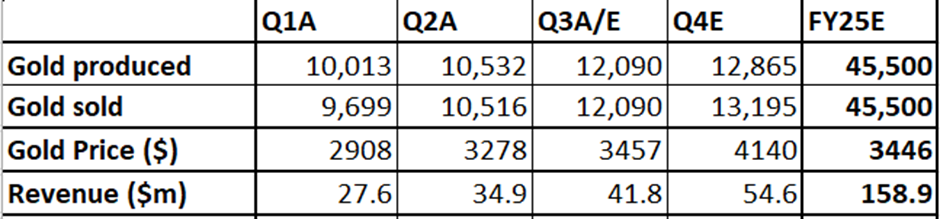
This is a sign that not all brokers may have caught up with the recent gold price changes:

Costs
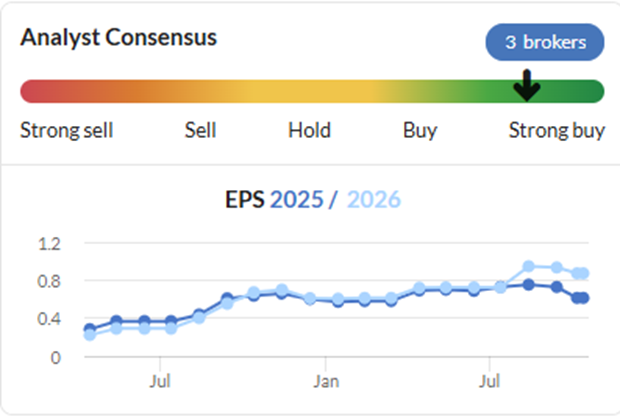
This is where things get a little trickier. An unexpected rise in costs for Q2 led me to express some caution about Serabi when it released its H1 results. This appears to have caught the brokers out, too, as the EPS consensus dropped, having been rising strongly for the rest of the year:
What worried me most was that it didn't seem to have been explained in the RNS, although a reader helpfully pointed out that some explanation was given in the notes to the accounts on their website:
Q2 cost of sales increased by US$3.9 million when compared to Q1, driven primarily by changes in ore mix and inventory drawdowns. Approximately US$1.2M of this increase relates to the processing of low-grade CMT stockpile at Coringa, consumed across March and April.
Excluding this one-off $1.2m cost hit, then I can put in similar costs for Q3 and Q4 as they had for Q2 and estimate their profitability:
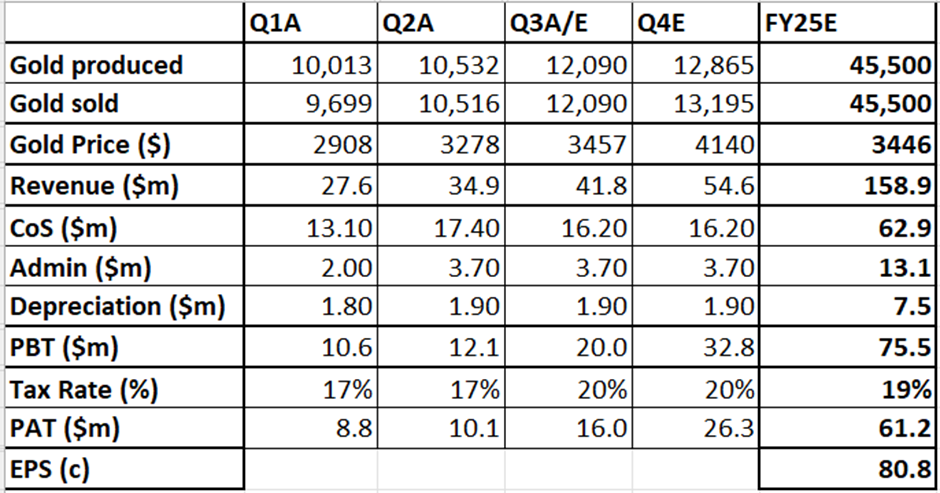
The tax rate is also a big unknown here. They look to have paid around 17% in H1 or half the Brazilian headline rate of 34%, presumably due to tax losses and capital allowances. I have guessed 20% for H2, but in the long term, this should trend towards the headline rate in Brazil. Even if they paid the full 34% in H2, this would be $53.8m PAT for the full year.
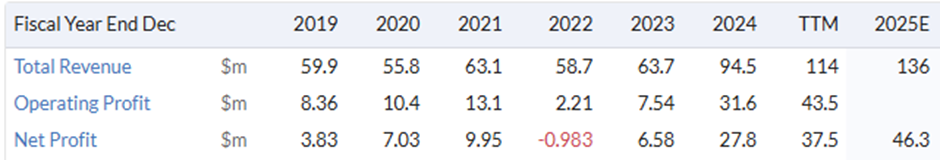
This looks like it will come in as a significant beat to the consensus if gold prices stay at current levels or above for the next quarter:
However, with a share price chart looking like this:
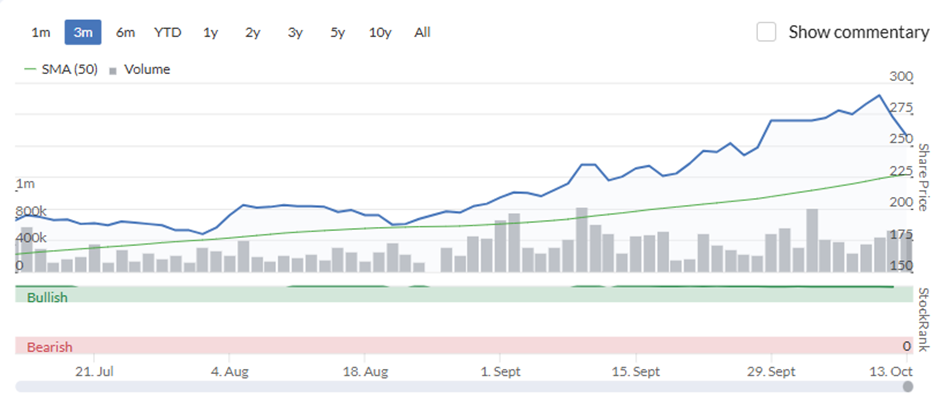
…it may already be in the price. To get a better perspective on this, we need to do some longer-term modelling.
Longer-term models
Quarterly models may be helpful to for sense-checking broker estimates, but in terms of valuation, it is the future years that count. Most companies provide some guidance on the future production expectations. In the absence of this, flat production is usually the best assumption. In Serabi's case, they aim to increase production to 60koz "by 2026" through additional ounces from Coringa:
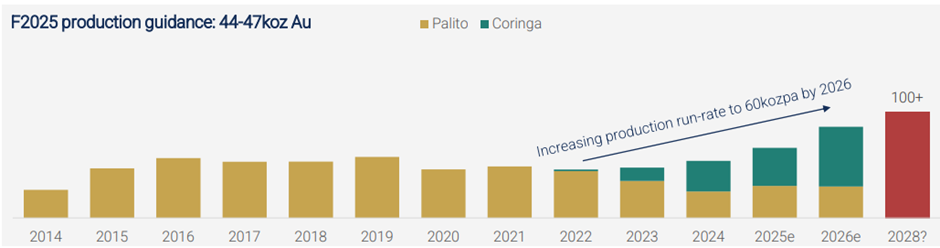
Their long-term aim is higher than that, but without a clear plan, I'm not sure it would be wise to include this. I also don't think they will be at 60koz run-rate from 1st January, so I think their broker Zeus, make some sensible assumptions on this:
We have brought forward the production uplift in our model (FY26: 55.6koz; and FY27 onwards: 59.1koz), which remains more conservative than Serabi's forecast for 60koz of gold from FY26.
In terms of gold price, I typically take spot prices, unless there is a clear trend for prices to decline. In this case, the gold futures curve from TradingView shows expectations for continued rises:
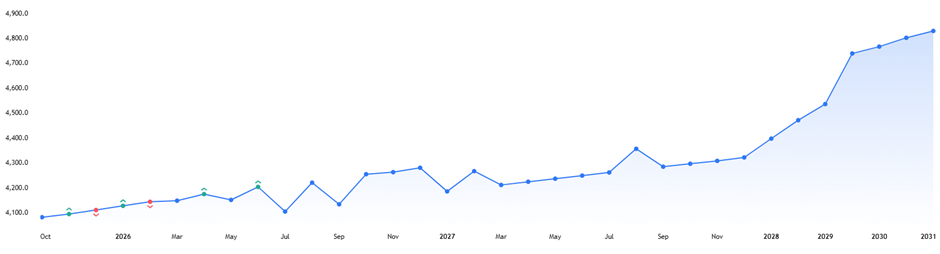
Some investors may be comfortable modelling profitability based on futures curves, but again, it is more important to note the assumptions rather than thinking there is an absolute right way to do it.
The other key factor that goes into modelling profitability long-term is the AISC. This has been rising recently due to general cost increases and the greater proportion of Coringa ore, which requires longer distance trucking:
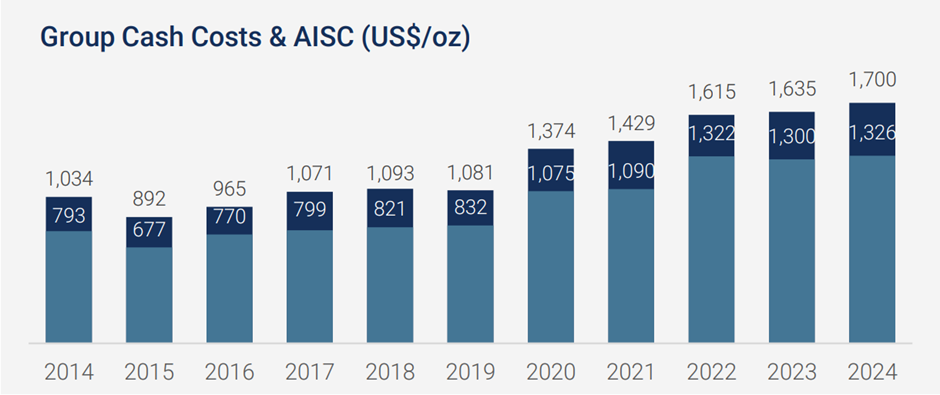
In 25H1, the AISC was $1,792/oz. This will be slightly elevated due to the processing of low-grade ore in Q2. However, I expect these cost trends to continue to rise by about $50/oz each year. Using these assumptions and a trend towards normal tax rates shows the potential earnings strength here:
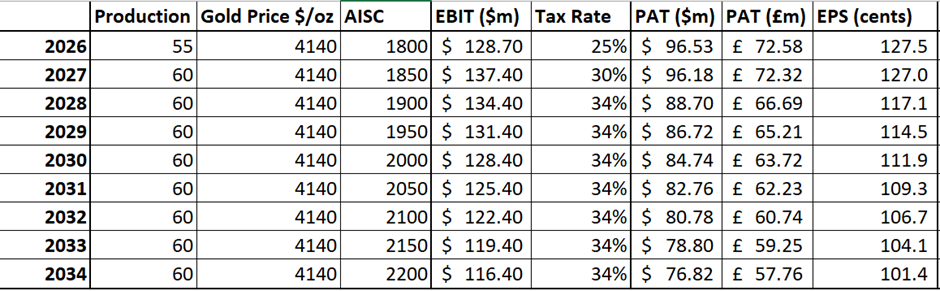
However, my understanding is that the current mine plan runs out in 2034, so for this type of investment, a Discounted Cash Flow may be more appropriate than using earnings multiples. This is also what broker Zeus use to value the business, although they rarely provide their updated model in their notes.
A discounted cash flow valuation adds together all the future cash flows but discounts future cash flows to represent that investors prefer cash now, and the inherent risks. This is called the Net Present Value or NPV. Choosing the appropriate discount rate would be an article in itself, so it is often best to use a couple of different rates and calculate the NPV for each. The notation indicates that an NPV10 represents the discounted cash flow at a 10% discount rate. If one makes a further assumption that cash flows = PAT over the long term, then we can use this instead of modelling capex cycles. Since we use AISC here, which includes maintenance capex, this seems a reasonable assumption. This is what I get for NPV10 and NPV20:
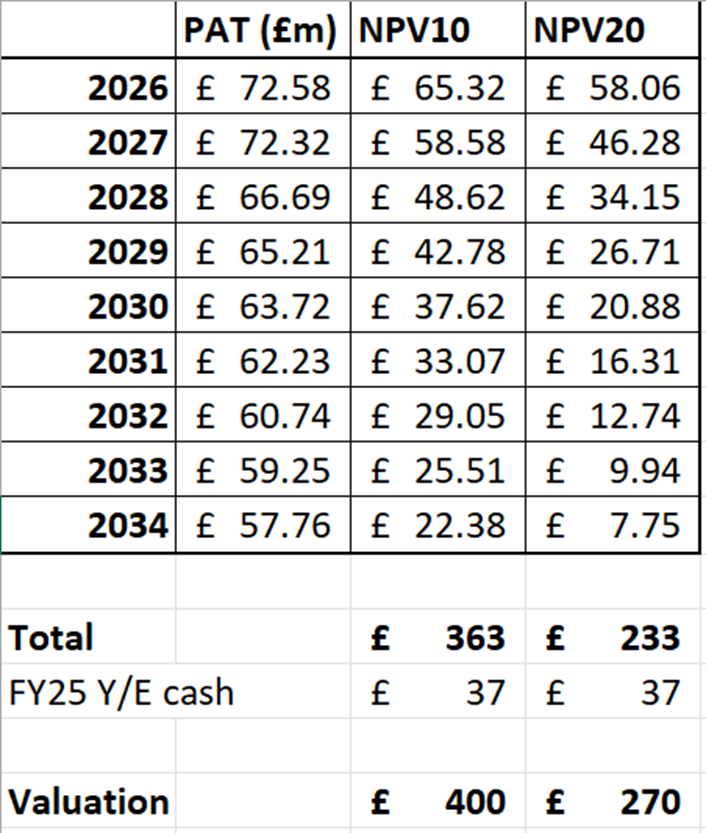
Finally, as I start my DCF in 2026, I add in my guesstimate of year-end net cash ($50m) to get a rough valuation estimate. Given the market cap is currently around £200m, there would seem to be some upside remaining at current gold prices, for all but the most conservative other assumptions, even after a great recent share price run.
Investors can, of course, model the impact of the company managing to boost production to 100koz or extend mine life through brownfield exploration. As these are not certain, investors may want to take a risked-NPV approach. This is where they make a conservative estimate of the likelihood of positive (or negative) events impacting the valuation and add (or subtract) the value of those "risked" by the chance of them happening.
In my simple model, Serabi ramping up to 100koz production by 2029 would add around £70m NPV20 to my valuation. If I think there is a 50% chance of them achieving this, then I'd add around £35m to my valuation to get a risked NPV.
Just to reiterate, this isn't about valuing a specific company or generating the most accurate set of assumptions for Serabi. My aim here is to encourage all investors interested in this sector to develop their own models, using their own assumptions, and make informed investment decisions based on their own work.
Do I have to be a gold price bull to invest in gold producers?
Despite writing about this topic and having some exposure to gold, I'm not a huge gold bull. I think there are some reasons to be positive in the short term. So far in this cycle, it appears that the major buyers have been central banks seeking to diversify their exposure away from the US dollar. The retail demand for gold has been relatively muted in some of the larger markets, such as Germany, so there is potential for this demand to continue. In terms of supply, price rises will lead some people to sell gold. We see this in the increased profits that companies like Ramsden's are making through their gold-buying arm.
However, it takes a considerable amount of time to build a gold mine. Greatland Resources discovered significant gold grades at their Havieron mine in 2018. They began substantive development work in 2021, and commercial production may not occur until H2 2027. This means it took 8–9 years from discovery to expected production. This means that investments made today, based on the strong gold price, may not be in production for another five years. When the gold price was low from 2015 to 2019, very few investors were willing to allocate capital to build new production.
This is the capital market cycle. The underinvestment over the years of low prices means that there is not much new supply coming, even as prices start to rise. Then everyone wants to invest in new mines as the prices soar. However, because everyone commits new capital to developing new mines, there is overcapacity a few years later, and prices will fall again. I asked ChatGPT where we are in the gold capital market cycle, and, perhaps worryingly, it says:
Short answer: We're in the late-cycle (peak-optimism) phase — arguably at or near euphoria — moving out of mid-cycle.
Reason: record gold prices, very large ETF inflows, huge gains in miner equities and strong M&A/sector activity — the exact mix you see when capital floods the sector.
We may well be late-cycle, but given the length of time taken to build a gold mine, the move from late-cycle to down-cycle may yet take several years. And what makes gold producers interesting is that if investors find ones that are significantly undervalued at current gold prices, the gold price can be hedged. Often, companies do this hedging internally when they feel they need to lock in a particular price. However, there is nothing stopping more experienced investors from doing this themselves at the portfolio level. You can be an investor in gold producers and be relatively agnostic on the future gold price.
Risk-Reward
After conducting this valuation work on a company or companies, it is up to the individual investor to determine whether any potential upside they see outweighs the risk of investing. I have already covered the fact that many companies in the sector operate in high-risk jurisdictions where governments may look at the exceptional profits of gold companies and think some form of additional taxation, or worse, may be justified. Local unrest can be a source of risk, too. Even without this, gold mining is difficult, and production misses for this reason or others are always a possibility.
However, perhaps the biggest risk is that the management of gold producers becomes carried away with the excitement of a gold price boom and decides to reinvest all the profits in expanding production at the peak of the cycle. If companies themselves didn't tend to act pro-cyclically by investing when the gold price is high and retrenching when the gold price is low, there wouldn't be a gold cycle. Instead, long-term investors in the sector may be better off looking for companies willing to act countercyclically, returning cash to shareholders during boom times and investing in exploration and growth in the leaner years.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

21 comments
To consider the performance of the individual miners against Gold itself I find useful to overlay the Gold Futures onto the individual stock.
I sold Caledonia Mining (LON:CMCL) today as the price was lagging behind the recovery in the price of Gold.
Compare that to Lundin Mining (TSE:LUN) which was barely affected by the recent weakness in Gold and has oustripped others during the recovery.
The recent fallback of c20% in SRB highlights the difficulty I have in deciding whether very high ranking, high momentum stocks are having a "temporary correction" and therefore are a buying opportunity or whether they should be sold because it is not a temporary blip!!
I appreciate that there isn't a "correct" answer and that one must make one's own decisions etc etc but has anyone any rules that they use to recognise such movements as a message to sell rather than to buy?
Hi dahhad, what i do with the momentum driven stocks that have a hiccup like Serabi Gold (LON:SRB) , is look at the fundamentals. If there is a profit warning, or the EPS figure is not increasing as fast as it it used to, i bail.
However, if it looks like the stock is still great value, and i believe Serabi Gold (LON:SRB) still is very good value even at a gold price of $4000/oz, then i stick with it.
Obviously if the gold price carries on falling, that changes the valuation.
It’s even better value today!!
Serabi Gold (LON:SRB) is a rollarcoaster for sure! Is up 20% since my last comment, but definitely not for widows and orphans. The latest presentation from the company is avaliable here:
Serabi-Gold-Corporate-Presentation-November-2025-v1.pdf https://share.google/zDKDJ1qQB...
Well worth a look if you want the bull case on why this is not only a punt on the gold price.
David
Like everyone else mark, many thanks for both articles. I’ve re-read this one a few times now, mainly looking at your valuation method. I started investing in miners (micro/small cap golds/silver/Plat mainly) around 30yrs ago and I’ve never found it an easy task. There are so many variables and each mine brings its own challenges. One of my first, eg, was Centamin and tbh i bought off the back of the Egyptian father & son team who had reviewed some of the original mine maps from the time of the Pharaoh’s. What the heck, there must be gold there. And i soon discovered that ‘desert’ mining was quite different from ‘jungle’ mining, etc. But my years holding CEY were a great learning curve.
I now use the Screens and QVM ranks as a starting point for many of my investment considerations and Serabi’s very high Stock Rank obviously didn’t go unnoticed. I started buying around May and have added a few times on dips, most recently today. Many on here seem to agree this is (still) a great buy, despite its falling Value score. I personally have this as a higher number in my own head, given we still seem ‘undervalued’ by many of the common metrics which can be seen in the Stockreport.
The value, as a potential buy, will obviously reduce as the SP rises (at least until produced ounces and sales catch up/increase etc) but do you have a view on the present Value score being thrown up by the Stockopedia algorithm, or is it simply a case of focussing on the overall Rank?
With this weeks pullback i noticed the Value rank has just gone green. No wonder. P.E 3.4 and PEG 0.1
It is still very cheap on fundamentals, even if the gold price sticks at no more than $4000/oz. Don't blame people for taking profits though, although i am sticking with it.
Is very volatile though so pretty nerve wracking. I still think it should double, as long as the gold price does not reduce.
David
Agree with all the other comments about the quality of the article. Very useful, thank you Mark. There was an article on IC on 17 Oct on gold ETFs including gold juniors ETFs. It included the statement "..such funds (gold miners ETFs) can suffer greatly when markets struggle....." Any thoughts on this - I would have thought that while market factors such as cost of borrowing etc will affect miners the gold price will be a stronger force? Does this mean that gold miner shares are not an effective balance to more general equities?
The good news for readers is that Serabi Gold and of course Mark along with the Stockopedia team are all presenting at the #MelloLondon two day investor conference which is now just four weeks away..
MELLOLONDON — Mello Events
There will be over 50 companies including Serabi Gold and hundreds of investors to network with over the two days. We have a great line up of speakers too
https://www.melloevents.com/me...
Do come and join us and use this discount code MLSub50 to gain a 25% discount
David
Very good article. I would just emphasise the sentence you included towards the end:
I have already covered the fact that many companies in the sector operate in high-risk jurisdictions where governments may look at the exceptional profits of gold companies and think some form of additional taxation, or worse, may be justified.
You cannot move the site of a resource and large profits tempt governments. But it is important to realise that one of the most egregious examples of this was the "windfall tax" imposed on North Sea energy producers by the last government and supported by the current one. The UK is now a "high risk jurisdiction" where large profits are seen as opportunities to tax, with the government taking the benefits of capitalism without the risks.
And ironically, that is one of the drivers behind the price of gold: gold is one of the few assets without counterparty risk. Gold miners, on the other hand, are not.
I largely agree about the UK, as there is no sign of the "windfall tax" on O&G being removed now that there is no longer a "windfall"!
However, every risk is relative, and I've seen no sign of the UK government taking hostages and demanding $160m ransom so far!
https://www.theguardian.com/au...
Crumbs, a military junta supported by Russian mercenaries. Red flags flying there.
It's great article Mark from a starting position, there are more considerations to come. Some small miners had hedged their future production, the climbing price of gold left them frustrated. They may be catching up now, the hedge having time-expired. Also the AISC is very important as some are nudging $2000 while others are half of that. Of course which State in which Continent has a bearing on an investment too. A wide spread would provide a Learning Curve, as it did for myself.
Hi Mark, what you've not mentioned is bad actors, take Hummingbird, is the mine still there? Is it producing gold in quantity? I wouldn't be surprised if it was. The thing was, due to problems with contractors, and they do the heavy lifting, targets were not met and debts were called in. Personally I thought it was down to people with agendas. I lost my money when things looked rosy so this is a warning for those who put their money in one basket, and that if an operator isn't getting money out of the ground it may take years for an investor to find out that there isn't going to be any return.
Great article and I'm lucky enough to have been in Serabi for a few years now. To me the a big risk with Serabi is the Coringa mine licence which is up for renewal in January 2027. They currently only have a trial licence. I think the general consensus is that the full licence is more likely than not to be granted, but with gold prices likely to continue on an upward trajectory, I can't help but think that the renewal will be far from plain sailing.
The Operators of Serabi are looking elsewhere, doing what any good mining company does when the life of mine shortens. Take Ariana Resources (LON:AAU) as an example.
Yes, I must agree with the previous posts when they say Mark’s article is an excellent piece of analysis work. A real deep-dive into gold producers, and number-crunching Serabi gold makes it a very enjoyable read! Thanks Mark
Very good detailed article that complements your earlier one Mark. Thank you very much indeed. I now have a much better understanding of how to model & value miners. I'm glad you chose Serabi Gold as your example above however because, quite fortuitously, I did strike it lucky this year by choosing Serbi Gold as my Basic Materials pick in Jan 25 using Ed's NAPS system. Needless to say I am very happy with the outcome! (Thanks Ed!)
So with a cost of capital of 10% Serabi has a valuation of £400m, compared to market cap today of £219m. Based on the current price of gold.
This cost of capital is the weighted average of the cost of borrowing from the bank and the return required by investors to buy the shares. So 10% seems reasonable.
A massive buy.
Great article Mark. The quality and breadth of research, ideas and commentary that the whole Stocko team provides is excellent and a real differentiator. There must be a huge amount of work that goes into these posts and it shows. Thanks.