Amur Minerals - (LON:AMC) - The Start of the Final Rise! (Nickel Mining)

AMUR MINERALS (AMC) - Improving Rating Figures......
I see AMC have moved up 5 Rating points in last 30 days and now has fallen into the one of the Bargain ‘Investment Strategies’ Screens... Walter Schloss 'New Lows' Screen (Bargain Stocks) on the back of a recent flow of 'Good News' which is getting share holders very excited.
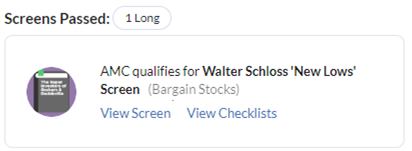
Walter Schloss New Lows is a value investing strategy based on an approach used by Walter Schloss, who was a disciple of value investing legend Benjamin Graham. The strategy uses value and price factors as its main rules. It searches for companies that are trading below book value, using the price-to-book ratio, and at prices that are close to new lows. Schloss said: "We want to buy cheap stocks based on a small premium over book value, usually a depressed market price, a record that goes back at least 20 years?and one that doesn't have much debt." Between 1956 and 2000, Schloss's fund produced a compound annual growth rate of 15.7%. In a 1994 shareholder letter, Warren Buffett wrote: "Walter continues to outperform managers who work in temples filled with paintings, staff and computers. And he accomplishes this feat by rummaging among the cigar butts on the floor of capitalism."
The report is also showing a much decreased chance of bankruptcy.
A final chance to get onboard maybe before AMC exceeds £0.02 per share and likely re-rate. Final figures according to some financial calculations is estimated a final takeover of anywhere of the region of £0.75+ per share.
Some recent media which highlights the predicted huge increase in future demand in Nickel and it's consumption....mines are needed and fast to meet this demand.
With this Micro Cap company sitting on one of the biggest remaining Nickel deposits in the world....with a mine primed to come into production in 3 to 4 years....when there will be an ever growing deficit driving up the per tonne price of Nickel at just the right time......the World's Mining companies will have their eye on Amur Minerals and their huge asset.
The chart below shows nickel is forecast to be in deficit after ~2020-2022 (note it is a bit outdated now).

......and
https://www.cruxinvestor.com/videos/nickel-investors-excited-as-ma-hots-up---4-mark-selby
The Company has issued Recent RNS's and interviews to confirm that this is still on track despite Covid and announced plans to secure a binding off take for the improved quality and quantity of copper they also have within the asset. This is predicted to happen within the next 2-3 months.
Confirmation of this off-take from what they have described as producer and marketer of nickel 'house hold name' will mean the company is financially stable right up to TEO and beyond (Russian Banking Feasibility Approval), takeover and a final multi billion dollar deal.The binding off-take agreement is likely to cause a re-rate into double digits on announcement.
This so called 'house hold name' is not only interested in the copper, they are also interest in taking 100% of the Asset at some point. Exciting time for shareholders.
This is an interesting watch from board advisor Adam Habib about 6 Days ago on Proactive Investors....
https://www.proactiveinvestors.co.uk/companies/news/922754/amur-minerals--adam-habib-outlines-progress-towards-teo-completion-and-offtake-discussions-922754.html
With a share price of £0.014, It could be one for a punt in the 'higher risk, massive reward' section of your portfolio.
With a market Cap of just £12.54m and mine worth billions.....(1.58 Million Tonne of Nickel x Current and rising market price of 12,418 USD Per Tonne) ....the reward for shareholders would be huge indeed....that is not pricing in the additional 20 million pounds of copper, 2000 ounces of gold and 25,000 ounces of silver.
DYOR
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
89 comments
Wasn’t a bad little tip @1.4p per share. Current offer on the table worth 7.5p.
Nickel Flying again!!
https://twitter.com/lgame88/st...
.
Something brewing here. We were 40p in 2016 on gaining licence. We are now in takeover territory for one of the worlds largest Class 1 Nickel deposits. AMC are cashed up...have a steady income from their Iron Ore investment. They have went quiet on the Binding Off Take which would be needed to take them to BFS...this suggests that they must be concentrating on TEO only and Russian takeover. Given the demand for Nickel that could be sooner than we think.
A surge in demand for electric vehicles is sending the price of raw materials soaring, threatening to slow the push toward making cheaper batteries that are key to more widespread adoption.
Lithium, the mainstay for rechargeable power packs used in EVs, is roaring back after a three-year slump in prices, while cobalt surged about 57% last quarter. Nickel jumped to a more-than six-year high earlier this year on optimism about the clean energy transition, though fell in March on plans by a top Chinese producer to beef up its battery business.
China is the biggest player in EV batteries, with the majority of the world’s capacity, and has a stranglehold over the processing of crucial battery materials. With demand building, producers are striving to make cheaper batteries — the most expensive components of EVs, accounting for about 30% of the total cost
/2021-04-14-rocketing-metal-prices-threaten-to-hinder-ev-affordability/
As battery metals continue to rise to the forefront of attention, much has centered around lithium and cobalt. Governments have enacted policies to encourage investment into the critical raw materials they deem essential to the green energy transition. At the same time, supply chain concerns surrounding nickel have begun to garner increasing focus.
https://www.mining.com/nickel-...
.
Commodities seems to be the big story at present with news about Glencore reinstating dividends and Rio Tinto paying out a record $9 bil in dividends. This renewed interest in the sector will gather momentum particularly for battery metals.
We have seen the upward trajectory in the price of nickel.....and we are only at the begining of this story. Look at HZM, performing well at the moment and is much further along the development curve than AMC but I think AMC has greater potential for SP appreciation and the current SP represents a great entry opportunity.
I also see NRW Holdings has been awarded the mining contract for the Roper Bar #IronOre project, Australia, owned by NRR, where Amur has an investment in a CLN. An offtake agreement for the 4.6Mt of DSO from the project is in place with Glencore. https://www.nsenergybusiness.com/news/nrw-roper-bar-iron-ore-project-contract/. Not many AIM mining companies have the luxury of an income such as this.
AMC - LICENSE SECURE!! - TEO EXTENSION GRANTED!!
On Tuesday Amur Minerals announced to the market that their application for extension to their TEO due date has been extended. The company announced pre Christmas that they applied for an extension to their December deadline due to unprecedented delays caused by Covid-19.
Amur also announced that they are ready to announce to the market their 2018 drill results which will increase the overall Class 1 Nickel resource.
2021 should play out favourably for AMC given the huge surge in the Nickel price, driven by the move away from fossil fuels for transport and energy needs.
AMC - RUSSIAN TAKEOVER OR BFS – DEAD OR NO DEAL IN 2021??
As some of you will likely know by now I am a keen follower of AMC and where this project may end up. Nobody can argue that the scale of the asset is not enormous.
I think 2021 will be a very important year here and strange things are stirring.
We have had radio silence from the BOD for a very long time now and maybe something is brewing behind closed doors. Adam Habib was brought in and did a great job with the NRR deal securing a solid income for AMC which is very uncommon for an AIM listed mining Exploration Company. This helped raise the profile of AMC. He also was successful in negotiating a non-binding off take with who many assume Glencore given his contacts with them. Adam sits on the NRR board alongside a Glencore Director. They will be well aware of the strategic importance of the AMC’s licenced mining zone, Kun Manie.
Given the importance of this asset is in Russia and opening up the Amur region, there will always be interest from the home country. Many believe there have been Russian companies getting involved given how quick the shares from a recent placing were snapped up. Adam recently was up for re-election at the companies AGM and very oddly was not re-elected. No normal PI or the BOD would have voted against Adam. This has led many believe that interested Russian parties who secured many shares in the recent placing voted him down. This was not because Adam was doing a poor job, but simply to reduce the chance of Western takeover and reduce the takeover price for themselves or in the interest of bigger players.
Why I think the next few months will be very interesting.
- The BOD is now in radio silence mode. Given that so much news was due, this is very strange. The board have been quite in the past but things feel different this time. Nickel price is booming and EV and the fight against climate change is front and centre of most governments.
- Adam has recently taken up a new Deal Making role with EUZ (Europa Metals). This to me suggests we could be in final takeover negotiations and his role of securing investment are complete with the NRR deal. As president of AMC, I don’t think he would be allowed to take this role due to complicit of interest and his need to secure a binding off take deal crucial to take us to BFS (Western Banking Feasibility). The Russian equivalent TEO would be enough to secure bank financing. AMC’s TEO is due to be submitted any day now with Q1 being the latest as per their RNS regards this. This was slightly delayed at the start of December due to Covid 19.
- Age of BOD – given the age of Robin Young and co. an easy deal now would make sense to enjoy the fruits of his hard work over the years. He will want the best price and I believe shareholders will get a good deal. Proceeding with the BFS route would take maybe 2-5 years minimum. The decision to allow Adam to take the role at EUZ suggests they are concentrating on doing a deal with a Russian Company. Radio silence suggests an NDA could be in place. So much value increasing news is due which I believe interested parties would want to hold back as they trash out a deal.
- Given the time it takes to bring a mine such as this into production (approx. 7 years) means interested parties need to move now.
2021 Deal or No Deal for AMC!!
Still ramping this. You only need to look at the Stockopedia rating - Sucker Stock...
.
Don't knock it - it's gone up 25% since June when this thread was started, that's about double the spread :-)
Yawn, will you please stop ramping this penny stock which is little more than a pipe dream of a "potential mine". Don't extrapolate todays commodity prices with what is little more than dirt in the ground
By all means tell us all how great this stock is once there is something to shout about.
I held this stock for 3 months, one day in October I managed to get out with £14.09 profit after all costs.
I wonder if I will regret losing the faith?
There is a great Telegram group with about 400 people in it with some very interesting discussion. They can answer any questions you have or keep you up to date with things going forward if you decide to invest again.
The link is the link
https://t.me/amur_minerals
The BOD are very quiet at the moment. We think there could be interested parties discussing takeover but all speculation. They are in the right sector at the right time and they have never been this silent. Q1 will be very interesting.
That's useful, thanks.
Both articles are well worth reading.
https://www.argusmedia.com/en/news/2178858-nickel-price-nearing-key-threshold-to-spur-investment
https://www.metaltechnews.com/story/2021/01/20/tech-metals/electric-mobility-metals-inflection-point/439.html
Enjoy
Did you see someone just bought 7.5 million shares?
There is a lot of positivity surrounding Nickel at the moment.
"6 minutes in for Nickel."
https://www.youtube.com/watch?v=QcgMy5r6T9U&feature=youtu.be
Biden in the White House. USA back in the Paris Accord. Time to start the renewable energy and EV engines which will drive the price of Nickel even higher. Now trading at over $8 dollars per pound.
Does anyone with mining experience have a view on the progress report on the TEO for Kun-Manie recently released? Yes, there are delays - is this concerning or understandable in the current difficult operating environment? Clearly, the market reacted negatively, but was this just those looking for quick profit, or genuine fear of non-delivery or further problems?
And what about the updated resource estimates?
Since this is highly speculative for me because I don't understand the sector, views of those that do would be highly appreciated!
Thanks,
Robin
Hi Robin,
It has been an eventful few weeks for AMC holders.
Let me put your mind at ease. The TEO delay was a big disappointment but all in all was understandable given the spike in Coronavirus cases in Russia from Oct to now. With everyone working remotely and works outsourced made AMC’s task of delivering one of their most important documents much more difficult.
AMC were proactive and asked for an extension just in case it was needed back in Oct when the cases started to rise. I have heard that many miners did the same by direction of the Russian authorities themselves but hard to know how true this is.
AMC’s recent RNS update shows the resource is even bigger than previous figures and the mining life has gone from 15 years to 30-40 years. Huge increase in fundamentals. The TEO was confirmed to be in the final stages and I believe the Russians have seen a draft without the few final pieces that were held up due to the delays which have been advised will be completed no later than Q1 next year.
The positives are;
The negatives are;
Before Christmas I think we will get confirmation of TEO extension with its official submission confirmed early next year and maybe an update on JORC figures before Christmas which will be huge for our off take agreement.
Good luck with your investment and hope the above gives you some reassurance or helps make up your mind to choose to sell.
Thanks for this. Do we know when news on the TEO extension might come? Steady decline in share price is quite worrying. Thanks.
Is anyone else holding this share concerned that the company hasn't yet confirmed that its TEO submission deadline has been extended beyond December?
The Russian government has extended all licenses by 12 months so no need to panic about that.
Hi RetireYoung,
Interesting day today for AMC.
There is a great Telegram group with some very interesting members. They can answer any questions you have.
The link is the link
https://t.me/amur_minerals
Let’s see what tomorrow brings. :)
A nice little write up regards the metal miners who are gearing up to benefit from the much predicted rise of EV across the world.
My personal favourite AMUR Minerals (AMC) gets a mention.
I particularly liked the 0.34p forecasted price in the last paragraph. A link to the full article is below.
https://seekingalpha.com/article/4389090-top-2-battery-metal-miners-for-lithium-cobalt-nickel-1-for-graphite-and-manganese?utm_source=feed_articles_investing_ideas_all&utm_medium=referral
Nickel
Amur Minerals Corp. [LSE:AMC]
Amur owns the massive scale Kun-Manie nickel-copper sulphide deposit in Russia. Grades are reasonable and if the project gets funded and into production there is potential for a 40kt pa nickel production operation which should be very profitable. The average nickel grade is 0.75%, copper is 0.21%, cobalt is 0.015%, platinum is 0.16 g/t and palladium is 0.17 g/t. Additional minor amounts of gold and silver will also be recovered but have not been estimated. The Project has a resource estimate of 1,581,000 nickel equivalent tonnes, with more than 76% of the resource identified as Measured and Indicated.
In a new recent development Amur has bought a 19% equity stake in Australian iron ore near term producer Nathan River Resources, who own the Roper Bar Project in Northern Territory, Australia. It has an estimated 446m tonnes of JORC resources with an iron grade of 39.9% and presently 4.76m tonnes of JORC reserves at 60.1% iron. Expected near term production is 4-5m tonnes pa. The US$4.67m investment was done using the majority of a recent £6.1m capital raise. The purpose is to gain near term consistent future cash flows for Amur that can help progress their Kun-Manie Nickel-Copper Project. The expected return is a 14% convertible bond, which can later be converted to equity in Nathan River Resources.
The current market cap is only GBP 30m. Analyst's price target is shown on Yahoo Finance as 0.34. I assume this is pounds [GBP]. If I am correct then that compares very favorably to the stock price of 0.0219 pounds [2.19 pence], being 15.5x higher.
AMC's Nickel deposit based on current drill proven figures compared with other world Nickel Deposits.
2018 drill are expected to significantly increase JORC and deposit size as below RNS snippet. The market is waiting for these figures to be released which I assume will be included within the TEO to be submitted in December. (Russian Banking Feasibility Study).
TEO being granted agrees mining is economically viable and opens AMC up to Eastern Metals Suppliers, such as Norilsk Nickel, sourcing large Class 1 Nickel deposits.
Many expect AMC will go further down the road and work towards a BFS ( Western Banking Feasibility Study). This would open AMC up to large Western orientated companies such as Glencore etc.
Having both will help increase any takeover value and final payoff for shareholders in an exciting time for EV and the renewable energy sector.
.
For any of you interested in following this stock, there is a very good Telegram group chat.
https://t.me/amur_minerals
Good luck to those that choose to invest.
App link https://telegram.org/
AMC Chat link
https://t.me/amur_minerals
The EV Revolution is coming...social media is littered with adverts such as this.
Most if not all main car manufacturers are switching to Electric Vehicles. The current and long term future battery technology will require huge amounts of Nickel with some batteries 80-90% Nickel.
.
The price of Nickel rising steadily as the demand increases and the world plans to make the shift to renewable energy sources such as EV and battery power in a Post-Covid World.
AMC - EV Revolution and Nickel Demand
Let’s hope Biden wins tonight and fulfils his promises of moving America away from fossil fuels and towards renewables.
This could really kick start AMC’s and many other miners share price, in AMC’s case building momentum towards TEO and other expected good news such as 2018 Drill results and Binding off take agreement.
Competition for Nickel will only encourage China to make more deals with miners such as AMC as they adopt a policy of being less reliant on Western economies.
In a future driven by electric vehicles, China is poised to dominate if the U.S. does not transform its automobile industry in coming years.
"Over the next five years we anticipate Chinese players across the EV supply chain to aggressively enter the overseas market," UBS analysts wrote in a note Wednesday. "We believe China materials costs are lower than the overseas market. If this advantage can sustain, China could realize a cost advantage over ex-China players."
Through deals with mines and other industry players, China has secured the minerals and key materials for battery production for at least the next five years, said He Hui, senior researcher on China's new energy policy at The International Council on Clean Transportation.
By 2030, McKinsey estimates more than a third to almost half of vehicles sold in China and Europe will be battery-powered and plug-in hybrid electric vehicles. The anticipated market share for the U.S. is far lower at roughly 17% to 36%, up from 3% this year.
https://www.cnbc.com/2020/10/2...
Looks like Trump is going to be re-elected.
I would not be so sure about that......postal votes still being counted which are predicted to massively favour democrats.
AMC doing well though. :)
Good news for AMC and those invested in the renewable energy and metals sector.
The election of Joe Biden as president of the US could reduce global heating by about 0.1C, bringing the goals of the Paris agreement “within striking distance”, if his plans are fulfilled, according to a detailed analysis.
Biden’s policy of a target to reach net zero carbon emissions by 2050, and plans for a $1.7tn investment in a green recovery from the Covid crisis, would reduce US emissions in the next 30 years by about 75 gigatonnes of carbon dioxide or its equivalents. Calculations by the Climate Action Tracker show that this reduction would be enough to avoid a temperature rise of about 0.1C by 2100.
AMC - All Going To Plan
After the markets taking a hammering this week including AMC, they have just released some very positive news to steady the ship.
They have released an update on their Iron Ore (NRR) Investment including board positions on Nathan River Resources and NRR Group Pte Ltd.
"The loading of the first vessel has commenced using some of the low grade DMS iron ore stockpiles that were in existence prior to the purchase of Roper Bar by NRR. This cargo will be approximately 58,000 tonnes and has been pre-sold by the Offtaker giving NRR an expected revenue from the sale of approximately US$3.6 million.
With the recent injection of additional equity capital announced on 27 October 2020, NRR is now targeting four to five further vessels by the end of this year. The processing of previously mined blocks has also commenced, and the transportation of existing stockpiles and processed blocks to port is now operating 24 hours a day. The Roper Bar site is now fully equipped and expected to commence the mining of new blocks in due course.
Prior to the recent capital raise announced on 27 October 2020, NRR had also carried out an independent valuation focusing on the building, infrastructure, plant and equipment assets. This indicative independent valuation increased the equity value of these assets to A$76 million. A more complete revaluation of its assets will be carried out in 2021.
Under the terms of the CLN, Amur is entitled to a seat on the Boards of Nathan River Resources and NRR Group Pte Ltd. Mr. Adam Habib, President of Amur, is now on the Board of Nathan River Resources, and Mr. Robert Marsden who was nominated by Amur, has been appointed to the Board of NRR Group Pte Ltd.
Mr. Marsden is a Mining Engineer with over 25 years of international experience, 18 of those years with Rio Tinto. In 2013 he established an independent mining consultancy, providing technical, economic, and strategic advice to the resource sector covering Australia, Botswana, Brazil, Canada, Finland, Ghana, Madagascar, Peru, South Africa and Zimbabwe. During this time Mr. Marsden has consulted on iron ore projects in Australia, Brazil, South Africa and Canada.
Whilst with Rio Tinto, Mr. Marsden conducted the commercial review of over 40 investment proposals on behalf of the Investment Committee covering acquisitions, disposals, project funding and project expansions.
As well as representing Amur's investment in NRR, Mr. Marsden will also work alongside the Company's management on the Kun-Manie nickel/copper sulphide project."
This is the Cash Flow (not common for an AIM company) that will help deliver TEO (early Dec and Western BFS next year.
https://www.nathan-river.com/projects
Talon & Amur both doing well on the back of improving nickel prices :)
Amur Mineral's Globally Significant Class 1 Nickel Deposit
S&P Global Platts Pricing Director for APAC Metal Markets Julien Hall talks to Platts battery metals experts Joyce Zhang and Jiahong Ong for an overview of nickel use in electric vehicle batteries, the main fundamental drivers in the market, and how the pricing behaves, to get a better sense of how hot the nickel market really is.
https://www.spglobal.com/platts/en/market-insights/podcasts/battery-metals/101920-nickel-price-benchmark-china
A summary of the attached podcast is as follows;
Nickel Sulphate
- Tesla offer of Giant Contracts to mine more Nickel
- Nickel being described as the 'new gold'
- Key Driver = EV Growth
- 2.1m EV’s in 2019 - 35 KT of Class 1 Nickel (currently only 3% of current nickel mining)
- 114m EV’s forecast by 2030 - 925KT per year (more than 14 Times Increase on current Nickel Mining needed in a short space of 10 Years)
- If Paris Climate Agreement is fully adopted is expected to increase EV growth even further
- This would 36% Growth per Year in EV Demand
- Reaching 245 million EV’s in 2030 and Class 1 Nickel Demand of 2000KT per year
Supply Side
- S&P Global ratings expect 2.3 Million Tonne of Nickel to be mined and processed by the end of 2020
- Battery Grade Nickel Sulphate can only be produced economically using Class 1 Nickel (most pure form) - AMC are sitting on 1.58 Million Tonnes of Class 1 Nickel
- Battery Supply Class 1 grade makes up only 1 Million Tonne - 37% of Current Annual Nickel Production
- Huge Supply Challenge for Global Nickel
- Class 1 Nickel Sulphide deposit discoveries are very rare, only 1 in last decade
You know I might end up taking a speculative position in AMC as I like the EV & nickel theme.
My only worry is the location of AMC’s resource, would the supply go to China & Japan in your opinion?
I like Talon particularly because the resource is in the US close to a significant point of demand offering security of supply.
https://www.juniorminingnetwor...
Seriously not trying to start a fight! But if you and others like the nickel small cap miner theme its well worth a speculative nibble too!
I think Glencore will be our binding off take partner.
Why I think this is because AMC have also recently invested in an Iron Ore mine in Australia and which has stockpiles ready to ship. The first shipments set off this week and AMC have already received their first payment. Investors believe we will get an RNS this week updating us on the Shipment and what it equates to for AMC shareholders.
https://www.proactiveinvestors.co.uk/companies/news/930858/amur-minerals-receives-first-interest-payment-from-nrr-investment-930858.html
The Roper Bar investment also indirectly links AMC up with Glencore who are also involved in the project. They also own the Bing Bong port in Australia where the iron ore will be shipped to the Chinese markets.
Another reason I think it will be Glencore is our President and Executive Board member Adam Habib. He has strong business connections with them. The Australian investment and a link up with Glencore would really secure the threat of any funny business down the line.
https://www.proactiveinvestors...
With TEO to be complete on our before the 1st of December, it is going to be a very interesting period for shareholders.
Once TEO is complete, AMC will work towards the BFS. This is the Western Equivalent of the TEO. The money from the Iron ore investment will go towards this. It is rare for a mining explorer to have solid cash flow and it protects shareholders from the much hated dilution. This is where I think AMC will be taken out by a big player like Glencore.
Good luck if you decide to invest.
Also regards your concerns around AMC being and exploration company in Russian territory.....you only have to look at EUA as to what is possible there...a share price at under a penny in 2019 to highs of 37p and currently going through takeover talks.
I'm fully aware of what happened with Eurasia Mining (LON:EUA), but well worth bringing to attention for others who aren't! Tbh it is what retains my interest in a speculative punt here! Will watch with interest for a breakout and close above 4p.
Have also done well on, POG, POLY, TSG which are all Russian based miners so not adverse to Russia at all.
In the case of EUA and AMC, i believe both companies were rated at around 1billion mcap many years ago. I think I read somewhere that the major investor at EUA took his main stake at around 5p per share years back?
Can I ask if you're you invested in any other small cap miners yourself or 'all in' on AMC?
I was in in GGP at 7.56p and it is now low 20's. I sold around 17p. I have no doubt it will go higher as they are in the process of drilling their 100% own Scallywag deposit in Australia. Everything is pointing to very good results like their JV at Havieron with Newcrest.
The other one I was in was POW (Power Metal Resources). I sold there at 1.35p to transfer across profits to AMC though I wish I had left some in as it is now hitting 2.20p and having a very good day.
With the way EV and the Nickel demand is going and the tiny market cap at AMC, I cannot see anything close to the potential this company offers. The Fundamentals are all there and only set to improve with the TEO only around the corner in early December.
This could be the catalyst that rises the SP to a more fairer value although I think an imminent update on proceeds from their Iron Ore investment will start this process.
Disappointed now I sold up (LON:POW)….flying now.
I also saw this last week - $TSLA Reportedly in talks with BHP over Nickel supply agreement - press (Tesla Inc)
Bhp said to boost output on demand for electric car battery
Nickel Prices rising steadily with growing demand
Global miner and commodities trader Glencore (LON: GLEN) is close to securing nickel supply deals with automakers and battery producers amid a looming squeeze in the market and Tesla CEO Elon Musk’s recent call to miners to produce more of the metal.
https://www.mining.com/glencor...
Electric car sales are on the rise – is coronavirus a turning point for the market?
Lockdowns across Europe to curb the coronavirus pandemic drastically changed how we move around the world. Work-from-home restrictions, furlough schemes and job losses left millions of cars gathering dust in driveways.
It is not surprising that the demand for new cars plummeted. In Germany – Europe’s largest car market – new car registrations in the first half of 2020 declined by 35% compared to the same period in 2019, and during the height of restrictions (April), sales slumped a historic 61%. Sales for 2020 across the rest of Europe’s largest car markets in the first half of 2020 performed even worse: Spain (-51%), UK (-49%), Italy (-46%) and France (39%).
But one segment of the car market is still growing. Electric vehicle (EV) sales, both full battery electric vehicles (BEV) and plug-in-hybrid electric vehicles (PHEV) have bucked the trend, not only in terms of their market share, but also in absolute terms. In Germany, EV sales from January to June increased from 47,584 in 2019 to 93,848 in 2020, supported by particularly strong PHEV growth.
This is an incredible performance, given the current economic and public health situation. Similar trends are evident across Europe with France, for example, seeing an even higher shift to EVs in 2020.
https://theconversation.com/electric-car-sales-are-on-the-rise-is-coronavirus-a-turning-point-for-the-market-144706
EV Metal Index surges 64% as Europe tops China
Europe has now overtaken China – not long ago responsible for every other electric car sold worldwide – as the globe’s largest EV market.
Over the first seven months of the year, Europe’s electric vehicle sales (including plug-in hybrids) outpaced that of China, reaching the half-million mark thanks to record-breaking monthly sales of 53,000 units on the continent in July.
More remarkable, considering Chinese so-called New Energy Vehicle (NEV) sales data also include fuel cell and commercial vehicles. July was also the first month of annualized positive growth in China with sales approaching 84,000 units – 48% year on year growth.
China still leads the charge in full battery electric vehicles (BEVs), however. According to Schmidt, a market researcher, for the year to end-July 2020, 269,000 BEVs were sold in Western Europe compared to 373,000 in China.
2020 vision is bright
Car sales are always lumpy and none more so than BEVs, where changes in incentive schemes and government regulations play an outsize role in buying decisions.
Beijing deflated its domestic EV market in June last year when it unexpectedly slashed subsidies. In July last year the EV Metal Index tanked 43.6% following the incentive scheme adjustments, but with action shifting to Europe and more certainty about Chinese green car policies, the second half of 2020 should remain robust.
According to Schmidt, September could be the breakout month with volumes surpassing 100,000 units in Western Europe – thanks to increased deliveries of Tesla on the continent and the launch of Volkswagen’s ID.3, which alone has racked up more than 30,000 in advance orders.
If Europe does go down this road, there is still a chance (granted an outside one) that 2020 could come close to the 2019 index which ended the year at $2
www.mining.com/mining-com-ev-metal-index-surges-64-as-europe-tops-china
The Move to EV
This Video is a few months old now and possibly been seen before, it gives you some idea of the scaling up with EV batteries and Powerwall units that will happen over the next 10 years. You can understand why Elon Musk says he is more interested in the electrification side than the car business. Well worth a watch if you haven't seen this before.
https://www.youtube.com/watch?v=9AM2ptpk71g&feature=emb_rel_end
Judging by this, I don't think Nickel is going out of fashion any time soon .
Martin - it's clearly Hughes87 with a new name. Lol.
Great - so we have another thread ramping this share by another poster who keeps posting to raise it up the listings. How many threads is that now 5,6 ? Come on Stockopedia - we don't pay our subscription for this - we can get this ramping for free at ADVFN....
There are other investors engaged in this thread. If anyone should be reported it should be you for negative comments and no knowledge.
BMW’s Move to EV
BMW are planning to release 23 electrical vehicles in 2023.
12 of these will be fully electric.
Hydrogen vehicles may be being researched at the moment but they are only viable for larger varieties.
At present infrastructure is gearing up for plug in electric.
You only need to look at the car adverts to see what is most popular and viable.
Huge world renowned companies known best for their fossil fuels business such as BP are even adopting the move to the ‘Electronic Vehicle Age’.
Battery capacity increases, pushing up demand for materials...
This is a fairly long and detailed document which most will probably not read from start to finish so I've picked out what most on here will be interested in.
https://www.iea.org/reports/global-ev-outlook-2020
The ongoing trend of increasing battery capacity is projected to continue. By 2030, battery electric vehicles are assumed to reach an average driving range of 350-400 km corresponding to battery sizes of 70-80 kWh. In addition to battery size, another important variable in projecting total battery capacity is the proportion of battery electric vehicles and plug-in hybrid electric vehicles in overall electric vehicle sales.
In the Stated Policies Scenario, global electric vehicle battery capacity increases from around 170 GWh per year today to 1.5 TWh per year in 2030. In the Sustainable Development Scenario, demand of 3TWh is projected. Despite ambitious electrification in the Sustainable Development Scenario, modes other than cars account for only 11% of overall battery demand in 2030, highlighting the centrality of electric cars in the battery market over the next decade.
The demand for the materials used in electric vehicle batteries will depend on changing battery chemistries, nickel cobalt aluminium oxide (NCA), nickel manganese cobalt oxide (NMC) and lithium iron phosphate (LFP) cathodes for lithium-ion (Li-ion) batteries being the most widely used today.
The estimated material demand for the batteries of the electric vehicles sold in 2019 was about 19 kt for cobalt, 17 kt for lithium, 22 kt for manganese and 65 kt for nickel. For battery needs in the Stated Policies Scenario, cobalt demand expands to about 180 kt/year in 2030, lithium to around 185 kt/year, manganese to 177 kt/year and class I nickel to 925 kt/year. In the Sustainable Development Scenario, higher electric vehicle uptake leads to 2030 material demand values more than twice as high as the Stated Policies Scenario.
Thanks for the link. I can’t deny the speculative potential of Nickel for the reasons you outline so regularly.
Some good suggestions there. Personally, Amur is too high risk for me but I like the look of Talon.
Joint venture with Rio Tinto, resource is geographically well positioned and it has a stock rank of 79 rated at High Flyer.
Talon has bagged and Amur has sagged
Proactive Nickel Article
Mention of AMC seems to be more frequent as demand for nickel hots up.
https://www.proactiveinvestors.co.uk/companies/news/925730/are-small-cap-nickel-stocks-a--buy--as-tesla-ceo-sets-challenge-to-miners-925730.html
Some questions regarding the Nickel market:
- In PGM there are royalties companies, so called "streamers", who specialise in Gold Silver Palladium etc. Companies like Wheaton and Franco Nevada are names that I hold. They offer domain expertise and diversification. Is there an equivalent in the Nickel space?
- Again in PGM a typical approach would be to combine a good big company with a more speculative small cap. Reading the literature Gmk Noril'skiy Nikel' Pao (LON:MNOD) would seem to be a candidate for the "good big company". For the speculative small cap exposure is there a small nickel producers ETF that is tradable? Essentially equivalent yo GDXJ and SILJ - both of which I hold ?
- Do you "fade" your Nickel, holdings with trades on the Nickel spot price?
Hi Hughez87
Many thanks for highlighting Amur.
I do occasionally invest in both the mining and the O&G sectors and experience has taught me it is easy to get caught up in the narrative and be over optimistic and not give appropriate weighting to the possible risks.
So generally I prefer to invest in mining companies only once they look financially stable with positive cash flow and a clear path to increasing commercial production. Waiting until such things are in place does mean that the potential gain is less but also the likelihood of a significant loss is much reduced.
Amur certainly has a compelling narrative.
It has Asia’s largest undeveloped nickel copper sulphide deposit. It is situated in a well established mining area in East Russia with good access to China, Japan and Korea who are large consumers of nickel.
There is currently Russian government support for this and other projects and the infrastructure required.
The future is likely to see the development and widespread use of electric vehicles. Climate change and clean renewable power is becoming a priority.
Electric Vehicles are reliant on effective and efficient batteries which are fast being developed and the cathode chemistry involved is becoming more nickel rich.
Nickel prices are rising and although in the short to medium term there is likely to be overproduction this is predicted to become a shortage longer term.
Amur’s Kun-Manie mine has been assessed as being break-even at a nickel price of $6.16/pound. Currently nickel is at $7.5/pound and is predicted to be over $8/pound longer term and double current prices by 2027.
In order to fulfill the requirements of their licence Amur have to complete a Russian feasibility study (TEO) by December 2020. Using the drilling results from the 2018 campaign this needs to cover a geology, mining, environmental, technical and economic assessment of the project.
Schedules are tight but good progress has been made. Metallurgy work has delineated two concentrate income streams - nickel and copper and Amur has been in discussions with a global off- taker to obtain details of the cash for each of these streams to inform the feasibility study (TEO).
The results are very likely to enhance the NPV of the project.
They have also negotiated a non-binding agreement for said global off-taker to absorb all their production and hope to get a binding agreement signed to work in partnership with them regarding financing the project before the December TEO completion.
A bankable feasibility study (BFS) will be expensive (estimated at significantly more than $13m).
A mine plan approval is hoped for by 2021 and production by 2024 just in time for the surge in EV battery requirements.
To add to this they are also in the market for an acquisition (and have assessed a few) that has commercial production and can offer immediate cash flow once acquired.
To fund this it will require a capital raise and share dilution.
Exciting stuff and if it all goes to plan this will be a multi-bagger from the current share price.
So what might prevent this?
Currently they have no revenue and an operating loss of about $2m annually.
Available cash is $400k matching current debt.
They need to have a successful capital raise to meet their acquisition aspirations but at what share price and how much dilution?
What are the chances of them finding a suitable buy that will produce immediate cash flow?
Presuming that they complete the feasibility study (TEO) by December and if this doesn’t happen for any reason their licence could be in jeopardy. They then need to fund the BSF.
If the deal with the off-take partner fails or is delayed they do not have the funding for the project.
And if they do make a deal what will be the price? Deals usually take longer than shareholders wish and in this case they have mooted a very tight schedule. I somehow doubt a deal will be struck before the TEO is due.
The BFS by their own account will be expensive.
Then there are the time scales – what happens if they miss the December deadline. Will they loose the licence.
If there is a second or third wave of covid will this add to delays to commercial production. Almost certainly. As humans we tend to be over confident particularly if we are selling a product or idea so in any event a 3 year time frame to production mooted by management is likely to overrun even if things proceed fairly smoothly.
Then there is the commodity risk. There is no guarantee that nickel prices will rise or even that EVs will be taking over in 3-5 years. All this is convenient, if believable, supposition.
The Russian government is currently benign and even helpful towards such projects. This can change and also has to be a risk. Both Russian regulations and the politics could play a role in creating problems for Amur.
Just recently Highland Gold (which I held) was sold relatively cheaply with Russian benefactors.
So many factors need to line up and assigning even a relatively generous probability to each still leads to the likelihood of a poor rather than successful outcome.
Then there are opportunity costs. Three years minimum to commercial production with share price volatility and not all of it upwards for example missed deadlines and a capital raise with share dilution pushing the price the other way. How much could a safer investment return during this period?
I am not saying I would never invest here but I would want much more certainty in the outcome. My fingers have been burned too many times in the past.
I will certainly keep an eye on them from here particularly regarding the TEO and possible acquisition.
One entry point might be at the capital raise if other factors have become clearer.
Also if you are a trader I am sure the inevitable volatility will offer opportunities but that is not my style of investing.
An interesting little company and one which has a great story to it but also one in which it is easy to get lulled into an over confident or over optimistic view or get too wedded to the narrative. I speak from past experience elsewhere.
Good luck with whatever you decide.
Regards
Iron
good summary of the pros and cons... thanks Iron. I have a small stake in this share, which I consider the riskiest in my portfolio. I will increase this stake if good news flows and risks are reduced. However, I bought them knowing full well I have a high chance of losing my money. My biggest fear is that a very small company sitting on a massive asset is like a lion cub sitting on a big kill in the Serengeti... sooner or later it's going to get chased off by a much larger lion or a bunch of scavengers
Hi Iron,
Many thanks for your input, it’s beats my posts being called ‘garbage’ and ramping. At least you did a bit of your own research.
I am a firm holder of this stock. I refuse to trade it as I know news of an off take or investment with a big name could send it rising into double figures where it should be considering the asset it has.
The have updated the market recently via an RNS to inform them that the TEO was on track despite Covid. The Russians also have no want to discourage foreign mining explorers and investors, in fact they want quite the opposite. To answer Retire Young’s comment, an off take with a major house hold name would further protect the company from any Russian ‘funny business’.
I am excited about this share and I only share articles regards Nickel and EV because I genuinely believe AMC will go places.
All the best and hope you well if you get onboard this one and your other investments.
Hi IronPyrites,
With AMC's recent Iron Ore investment of which they received their first payment last week (see last RNS) I would like to know if you decided to buy in here?
With the investment and subsequent Cash Flow the company have advised investors that there will be no need for any further dilution and the SP will be allowed to grow to reflect the true value of AMC considering their huge asset.
My wife and I invested a small amount here a while back and recently topped up a bit more, given news shows company seems to be heading the right direction. But still less than 3% of my portfolio and what I consider to be my riskiest investment. Let's see what happens next.
Hi Retireyoung,
In my opinion I think your and my investment here is safe. In the short term we have;
Good luck.
LG87
Hi IronPyrites,
The company also released an RNS yesterday to inform investors that they will be taking shares at current share price instead of salary. A very positive sign that they are confident that the share price will be heading higher.
Good Luck
Nickel market is overstretched according to the same news source you are using to ramp this share.
https://www.mining.com/web/stainless-surge-revives-nickel-but-surplus-still-looms/
Rapidly rising stainless steel production in top consumer China has helped to preserve demand and prices of key ingredient nickel, but analysts still expect a supply overhang of the metal valued for its anti-corrosive properties.
Benchmark nickel prices on the London Metal Exchange (LME) are near their highest in more than seven months at around $14,300 a tonne and up more than 30% since touching a 14-month low of $10,865 in March.
Covid-19 lockdowns and stalled manufacturing activity had led analysts to expect a large drop in production of stainless steel, accounting for about 70% of global nickel demand estimated at about 2.35 million tonnes this year.
But vast amounts of fiscal and monetary stimulus in China have fuelled a surge in economic activity, particularly in the infrastructure and construction industries, major consumers of stainless steel.
Macquarie analyst Jim Lennon estimates that Chinese mills produced 2.875 million tonnes of stainless steel in July, up 4.8% year on year.
“More importantly for nickel, the high-nickel containing 300-series grades of stainless saw growth of 17.5% year on year in July to 1.46 million tonnes, an all-time high,” Lennon said.
“But we’re still likely to see a surplus around 100,000 tonnes. Demand is better, but supply is better, too, mostly because of China and Indonesia.”
Traders say much of nickel’s gains are due to bets on higher prices, as can be seen in open interest for the LME’s nickel contracts.
This is partly speculative and based on Tesla boss Elon Musk urging miners to produce more nickel “in an environmentally sensitive way”.
Analysts say that most of the stainless steel produced is being consumed and that inventories in China are falling.
“The nickel market is probably where you get the starkest comparison between China and rest of the world in terms of economic growth and demand,” said Citi analyst Oliver Nugent.
Citi expects the nickel market to be oversupplied by 135,000 tonnes this year and 117,000 tonnes in 2021.
“In the base metals complex, nickel looks the most expensive compared to production costs,” Citi’s Nugent said.
Russia has $1.5bn plan to dent China’s rare earth dominance
Some good news for anyone invested in mining (such as AMC) in the Russian region. Some investors are put off by it not being one of the 'safer' mining locations. Fear not.
Russia plans investment of $1.5 billion in rare earth minerals, critical to the defence, telecommunications and renewable energy sectors, as it strives to become the biggest producer after China by 2030, a top government official told Reuters.
Russia’s initiative is in line with other countries, such as the United States, which are also trying to curb their reliance on China, home to 63% of global rare earths production and 37% of global reserves.
China’s dominance is so established, it is hard to weaken.
Russia has reserves of 12 million tonnes, or 10% of the global total, and its government is willing to back any foreign investment......THIS IS VERY IMPORTANT.
Alexei Besprozvannykh, Russia’s deputy industry and trade minister, said Russia is offering reduced mining taxes and cheaper loans to investors in a list of 11 projects designed to increase Russia’s share of global rare earths output to 10% by 2030 from 1.3% now.
The Russian projects will require at least $1.5 billion in investment, he said.
China will keep its market dominance, but Russia’s “goal is to be at least the second after them by 2030,” Besprozvannykh told Reuters in an interview.
So far rare earth processing is almost totally controlled by China, with the exception a plant in Malaysia, operated by Australia’s Lynas Corp, and the U.S. is reviving production.
The 11 projects, which include developing the Tomtor deposit in Russia’s far east, will allow Russia to become almost self-sufficient in rare earth elements by 2025 and start exports in 2026, the deputy minister said.
By 2024, Russia’s production of rare earths concentrate may reach 7,000 tonnes a year, he added. The U.S. Geological Survey estimated Russia’s 2019 production at 2,700 tonnes.
(By Anastasia Lyrchikova, Gleb Stolyarov and Polina Devitt; Editing by Andrew Osborn and Barbara Lewis)
https://www.mining.com/web/russia-has-1-5bn-plan-to-dent-chinas-rare-earth-dominance/
You obviously don't understand the lead time to turn a deposit into a mine.....7-10 years in can take....THE EV World will have really started to put strain on the supply by that stage.
Companies such as AMC need to develop their assets NOW. This is where I believe they are way undervalued in terms of their current SP. Majors will be eyeing them up soon enough. They have an asset of 1.58 Million Tonne of drill proven Nickel....and other metals included.
The short to medium term demand and price fluctuations are not important....I have previously shared Musk's comments regards this and many mining experts and commentators. You choose to ignore this and decide to call me a ramper and accuse me of talking garbage.
AMC has the added benefit of being a Class 1 Deposit, the type used in EV and the type which will branch out and cause a Two Tier Nickel price....Class 1 obviously being the higher of the two.
Here is an interesting link regards the Nickel Market now and future forecasts.
https://seekingalpha.com/article/4362139-nickel-monthly-news-for-month-of-july-2020
Summary
Nickel spot prices were higher in July, and the LME inventory was about the same as last month. Nickel 'battery' demand forecast to increase by 14x from 2019 to 2030.
Nickel market news - Roskill - Partial demand recovery to support nickel prices in H2. Musk promises 'Giant Contract' for efficiently mined nickel. Battery-grade nickel could run short by 2023.
Nickel company news - Nickel Mines completes move to 80% of Hengjaya Nickel and Ranger Nickel RKEF Projects. Canada Nickel identifies multiple nickel targets on recently acquired option properties.
I do much more than just articles at Trend Investing: Members get access to model portfolios, regular updates, a chat room, and more.
Welcome to the nickel miners news for July. The past month saw nickel prices rise strongly and plenty of nickel news including some very interesting comments from Elon Musk.
Nickel price news
As of July 27, the nickel spot price was USD 6.22, up from USD 5.62 last month. Nickel inventory at the London Metals Exchange [LME] was about the same as last month at 234,852 tonnes (234,198 tonnes last month).
Nickel spot prices - 5-year chart - USD 6.22/lb
Source: InfoMine.com
Nickel demand vs. supply
On June 30, Kalkine Media reported:
Source
The chart below shows a forecast widening nickel deficit from 2023 (note, it is a bit outdated now).
Source: Wood Mackenzie
Battery and EV battery metals are set to take off
2019 to 2030 'battery' demand increase forecast for EV metals - Nickel 'battery' demand forecast to increase by 14x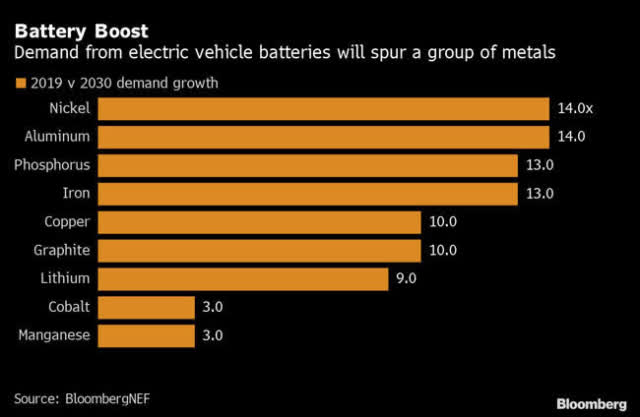
Source: Courtesy BloombergNEF
Benchmark Mineral Intelligence - Simon Moores's - forecasts
Source: Benchmark Mineral Intelligence Twitter
Investors can also read my past article: "Top 5 Nickel Miners To Consider Before The Nickel Boom."
Nickel Market News
On July 21, Investing News reported:
On July 23, Yahoo Finance reported:
Yesterday's RNS at Horizonte (LON: HZM) will, hopefully, swing the spotlight round onto the options for nickel investments on AIM, of which there aren't many, and bring into sharper focus Amur (AMC) in particular.
HZM's chart jump on release of some good news via an RNS.
Our day in the sun might still be a good 12/18 months away but it will come.
"PLEASE MINE MORE NICKEL"
https://www.bloomberg.com/news/articles/2020-07-22/musk-promises-giant-contract-for-efficiently-mined-nickel
New 89% Nickel Cathode Developed - The main Electricity Storing Element of all EVs
More nickel in a battery means it can store more energy. That increased energy density can lead to longer battery life for a phone or greater range for an electric vehicle with each charge.
https://news.utexas.edu/2020/07/14/new-cobalt-free-lithium-ion-battery-reduces-costs-without-sacrificing-performance/
Researchers from the Cockrell School of Engineering at The University of Texas at Austin say they’ve cracked the code to a cobalt-free high-energy lithium-ion battery, eliminating the cobalt and opening the door to reducing the costs of producing batteries while boosting performance in some ways. The team reported a new class of cathodes — the electrode in a battery where all the cobalt typically resides — anchored by high nickel content. The cathode in their study is 89% nickel. Manganese and aluminum make up the other key elements.
By 2040, long-range electric cars will cost less than $22,000 (in today’s dollars), according to the projections. Thirty-five percent of new cars worldwide will have a plug.
Putin could buy it with his petty cash and be privately owned?
Many thanks for highlighting this one. Interesting little company. At first sight it looks like a bit of a barge pole stock. The spread of 18.5% is an instant discouragement. Having said that, Nickel has a great future in industry and the commodity is relatively cheap at present compared with last year. My preference would be to buy a nickel ETC such as £NICK (I hold) rather than Amur Minerals (LON:AMC), but if anyone's brave enough to take a punt on Amur, I wish them well. Thanks again for all the info and links,
The spread doesn't bother me too much as I am not trading and I know the SP will rise steadily. The companies target is complete a Russian Banking Feasibility Study and have it pass at the start of December. Granting of this will be a game changer and green light a takeover bid which will amount to billions for an asset of this size.
The Company has issued Recent RNS's and interviews to confirm that this is still on track despite Covid and announced plans to secure a binding off take for the improved quality and quantity of copper they also have within the asset.
Confirmation of this from what they have described as a 'house hold name' will mean the company is financially stable right up to TEO (Russian Banking Feasibility Approval), takeover and a final multi billion dollar bill. Exciting time for shareholders.
This is an interesting watch from board advisor Adam Habib about 5 Days ago....
https://www.proactiveinvestors.co.uk/companies/news/922754/amur-minerals--adam-habib-outlines-progress-towards-teo-completion-and-offtake-discussions-922754.html
Thanks for that, Cahill. This one definitely merits further study. If the price of nickel goes back up to last year's level, this will have a lot of potential. High risk. High reward.