An emerging Aussie MedTec helping the world deliver care.

For this ‘fundamental’ view on a stock, I delve deep into the depths of the smaller cap realm. It's an ‘emerging’ story that still carries elevated risks, as evidenced by the moderate overall StockRank score. These risks however seem to be moderating as the business continues its growth trajectory and hence why it has been put forward for discussion.
ASX:ALC Alcidion Group
Alcidion (ASX:ALC) assists healthcare organisations by delivering a platform which helps with patient care delivery through clinical decision support, artificial intelligence and real-time visualisation health informatics. These insights extend the full scope of patient care though to organisation management.
Miya Precision is the flagship product, and it is built on a Fast Healthcare Interoperability Resource (FHIR) standard for sharing healthcare information in a compliant manner which helps with patient management. The short description, it is a patient management system for hospitals and medical facilities.

A more simple explanation is that the platform is plugged into the electronic medical record system of a hospital and Miya helps by running clinical decision support algorithms in response to changing clinical data. There are also a range of other products and services that run from the core technology, adding scope to increase stickiness and penetration into a facility.
ALC has customers in Australia and New Zealand, but another real key driver is its more rapid expansion into the UK following the acquisition of Silverlink and ExtraMed over a year ago. While Australian companies have had a chequered history when it comes to investing in the UK, today the businesses have been fully integrated and ALC ended FY22 with at least one product in 39 NHS Trusts (there are 219 in total).
The numbers for ALC currently look like they need clinical treatment themselves. However as with all companies with a market cap of $200 million, hope springs eternal.
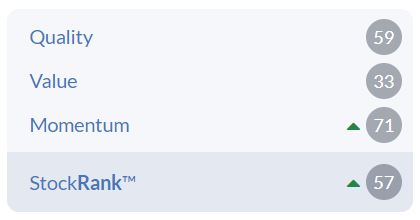
From the end of 2021 the stock has fluctuated, mainly on account of momentum 'rise and falls'. Though it finished 2021 with a StockRank score of 46 and it is now 57 so that is an improvement. Investors will be hoping the fundamentals can now do more of the heavy lifting.
Keen observers will note that the company has been a consistent loss maker, however if the two brokers that cover the stock are to be believed, the company is expected to be profitable in FY23.
Valuations
The first expected profit always skews PE and EV/EBITDA valuations to the expensive side because the earnings component of the equation is still small. What you hope to see is that with continued growth, these rates will normalise.

However, note, this is a sector prone to paying lofty multiples for stoic businesses. I am thinking of mainstays like Cochlear (ASX:COH) and ProMedicus(ASX:PME) here. So, if the MedTech company is good and is gaining traction, rarely do you pick it up for a bargain. COVID will likely be the last time for a while that discounts will apply to any proven MedTech businesses.
A view of a future move towards profitability is also supported by the company who at their AGM showed us how contracted revenue has been progressively growing, with the first half of the year progressing well.

Source: AGM presentation, 30/11/2022
There are only two analysts that look at this stock, so it definitely flies under the radar. But those who do, agree that the best is ahead of them. As they have been increasing their estimates for FY23 in response.

Any prospective increase to FY24 will have to come on the back of more contract wins. Something it did quite well in FY22 with the company achieving a record $57.7M in new sales in FY22.
Financial Health
Given the years of consecutive losses it may not come as a surprise that the company rates poorly from a financial health perspective.

So we look at the availability of cash and what their cash generation is like.
In the company’s latest 4C Cashflow report, unfortunately the receipts from customers were down on the prior qtr ($12m 1Q23 vs $13.96M 4Q22). However, pleasingly they were up strongly on the pcp ($12M 1Q22 vs $6.55M 1Q21). Cash flow is going in the right direction, given the increases in contracted revenue (as shown above) this company is on the cusp of generating consistently positive cash flow from operations.
Speaking of which, total cash on hand currently sits at $16.2M which at its current trajectory of contracted revenue means the company should have enough capital to cross the threshold.

This cash balance doesn’t mean the company won’t need to raise future capital.
The company has a history of making complimentary acquisitions. As interest rates go up, funding for any transaction will likely have to be supported by future raisings, and a decision as to whether investors should participate should be made at that time. While the acquisition to date appear quite shrewd and possibility of future dilution needs to be considered.
Their last capital raising was towards the end of 2021 when they acquired Silverlink PCS Software Limited. They raised $55M in order to add the specialist Patient Administration System provider with exposure to the UK NHS market.
Prior to that in April 2021 it was $17.9M to acquire ExtraMed Ltd, a UK provider of patient flow management software with nine NHS Trusts, six of which were new customers for Alcidion.

Company outlook
While it provided no formal guidance, it did say that its key growth drivers will be new contract wins, retaining existing clients and up-selling to existing customers other services that ALC provide to command more share of the operating wallet.
If we look a little further back, at the time of the June 2022 cash flow statement release the company was more categoric saying,
“We head into the new financial year with $31.2M of contracted and expected renewal revenue, which when combined with our continually maturing pipeline both in ANZ and UK positions Alcidion for continued strong and profitable growth in FY23.”
Be aware
On a minor down note, the company will be removed from the S&P/ASX All Technology Index come 19 December.
A more major consideration is that co-founder of the business, Dr Malcolm Pradhan has stepped away after 22 years with the business. Losing such an influence on the business with such deep knowledge is always a challenge, though it is a challenge that all growing and emerging businesses need to overcome at some point in their corporate stories. Hopefully ALC can manage it well.
Conclusion
There are strains across the entire global healthcare sector. Hospitals are increasingly on the lookout for tools that better manage clinical workflow.
With increased funding from governments in Australia and the UK, tools that boost productivity are an important piece of any improvement strategy. Therefore, notwithstanding the risks, ALC is a company with the right product, in the right place at the right time.
All it has to do now is keep developing relationships and executing contracts.
Hopefully this will lead to a reduction in their own business risk exposure.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
The author holds an interest in ALC which is the topic of this article. This position can and will change at any time without notice.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
6 comments
Thanks Elio, i've been in and out of this stock a few times in the past. But now that things have changed organically and increasing their footprint, probably will be a turn around. One to add to the folio for now.
A few false starts, but it appears to be bottoming out now. Hopefully that will be supported by a continued improvement in the fundamentals.
Thanks Elio
Interesting revue. I have been watching this for a few years now. Probably wait until after the next reporting season before I make a decision.
Makes sense. Sitting on the sidelines to this point means you have earned the opportunity to do just that. Well done!
Thanks Elio, an interesting insight. I have been in ASX:ALC previously but have been watching on the sidelines for a while. I look at a number of other small caps, would you have any thoughts on ASX:COS, smaller cap, strong growth, profitable and paying a dividend. Again a bit under the radar but looks to be getting a bit more interest.
COS run by former North Melbourne Football Club Chairman, Ben Buckley. I know it. Thanks for the suggestion.... have added it to the loooong list, but its definitely worth a look.