An investor's guide to pension plan analysis - an introduction to actuarial assumptions.
Following on from a previous introductory article, it’s time to take a closer look into precisely what actuarial assumptions are and how they can influence a company’s balance sheet. We’ll then take a brief look at the accounting standards that impact them and see where and how they could lead to difficulties for investors.
Broadly, the key assumptions we’ll be looking at are the discount rate, the rate of return, the inflation rate, the mortality rates of employees, the average number of years of service by employees and the actual number of employees.
The discount rate...
A discount rate is an annual interest rate that we use to work out the present value of a future cash flow. I will briefly explain this here but to avoid straying too far from the point, I would strongly recommend anyone to look up the ‘time value of money’ in order to learn more about this. It is a central concept in finance and crops up all over the place, in particular in security valuation.
What is the time value of money then? In short, it is the idea that money today is worth more than money tomorrow. This is because it has the ability earn interest in the meantime. For example, let's say I have the ability to deposit my cash today in a bank account earning 10% interest a year (if only!).
Someone then offers me the choice between £ 100 today or £ 105 in one year’s time. If we were unaware of the time value of money I would choose the £ 105 because it is a higher amount. We’re smarter than that though - we know that if we take the £ 100, we can put it in our bank account and earn 10% interest in a year. This means that the £ 100 will actually be worth £ 110 in a year’s time, which is definitely better than receiving £ 105 on that same date. In a nutshell, that is the time value of money.
In this example we would say that the future value (in a year’s time) of the £ 100 is £ 110, assuming a 10% discount (interest) rate. Equally, that £ 110 a year from now has a present value of £ 100, assuming a 10% discount (interest) rate. Notice that if we change the discount rate, then the present value also changes. £ 110 in a year’s time, discounted at 5% per year gives us a present value of £ 104.76, not £ 100 because £ 110 / 1.05 = £ 104.76.
This technique is how we arrive at the current value of liabilities on the balance sheet to net off against assets. A pension plan promises to pay out benefits in the future (future cash flows), so we must discount them back to today to find out what they are worth right now. Perhaps you can start to see how the discount rate plays a big role in determining what figure we arrive at and, therefore, what number goes on the balance sheet.
It’s worth noting from this that the discount rate is closely linked to the rate that is earned on assets and so it is closely linked to the performance we expect to see on the portfolio. You should also note that a lower discount rate leads to a higher present value - ie, bigger liabilities in pension terms.
The rate of return...
As mentioned before, the rate of return is intrinsically linked to the discount rate as cash flows are discounted at the rate we expect to earn as a return on the assets. Therefore a portfolio that consistently earns very high returns (through skilled investment, luck etc) can, in theory, discount its liabilities at a higher rate than they would otherwise.
It used to be the case that management were allowed to bake in an assumption of how well they would perform to their discount rate but this led to overly optimistic assessments of performance! Instead, the rules now require you to determine your rate of return purely through reference to high quality corporate bond yields. It is much less open to interpretation but does not always lead to an accurate assessment.
The inflation rate…
This is also closely linked to the discount rate used. The inflation rate can be viewed as an extra return hurdle for the company to overcome and as such should be subtracted from the rate of return before discounting (remember, lower discount rates mean higher present values of liabilities).
So, for example, if a company expected to earn 4% per annum on its portfolio and inflation is expected to be 2%, then it should discount at 2%. This reflects the extra funds the company will need to put away today to meet its liabilities tomorrow, given that the value of the assets will be inflated away over time.
This causes problems (like everything else in this calculation!) because it is impossible to know with certainty the rate of inflation in the future. Current rates are very low indeed and have been for some time, but it has not been so long since we had double digit inflation and it may well happen again. Just check out this chart of the historical rate (RPI) in the UK:
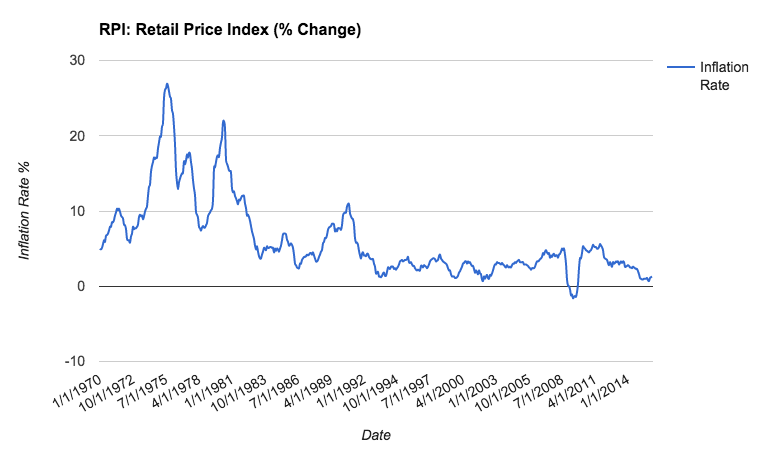
(Data is from the Office for National Statistics)
You can be sure that inflation of anywhere near this scale is not currently factored in to pension plan present value calculations. If, for whatever reason, it did become reality, even in 10 years time, there could be a lot of losses recorded across a lot of companies as they adjusted their calculations for this.
Mortality rates...
This one is fairly easy to get to grips with, it is simply a way of accounting for how long you expect your employees to live for. This is crucial in figuring out how long you will be paying out benefits for.
It is quite a simple equation really - the longer your employees are scheduled to live, the more you will have to pay out in benefits. Easier said than done of course, how long a given person will live for after retirement is quite a tough question to answer. That said, with the use of grimly named mortality tables, actuaries can have a pretty good stab at it. The tables tell you, based on current statistics, what the probability of a person dying at a given age is. You can then weight the benefit due for a given year based on this probability before discounting it.
For example, if a company paid out £20k a year in benefit to a pensioner, and based on the tables they had an 80% chance of living another year, then we would weight their benefit accordingly for that year. In this example, the probability weighted benefit would be £20k * 80% = £16k.
Number of years of service…
As mentioned in the introductory article, annual benefits due to employees will often be based, in part, on the number of years of service for the company. The formula to work this out will often be something like:
Annual Benefit = 2% * Salary at Retirement * Number of Years of Service.
There is therefore a direct linear relationship between how many years employees have worked for a company and how much they receive in retirement benefits.
This relationship is quite simple but for plans that still have active participants, it does raise the usual estimation issues. If someone is 5 or 10 years from retirement, then there is still uncertainty as to what this final figure will actually be. You may be picking up the theme and rule of thumb by now - wherever there is estimation you will find scope for error.
Number of employees…
This, like the number of years of service per employee, will affect the calculation in a simple, linear fashion. Again though, due to it often being a forward looking estimate, it is impossible to know precisely how many people will be due benefits. In reality and at the present however, this is much less of a problem than it used to be. This is because defined benefit schemes are now all (as far as I know) closed to new entrants so companies know with certainty the maximum number of people that will be due benefits.
Where do accounting standards come into the picture then?
Recall from the previous article that we discussed the accuracy of actuaries - and concluded that while not perfect, they can actually hazard remarkably good guesses about these figures when given a free rein. We also discussed the role that accountants play in the process before results are actually published, and how they require a degree of standardisation to prevent fraud and encourage comparability.
Now that we are armed with a bit more knowledge as to how and why changes in certain parameters influence the outcome of our present value calculations, let's take a look at the restrictions the accountants place on them. The relevant accounting standard is the inspiringly named IAS 19 (International Accounting Standard 19) - Employee Benefits (2011). This replaced the old standard from 1998.
As we will see in the next article, by far the biggest influence on the output of a present value calculation is the discount rate used, so let's focus our efforts on understanding what they standard dictates here.
The standards on discount rates...
Regarding discount rates, the standard specifies that a company is “to determine the discount rate by reference to market yields at the end of the reporting period on high quality corporate bonds (or, in countries where there is no deep market in such bonds, government bonds) of a currency and term consistent with the currency and term of the post-employment benefit obligations.”
This figure is clearly variable but at present this equate to around about a 3% discount rate that companies can use to discount their liabilities. This means that, regardless of what the future holds, companies can and will be discounting at this rate. If yields persist at low levels or slip into negative territory, or if inflation rises once again, then given the investment opportunities currently out there, there is every chance that companies will fail to make even these real rates of return over the coming years.
Don’t forget that the inflation rate is also a key component of the discount rate used. Companies use a combination of RPI (retail price index) and CPI (consumer price index) rates to determine the final interest rate assumption. The long term expectations of these rates are derived by looking at the difference between the yields on long run fixed rate and index linked (inflation adjusted) bonds. For the assumption to be accurate then, these long dated reference securities must be priced perfectly. I would argue this is not exactly a common occurrence...unless you believe the efficient market hypothesis of course.
Relating to these two points is the requirement that all actuarial gains and losses must be recognised immediately to the balance sheet outside of the P/L. In other words, any change resulting from the need to use different actuarial figures will be recognised immediately on the balance sheet. You can wake up to an annual report one day and find a big hit to your investment’s balance sheet - and it really can be big if the pension scheme is large relative to the company’s net assets - without any warning in advance.
Even if things work out okay in the long run for these firms, it can spell short to medium term disaster for you as an investor. A further decline in yields or a temporary rise in inflation would result in a large actuarial loss on your investment’s balance sheet. It doesn’t matter that these may be replaced by an actuarial gain a few years down the line, the market is unlikely to react kindly and won’t hesitate to leave you nursing a capital loss.
In conclusion…
In short, we have been through the most basic assumptions to get a qualitative feel for what they are and how they affect the present value of liabilities calculation. To summarise:
- The discount rate - the interest rate we use to work out the present value of our liabilities. This has two key dependencies, the expected rate of return on plan assets and the expected inflation rate.
- Rate of return - how much does the plan expect to earn on its assets? The higher this number, the higher the discount rate and the lower the present value of liabilities.
- Inflation rate - an additional return hurdle for the plan to overcome in order to preserve the real purchasing power of its assets. The higher this is, the lower the discount rate and so the higher the present value of liabilities.
- Mortality rates - how long do we expect employees to live for in retirement? The longer we expect them to live (or the lower the mortality rate), the greater the pension liabilities.
- Number of years of service - how long do we expect employees to have worked at the company by retirement age? The higher the number, the greater the plan liabilities.
- Number of employees - how many people are expected to be beneficiaries of the plan in retirement? The higher the number, the greater the plan liabilities.
- Finally, we saw that accounting standards place quite strict limits on what a company can and can’t use for its discount rate. This is probably better than companies being overly optimistic about their performance potential but does lead to problems in and of itself!
Next time we’re going to embellish on this more qualitative review and work through a simple, fictional example in order to help us really understand and visualise how these assumptions affect the company. Please do chip in with comments or questions below.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
6 comments
Thanks Tom – all good stuff!
Just a couple of comments, as I’m increasingly out of touch with the pensions world:-
It’s worth, if you haven’t already done so, emphasising the distinction between accounting and scheme funding valuations. For a medium/ long term investment horizon arguably it is scheme funding that is the more relevant since it is this, through the deficit recovery plan, that drives the employer’s cash contributions. Selection of discount rate for the funding valuation will be more complex than for the IAS19 valuation – amongst other factors it will reflect actual (and expected) investment strategy and the degree of prudence desired by the trustees and employer (which itself will be a function of the perceived strength of employer covenant). Funding valuations often use differential discount rates for pre- and post-retirement liabilities.
Investment strategy is also a key issue for pension funds. Funds have tended to significantly reduce their equity (especially UK equity) holdings in recent years. Most trustees will be keen to de-risk where this can be achieved without too much strain on the employer. Moving from return-seeking to matching assets (primarily bonds) is a common objective. Some funds engage in ‘dynamic de-risking’ – a buzz word for making incremental switches when equities are relatively highly-valued relative to bonds. According to a Professional Pensions survey in June, there’s a lot of interest in interest rate and inflation hedging strategies. All this will help place the fund in a better position to engage in buy-in/ buy-out transactions with an insurer for significant tranches of liabilities (eg all pensions in payment) when conditions are favourable – for many trustees this is the ultimate de-risking goal. It goes without saying that a fund can’t anticipate equity-style rates of return/discount rates if it doesn’t hold much equities!
There’s a wealth of industry statistics available from the Pensions Regulator and other sources, eg http://www.thepensionsregulator.gov.uk/docs/scheme-funding-appendix-2016.pdf and http://www.thepensionsregulator.gov.uk/docs/scheme-funding-2016.pdf (‘tranche 9’ in this context denotes the most recent batch of triennial scheme funding valuations).
Looking forward to the next instalment in your magnum opus!
Hi all,
Glad you've found the articles helpful - I'll start doing some research for another series on this kind of thing. I actually need to do the last one for this series too...I was planning to apply the discussed ideas to an analysis of BTs balance sheet but things have been busy and I've failed to set aside time to properly research it.
Tom
Good discussion gents - and hopefully at the end of it we can review all of those pension funds listed on the stock market that have miniscule businesses attached to them such as BT, RSA, BAE, RBS etc etc
Tom,
Thank you. You've done a great job with this. I might have to read it several times, which is why I have printed all three articles.
Pensions deficits are indeed a huge issue. But so too might other Off Balance Obligations be to many companies, and I'd like to urge you to do a short and similar series on that please. Auto-retailers and their stock financing, companies with JV obligations, sectors where one should bear in mind that financing structures often involve such commitments. How are they accounted for? Where should investors look for such problems and how should they judge them? We all know gearing can be a great thing for equity returns, but we also know that leverage can cripple very quickly.
Hi,
Thanks a lot for the feedback - to be honest with you I am no pensions expert though I have trained as an auditor in a previous life. So while this is semi(-semi)-familiar territory it is an area that is still a bit of a learning curve for me! As you've picked up, I'm trying to get some of these concepts across in as basic a way as I can in order to help equip private investors with the tools they need to analyse their stocks. That's what we're all about at Stockopedia after all!
You quite rightly say that this an area that a lot of investors shy way away from (I don't blame them personally...) and we've had a number of more experienced community members suggest that we could improve on the way we deal with things like pensions schemes in the StockReports etc. This blog series is the start of my thinking on how to accomplish that and we want the finished thing to be as useful a tool as it can be. If you have any other thoughts on the matter (no matter how pedantic!) then your input will be greatly valued. We are, of course, limited by what can be automated and data driven across the number of stocks that we analyse but a tool or range of metrics that helped to identify when a company could be at risk of a pensions write down would be a great addition to many investors' toolkits.
Re your point on the Projected Unit Credit funding method - I actually was not aware of this at all (I did say I wasn't a pro!) and if I understand your comment correctly it seems it could have quite a significant impact on PV calculations, in particular where the ratio of active to inactive members is high and where the average age of active members is low. This would be because there is potential for many more years of service to be accrued on top of the current level relative to a plan where the ratio of active to inactive members is low and the majority of years of service to be accrued have already been accrued. Does that sound about right? That said, presumably defined benefit schemes with a majority of young, active members are very much the exception rather than the rule these days?
My plans for the next couple of blogs on this series, as mentioned above were first of all to put this article into graphical format with a super simple fictional case study to try and demonstrate how some of these inputs can affect liabilities, then I was planning to follow up with a dig at BT's plan. With the disclosure coming in at around 8 pages in their latest accounts I figure there's got to be enough material for a good blog in there! After that though, that is a good idea you've put forward so I'll do some reading and think on it, definitely sounds to be one for the 'intermediate' course on pensions analysis! If you (or any one else reading) have other ideas for topics you'd like to see covered/think are important then just let me know.
Thanks again for taking the time to comment, much appreciated :), especially coming from an expert in the area like yourself!
Tom
I'm a pensions actuary myself so quite familiar territory. I like seeing this discussed as I think it's something a lot of people struggle to understand, or simply ignore. You've done a really good job of writing this up in a way that a layperson can understand.
One point to note on the comments under Number of years service. Under the Projected Unit Credit funding method used for IAS19 (and for every Scheme Funding valuation I've ever seen), the liabilities at any given date allow for accrued service only, and not the expected number of years service that member's will have at retirement. Where there are active members, then there will typically be an allowance for future salary increases up to the point the member is assumed to leave service (be that retirement or some earlier withdrawal).
Ultimately if people continue in service for longer the liabilities will increase over time, but this isn't allowed for in the liabilities at a specific date (if it did, then you would probably have to allow for the PV of future contributions in respect of accrual in your assets).
Any other comments are purely pedantic! :) Again, well done on this - very good write up. Look forward to future posts.
It's been discussed a bit here before, but I think it's also important to understand the difference between Accounting, Scheme Funding and Buyout bases and what this may mean for the company. E.g. SF basis driving required contributions, potential massive hit if the Scheme was bought out etc. Maybe one for the future!