AO World: high quality and a modest valuation

AO World (LON:AO.) is a business I had been meaning to investigate properly for a while. It's a UK electricals retailer – a household name -- that's just reported record profit and moved into net cash at the year end, yet the shares have drifted down. That combination is usually worth a closer look.
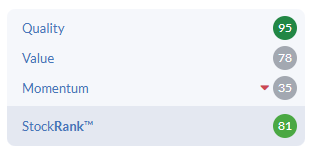
It's also a strong quant stock – a StockRank of 82, with a Quality score of 96 and a Value score of 77. The only thing dragging it down is Momentum at 37, which is precisely what you'd expect from a business that's been de-rated on sentiment rather than on anything it has actually reported.
The Pitch
AO is the UK's most trusted online-only electricals retailer. It sells washing machines, fridges and TVs, delivers and installs them, takes the old one away, and it can sell you a phone contract and a refurbished iPhone as well. It owns musicMagpie, the "recommerce" business, and – as of last week – Jessops, the camera chain.
The investment thesis is combination of valuation and quality, and an anticipation that momentum will turn around.
The shares trade on 12.1x forward earnings, 5.7x free cash flow and 6.2x EV/EBITDA, with net cash and a return on capital of 21%. That's a modest retailer multiple on a business that grew profit 16% last year and is guiding to 20%-plus for the first half of this one.
Management has a stated target of a 5% pre-tax margin, against roughly 4% delivered in FY26. On £1.27 billion of revenue that's about £63 million of profit versus £50.5 million reported. That's the bull case in one number.
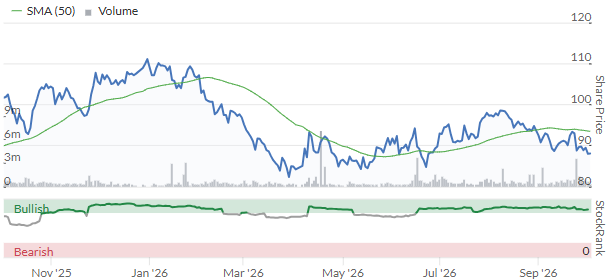
[Chart: AO World 1y share price. Source: Stockopedia]
The Big Picture
The UK consumer isn't in great shape. AO recently said the backdrop was “sluggish” – it’s hard to disagree.
But the business keeps growing – pre-tax profit is expected to be up more than 20% in the first half – and the shares have gone the other way. Institutional analysts have the consensus target at 139p, some 55% above the current position – the market is pricing weak consumers, but analysts see a stronger business.
Part of the reason it holds up is the resilience of the core business. When your washing machine dies you buy a washing machine, regardless of what the economy's doing. AO actually has built a membership scheme around that – members always pay less, and it gave away £29 million of discounts to them in the half.
The business reported that renewals, spend per member and share of wallet all went up last year. It added 720,000 new customers and its share of the big-appliance market went past 17%.
Trust matters and peers can’t build it overnight. AO has a million Trustpilot reviews at 4.9 out of 5 – the first retailer anywhere to get that. Founder and CEO John Roberts said in June that it “sits nowhere on our balance sheet, yet it's among the most valuable things we own”. What’s more, in a business where the product is identical everywhere, the delivery is a large part of the experience.
It's worth noting that some of the discount may reflect previous exuberance – the business overstretched itself. It listed in 2014 to fund European expansion and spent the next eight years doing exactly that – first Germany, then the Netherlands, a £50m placing in 2017 to fund more growth, a mobile business bought for £32.5m in 2018, then housebuilders, Tesco concessions and an arena sponsorship.
The pandemic made these investments look wise, before they fell apart. Roberts, who came back as chief executive in 2019 and was responsible for some of the later bets himself, shut Germany in 2022, binned the side projects, charged for delivery and cut costs. Since then it has guided low and delivered – that’s frustrating in the short term and reassuring in the long. The two deals since – musicMagpie, profitable in fifteen months, and Jessops, small and paid for in cash – don't look like the old AO.
Collectively, this has contributed to a turnaround in quality metrics. In September 2022, the company’s QualityRank sat at 17. Today that figure is 95, and this reflects ROE of 22%, ROCE of 21%, an F-Score of 7 out of 9 and a Z-score in the safe zone.
It’s worth knowing where the ROE comes from. While the operating margin is under 4%, the business turns its assets over 2.6 times a year and runs on very little equity. It doesn’t have any stores, it leases warehouses, customers pay up front and suppliers get paid on 49-day terms on the company’s measure. It's a capital-light model, not a fat-margin one.
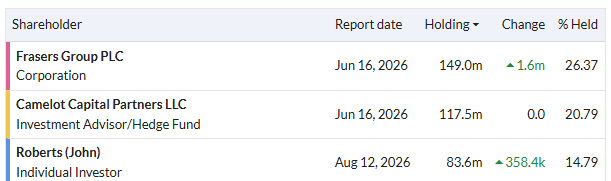
Roberts owns 14.6%. Frasers Group owns 26% and has been buying since 2023.
Going Deeper
FY26 revenue rose 11.4% to £1.27 billion and adjusted pre-tax profit jumped 16.1% to a record £50.5 million. Free cash flow was £66.4 million against £26.3 million the year before, and the group ended the year with £16.4 million of net funds having started it with £35.9 million of net debt.
Then last week's pre-close update: H1 revenue up 5.5%, pre-tax profit up more than 20% to around £21.5 million, and more than £200 million of liquidity headroom after paying a £10 million special dividend and completing half of a £10 million buyback.
- Strong and steady: Group revenue growth of 11.4% includes a full year of musicMagpie. Strip that out and B2C retail – the bit that matters – still grew 9.5% to £911 million, with market share gains across every major category.
- Two divisions shrank but it was anticipated. B2B revenue fell 12% and Mobile fell 18%, both deliberate resets toward profit rather than volume. The post-pay mobile business is now profitable, with improved terms agreed in principle with the networks, and management says the B2B reset is “materially completed”.
- A 5% margin target looks achievable. Gross margin rose 70bps to 25% last year, Mobile and musicMagpie are now profitable, offshoring has been completed and B2B has been reset. There's no date on it – management says “medium-term” – but Roberts described it as “our next milestone” in September. A stronger margin will inevitably make this business more attractive.
- musicMagpie – a small electronics recommerce business -- has turned. A little over fifteen months after acquisition it has gone from a c.£6 million loss to run-rate profitable, helped by exiting the US, consolidating warehouses and a trade-in partnership across more than 1,300 Timpson stores.
- Jessops is a bolt-on. Bought from BBC dragon Peter Jones and funded from existing cash, it brings a specialist category and a recommerce arm, Camera Jungle, that sits alongside musicMagpie. AO expects it to grow over the next twelve months on the back of AO's scale and traffic.
- AO Mobile is one to watch. The group's own-brand mobile network (capacity from Vodafone) launched on 12 August at 500GB for £12 a month (for members), which Jefferies' Andrew Wade reckons undercuts every major UK operator. With Switch24, members can get an iPhone 17 from £17 a month -- upgraded every two years – meaning the handset, contract, and trade-in can all be done on one platform.
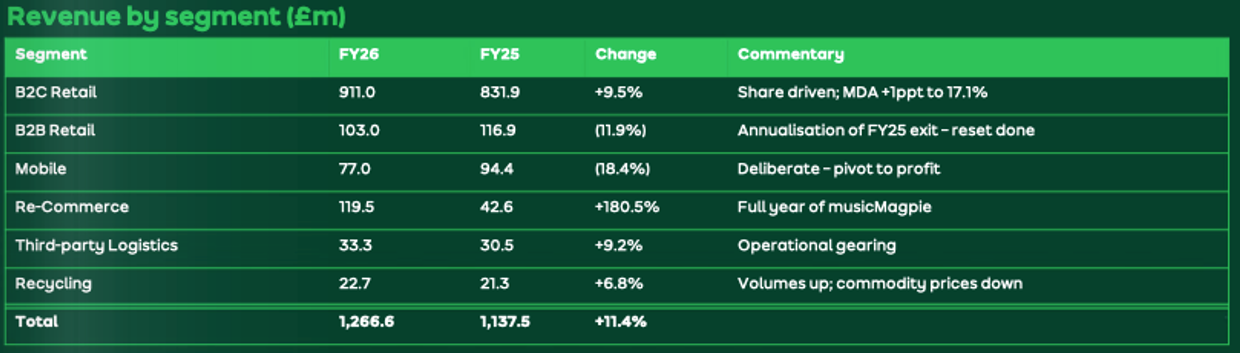
[Table: FY26 revenue by segment. Source: AO World FY26 Results]
Valuation
- 12.1x forward earnings, PEG of 1.0. Forecast EPS growth is 13.4%. Earnings for FY28 are pencilled in at 7.9p, which puts the shares on 11.3x two years out. Unlike other stocks I’ve covered recently, there are no significant adjusting items – the company notes there were “no adjustments to statutory profit before tax in FY26,” so adjusted and reported are the same number.
- 5.7x free cash flow. Cheap against the market, and mid-pack for a specialty retailer – 10th of 27 on Stockopedia's ranking. What's changed is the direction: FCF went from £26m to £66m in a year and the balance sheet flipped to net cash, with net gearing of -9.4% and interest cover of 29x.
- £20 million is going back to shareholders this year: a £10 million special dividend paid in July and a £10 million buyback, half done. On a £507 million market cap that's a 4% return.
What the brokers say
Four analysts cover the stock with a consensus target of 139p, 55% above the current price – pushing the ticker towards ‘strong buy’. Jefferies trimmed its target from 160p to 155p last week but kept its Buy, calling the pre-close “a solid result” and continuing to view AO as “a winning proposition with a long-term growth runway.”
Estimates have drifted down slightly in recent months – 0.1p off FY27 EPS over one and three months – which reflects Jefferies cutting its core consumer growth assumption from 6.5% to 4.5% and FY27 pre-tax profit by 3% to £53.5 million.
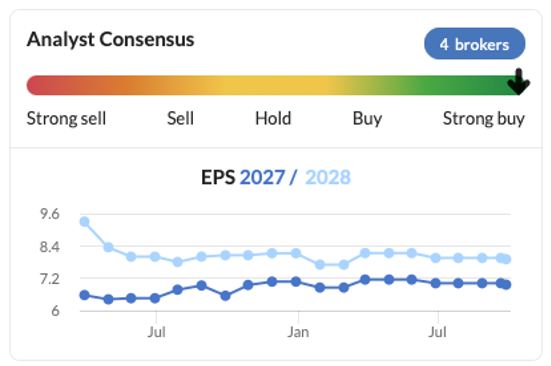
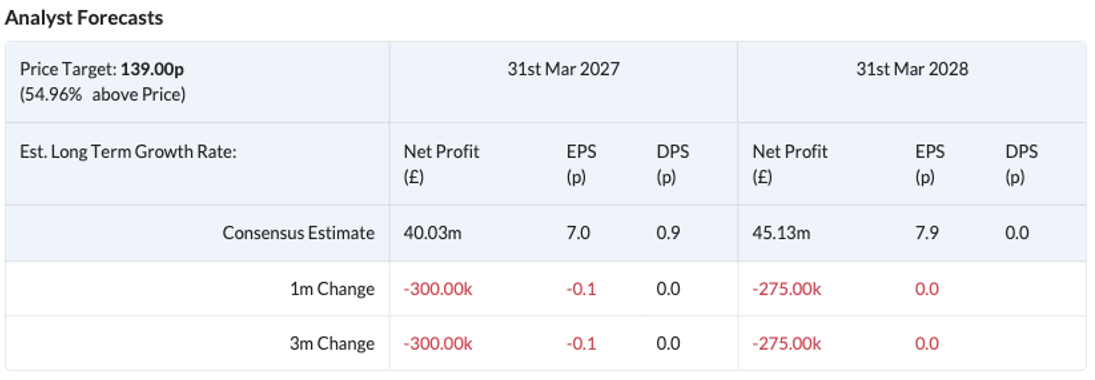
[Chart: Analyst consensus / EPS 2027-2028 estimates. Source: Stockopedia]
The Bear Case
So why does a business with record profits and net cash sit on 12x?
- Management didn’t upgrade. June's results guided FY27 profit “in line with current market expectations” and the shares fell 3%. September's pre-close pointed to 20% profit growth and held guidance again; the shares fell 4%. Consensus has FY27 pre-tax profit at £53.5 million, up just 6%, so 20% growth in the first half implies a broadly flat second half. Management highlighted higher ERP and warehouse-system spend this year, and tougher second-half comparatives, but the market wants to see it, and until it does the shares are stuck.
- The summer may have been softer than it looked. Wade suspects the retail arm ran below the 5.5% group growth rate, hit by a hot World Cup summer that stretched delivery crews and pushed spend toward fans, air-con and TVs, where AO is under-represented.
- Margins are thin. Four pence in the pound of pre-tax profit doesn't leave much room. If sales slip or delivery costs rise, profit moves a lot more than revenue does -- that's what happened in 2022. Fuel and electricity are hedged into 2027 (fuel is 80% hedged to March 2027 and electricity is fixed to October 2027), which helps, but a soft Christmas would still show up quickly.
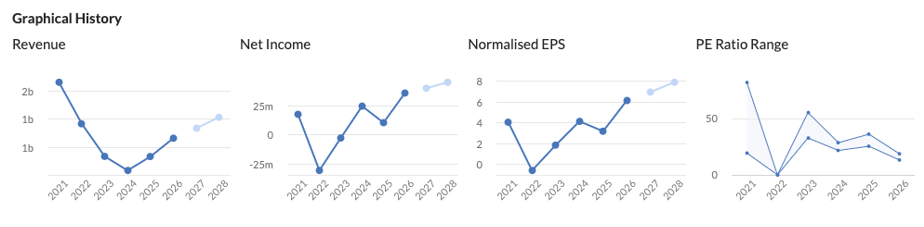
[Chart: PE Ratio Range. Source: Stockopedia]
The Bottom Line
AO World is a high-quality, cash-generative retailer on a modest multiple. It has net cash (at end of year), a 21% return on capital, a credible path from 4% to 5% margins, and is returning £20 million this year to shareholders while it waits for the market to notice.
The interim results on 24 November are due just before peak trading (e.g. Black Friday and Christmas). Following two “in line” prints in a row, that's the most obvious window for the upgrade the market has been asking for.
However, I don't think an upgrade is needed to make money here. The valuation is undemanding, growth is steady, quality metrics are strong, and the business looks well run today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
4 comments
My thoughts on this share is even tho it appears a very good share on a lot of grounds itemised by Dr fox why was its Ceo selling huge amounts of shares circa 7.5 million shares at 90 p in April 2026 and further 1.7 million shares at 107 pence in Jan 2026 and 2.5 million shares at 105 p in Jan 2026 .Further large quantity selling by the CEO occurred in 2025. It hardly inspires confidence I n the ordinary punter
I totally appreciate that. I do, however, try not to read too much into it. We all have to liquidate investments for some reasons at different times.
Great article James! The membership scheme here is definitely interesting – they are operating a 'scale economies shared' business model like Amazon and Costco.
Thanks, Ed! Really appreciate that. Absolutely -- the Nick Sleep reference really works here.