Are Carillion PLC shares a good investment?

Sometimes when I’m scouring the markets in search of a good place to put my money I’ll get a sense of déjà vu, a kind of, “hang on, I’ve been here before” moment. That’s exactly what I get when I look at the shares of Carillion PLC, the leading support services company.
Why should I get that déjà vu feeling? It’s because Carillion (LON:CLLN) looks uncannily like Interserve did when I bought it back in early 2011. To date my investment in Interserve has returned 114.5%, so finding another investment like that is obviously high on my list of priorities.
Carillion – An overview
The company operates in the Support Services sector which means it provides maintenance and facilities management for a wide variety of buildings, as well as financing, designing and building both property and infrastructure (including Public Private Partnership projects).
It’s valued at just over £1 billion, is listed on the FTSE 250 and generates about 75% of revenues from the UK (with the remainder coming from Canada and the Middle East and North Africa).
Past performance
Starting with the past, here’s a chart showing how Carillion has done in recent years on a per-share basis.
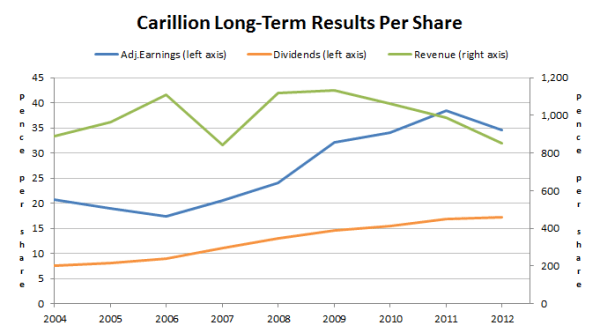
There are two conflicting stories in this chart. The first is the relative stagnation in revenues, while the second is the near doubling of earnings and dividends.
If a company can double its earnings and dividends then of course that’s good, but there are limits to what can be done if revenues are not growing. After all, margins can only be expanded so far.
Why have revenues failed to grow for the best part of a decade? The financial crisis certainly doesn’t help. The UK construction industry is apparently still shrinking and as Carillion gets around 75% of revenues from the UK, that’s the main reason. However, the management have a plan to grow internationally, and personally I’m always more comfortable when a company has an international footprint.
The plan is to grow the Canadian and Middle East businesses to around £1 billion in revenues by 2015. That would leave the company with a more diverse revenue split, with around 60% coming from the UK and 40% from overseas.
From where things are today that will require a near doubling of revenues from overseas, so whether or not this goal is actually achieved is uncertain, but accepting uncertainty about the future is a key part of being a successful equity investor.
By combining the growth rate in sales, earnings and dividends we can estimate the overall per-share growth rate at 7.7% over the last decade, and that growth has been slightly more consistent than the growth of earnings and dividends in the overall UK market.
In other words, Carillion has had faster, more consistent growth that the market, which in my books makes it a good investment candidate.
The present situation
I have three main requirements when it comes to the present:
- The company is not in the middle of some major crisis which may have significant long-term impacts.
- Debt levels aren’t high enough to put the company’s future at risk
- The share price is low relative to the company’s proven earnings and dividend paying ability.
On the crisis front, there doesn’t seem to be one. There is the UK issue, where revenues are shrinking due to the shrinking UK construction sector, but this is a known issue and has been actively managed since 2010; although, as I said before, whether shrinking UK revenues can be fully mitigated is another matter.
Debt levels are quite high at around £800 million, but the company carries large amounts of cash on the balance sheet (close to £650 million) offsetting the debts to some degree. Interest cover is a reasonable 11.
And then there’s the pension. With current defined benefit obligations of £2,343 million, the company has massive pension liabilities. The current funding gap is £270 million and deficit recovery payments are around £30 million a year. That’s from a company where profits are under £200 million a year.
For me these pension obligations are likely to be too much as I have strict rules that limit borrowings and pension liabilities. That’s a shame because otherwise Carillion was looking good.
Still, not everybody has the same rules as I do and so perhaps you can live with the company’s pension as it is. It certainly isn’t a sure thing that the pension will cause problems or dividend cuts in the future, so let’s turn our attention from the company to its shares.
Value for money?
The current share price is 262p as I type. At that price the PE is 7.5, the PE10 (price to 10 year average earnings ratio, which helps to smooth out the yearly ups and downs in earnings) is 9.8 and the dividend yield is 6.6%.
All of those compare very favourably with the market average as measured by the FTSE 100. That index at yesterday’s close of 6,165 can only manage a PE of 12.4, a PE10 of 13.4 and a dividend yield of 3.7%.
For me the most striking difference is the dividend yield. When I bought Interserve at 246p its dividend yield was 7.3%. At the time I couldn’t see any rational reason why a company with reasonable prospects should have a 7.3% yield. However, over the years I have come to realise that the market is sometimes far from rational.
I put most of Interserve’s gains down to the dividend. At 246p the yield was 7.3%, and as it became clear that the dividend was still growing, investors bid up the shares until they reached around 500p, giving a current yield of 4.1%. Investors chasing the yield down have driven capital gains of 100% in just 2 years.
What will the future bring for Carillion?
Sadly, I have no crystal ball. Can it overcome the ball and chain which is its pension obligations? I do not know.
If Carillion can follow Interserve and maintain and indeed grow its dividend, then at some point it seems likely that investor sentiment will change, just as it did for Interserve. At that point the shares could increase massively from their current levels in a relatively short period of time.
Only time will tell.
Disclaimer: I still own shares in Interserve.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
2 comments
Not wrong at all.
He said he could not buy it because of the Pension, the Debt & his Rules but others might not be so strict.
Those who took the risk could have sold for 390p, a 48% profit, in March 2014 and not far off that for another year.
In retrospect he pointed out the risks and rewards accurately.
Oh dear. This was so very very wrong. An update: terrible management destroyed value in a massive car crash.