Are Rolls-Royce shares set to roll over?

Everything seems to be going so well for Rolls-Royce (LON:RR.) So well in fact that, as you may have seen, the company recently had a royal visit to a factory in Singapore where another exceptional engine was unveiled to the world. However, although Rolls-Royce have done exceedingly well in the last decade, Rolls-Royce shares have done even better.
In the last decade, turnover has gone from £5.8 billion to £11.1 billion; profits have gone from around £200 million to over the £1 billion mark, and dividends have gone from 8p per share to more than 17p. Overall the company’s growth rate has been upwards of 10% a year, an exceptional figure for a FTSE 100 listed company whose market value is more than £15 billion.
You can see the results of this outstanding decade below:
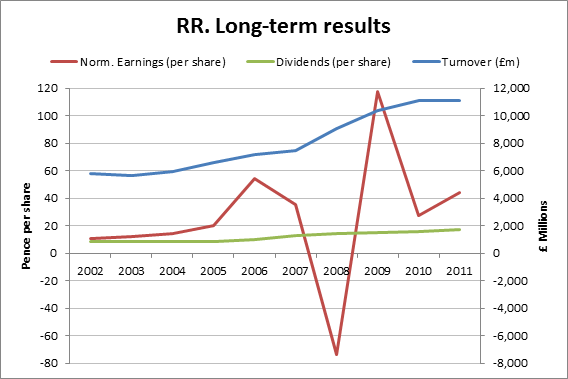
You’ll have to ignore the manic earnings swing of 2008/9, which was currency related and didn’t show up in the adjusted, underlying EPS figures. The turnover and dividends show the underlying picture of steady growth much better.
In the last decade the company has roughly doubled its ability to generate sales, profits and cash dividends for investors; but that is literally nothing when compared to the returns from Rolls-Royce shares.
Unbelievable shareholder gains
In 2002 you could have picked them up for less than 200p each. If you were a really serious bargain hunter then you may have loaded up with Rolls-Royce shares at the incredible price of 69p in March 2003.
Since then the shares have risen to more than 800p, almost touching 900p a few weeks ago. That’s a gain of more than 300% in the last decade, even without taking dividend income into account.
If you had bought the shares for less than 80p at almost any time during March 2003, and then sold at more than 800p at any time since March this year, then you would have found the mystical “10-bagger”, and generated over 900% profit in only 9 years.
The more they rise, the further they have to fall?
I wrote about the bubble in defensive stocks recently, and I think that Rolls-Royce shares may be a prime example of this particular bubble.
The underlying company is definitely defensive. It’s large, global, robust, diversified and carries little debt. It’s a great global success story with a consistent ability to grow year after year.
So don’t be in any doubt – I think that Rolls-Royce is a great defensive company and one that I would be happy to invest in at the right price. But are Rolls-Royce shares worth more than 800 pence each?
At today’s price of 830p, each share has a dividend yield of just 2.1%. I can get 3.7% (a 76% improvement in income) from the safety of a FTSE 100 index tracker. The current normalised PE is 18.8, also well above the market’s PE of 11.4.
Looking at the ‘cyclically adjusted’ PE using average earnings over a 10 year business ‘cycle’, I can see another indicator of an overvalued share. Rolls-Royce shares are priced at around 30 times their cyclically adjusted earnings, while the FTSE 100 is less than half that at under 15 times.
Of course, if Rolls-Royce continues to grow while steadily increasing its dividend, and if investors continue to give the company a lofty valuation, then the shares may still do well in the future.
But let’s look at it another way. The last time the FTSE 100 was valued as highly as Rolls-Royce is today (at 30 times its cyclically adjusted earnings) was 1999. Investors had invested in a great asset, namely the UK equity market. It had grown earnings and dividends consistently well for years and the FTSE 100 had gone from around 2,000 in 1990 to almost 7,000 in 1999.
In essence, the price of the market had risen far faster than its underlying value.
So what happened next? The value of the market collapsed by about 50% and we are still not above 7,000 today, more than 12 years later.
I’m not saying that this fate awaits Rolls-Royce shareholders. But let’s say the shares fell by 50% tomorrow, back to just over 400p. Just imagine that some bad news came out that was bad enough to trigger such a fall, and yet not really affect the long-term prospects of the company (although the market would think otherwise, extrapolating today’s bad news further into the future than it really deserves).
At 400p, what would we have?
We’d have a big, international, relatively defensive company that can consistently grow at around 10% a year. It would have a yield of perhaps 4.2%, a PE of around 9.4 and a cyclically adjusted PE of about 15.
Surely investors wouldn’t allow such a fantastic business to trade at such a low PE, with such an attractive yield?
Well, let’s look at Tesco (LON:TSCO) . It’s a big, international, relatively defensive company with a history of consistently growing at more than 10% a year. It has a yield of 4.3%, a PE of 10.5 and a cyclically adjusted PE of 14.5. Almost exactly the same as Rolls-Royce shares would have if the price fell to 400p today.
The bad news for Rolls-Royce shareholders is that Tesco really is that cheap, and there’s no fundamental reason why Rolls-Royce shares can’t fall back to 400p either.
That may sound crazy, but it’s where they were just three short years ago, and they could easily go back there in the next three years.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
8 comments
How does RR compare with their users ie Airbus/ Boeing in terms of deep pockets
This is a great post, from a 2015 perspective. Spot on.
Good article and I agree that it would be risky to invest in Rolls at the current price, despite its excellent track record. However, I question the applicability of CAPE in situations like this.
The whole point about CAPE is that it is designed to even out cyclical swings. However, whilst Rolls has been subject to cyclical swings over the last 10 year period, it has also achieved considerable secular earnings growth. Hence I don't see how a metric that averages earnings over the last 10 years is particualrly useful in a situation like this. Future earnings are not likely to revert to the figure of 10 years ago and I see no reason to believe that Rolls relative earnings outperformance over the last decade is going to turn into underperformance in the next one (i.e. mean reversion).
So, personally, I wouldn't be guided by CAPE here but I do feel that a historic P/E of over 18 is a bit rich. In that vein I'll just note that the graph shown on Stockopedia's stock report for RR (in the "Graphical History" section) which shows how the company's P/E has varied over the last 5 years is IMO more useful and shows that the P/E that the stock is currently on is towards the upper end of its historical range, implying "expensive".
I think CAPE is a valid tool for valuing any company, regardless of whether it's cyclical or not. The price relative to the past 10 year's earnings can give you an idea of what you'd be paying relative to the next 10 years earnings.
So a company that is non-cyclical, say Reckitt Benckiser, will normally have a relatively high CAPE because the next decade's earnings are virtually certain to be materially higher than the previous decade's. An above average CAPE in this case isn't necessarily a bad thing, although even non-cyclical business can have a CAPE which is 'too high'.
A company like M&S, which is somewhat cyclical, should probably have a lower CAPE than RB, and usually does because investors are less certain that the next decade will be substantially better than the last.
With Rolls Royce on a CAPE of 30, investors are assuming that the next decade's earning are going to be very much higher than the last decades. This may be true, but then again it may not. They are taking a substantial bet on a rosy future which is an investment strategy that does not have a good track record.
I would say that CAPE, like any quantitative metric, should not be used in isolation. It should be used only in conjunction with considerations about a company's cyclical nature and potential growth rate.
As for PE, yes that's a good tool, but only as long as you look at multiple years (as you say) and not just the last year - in case last year's earnings were especially high or low which of course distorts the PE.
Interesting from Stuart Mitchell Capital on Rolls...
But also this comment...
More here: http://swmitchellcapital.com/news/august-1-2012
Hi Ed, well I wish them good luck with Rolls, but I'd expect a much better entry point at some future date. As for Europe (I guess they mean continental), I agree, valuations are compelling, which is why I'm surprised they chose Rolls rather than a European 'world leader'. I'll wager 50p that Rolls Royce's CAPE is lower 5 years from now than it is today.
Hi Siestainvestor, thanks for pointing that out. I didn't pick the image but I'll ask the Stockopedia editor if it can be changed to an aeroplane engine, or logo or something appropriate (even though it's a nice shot of a Phantom).
Can't fault the thinking in this article. But the Editor ought to know that Rolls Royce motor cars (as photographed) are part of BMW and nothing to do with RR. the quoted company