ATA: An emerging IT services story

A stock that has recently appeared on my radar is Atturra (ASX:ATA).
Atturra is a technology company that provides end-to-end technology services. They offer services such as advisory and consulting, business applications, cloud services, data and integration, and managed services. They serve over 600 clients across public and private sectors, including industries like defence, government, financial services, education, local government, manufacturing, and utilities. Atturra partners with leading technology companies to deliver scalable and expert solutions. The company is based in Sydney, Australia though they have a presence in all the major business centres as well as New Zealand and Singapore.
The immediate question that popped up into my mind is could this be another TechnologyOne (ASX:TNE) in the making, and while it is early days there are some promising signs. Coincidentally, Atturra is the largest independent provider of services supporting TechnologyOne applications. Along with Microsoft, these partnerships form a strong base from which to market their services.
While I say the stock came up on my radar recently, the reality is it has had a sound overall rank score since one was calculable following its listing at the end of 2021. The company is an amalgamation of a range of roll-ups and in 2021 changed its name from FTS Group to Atturra. In 2022 it acquired previously listed and distressed MOQ for some $22M after a brief bidding war with Brennan IT.
The bolting on of acquisitions continues to be a resonant theme for Atturra as it has been making a number of them in recent times to add onto their capability set.
Most recently the company had been championing the acquisition of three businesses to support a capital raising that they performed in 2022 (just one year after listing.) The Somerville Group was most recent with their provision of managed services to the corporate and education sectors. Prior was Hammond Street Developments, a specialist Microsoft partner. The third was intended to be a company by the name of NBIO, however that will now not proceed.
Stock Rank
The half year result recently published by the business was a good one and contributed to the strength of StockRank that the company has experienced since May 2022 when the score first rose above 80. Since then there has been a steady improvement underpinned by a high Quality and Momentum score.

The company ranks very well from a quality perspective because all the key metrics rank highly, which is often the case for profitable IT companies as they are low capital intensive businesses that are able to generate solid returns on capital.
Further the operating margin ranks highly both on a market and industry level. This is important as wages are the biggest expense for an IT business. So a robust operating margin generally translates well into cash flows. Especially with a low Earnings Manipulation score, meaning this is a good sign.

Value is always going to be a challenge after a price has performed so well and the company has a large intangible asset base relative to their total assets. But this is a common theme with the likes of TNE, Objective (ASX:OCL) and other high intangible businesses. The fact is that when it comes to these types of businesses, traditional value metrics can be a little lagging, therefore a Value score of 63 for Atturra is actually quite good. Especially when you look at more established players.
As alluded to, Momentum has been quite strong. From a price performance basis it has outperformed the market on all the periods measured, though it is important to note that the company has lost a little puff since its highs in February. While it is not alone, in exhibiting a chart pattern like this, for proponents of charts they will notice that I wrote about ATA in a Momentum Monday article in April.
At the time I said from a price perspective support is the low close of March at $0.815. A break below that level would be the stop loss at current levels. Therefore a position close to support which price is starting to move towards is why it is on my radar as ”I won’t have to wait long to know if I am wrong.”

As also mentioned, investors will note that the daily bars for ATA can seem quite large with large volume spikes. This is symptomatic of a stock not heavily traded (low average volume) with quite large spreads in price. Traders need to consider this when looking to establish a position, as getting in and out at a fair price will be difficult if sentiment shifts one way or another. Further the 50 and 200 day moving
But this is obviously not as big an issue from an investment perspective, which is the lens we look at ATA today. What is also just as pertinent is how analysts see the stock. And following the EPS downgrade cycle which came on the back of rising rates and growing expense pressures on many companies. The trajectory of the line changed following the update in April. The servicing of governments and large corporations offers an element of stability to earnings in these uncertain times.

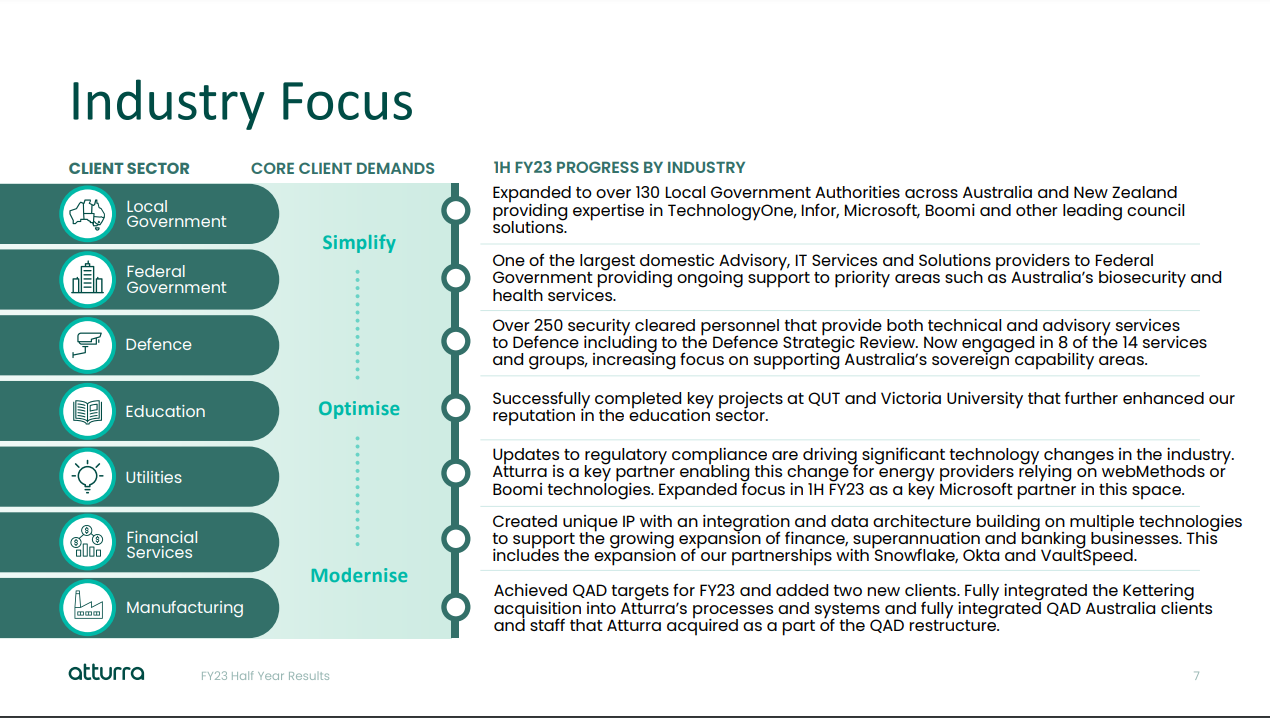
Source: ATA Half year report presentation
The company hasn’t paid a dividend yet, though analysts expect to see it start next year, albeit small. While this makes sense at the moment given so much cash is re-invested into the business through acquisitions, in time my experience is with such IT businesses is they will end up paying big dividends in the future "should" they execute their strategy correctly. Investors would be best to be mindful of that.
Outlook
Which takes us to the outlook of the company, and at the same time as finalising the Somerville Group acquisition, Atturra raised its FY23 revenue guidance to be in the range of $168.5m-$175.5m, up from the previously communicated $160m-$167m.
The FY23 earnings before interest and tax (EBIT) is expected to be in the range of $15.5m-$16.5m, up from the previously communicated $15m-$16m. Atturra is also forecasting an Underlying EBITDA in excess of $19m for FY23.
Another possible tailwind upcoming is Atturra’s intention to start reporting on ARR for FY24.
ARR, or Annual Recurring Revenue, is a preferred earnings measure, especially for companies with a subscription-based business model. Investors tend to prefer ARR as a measure because it provides a clear understanding of a company's earning potential and growth trajectory. It also allows us to compare the performance of different companies in the same industry.
So in summary, the outlook for Atturra is positive with expectations of increased revenue and earnings following recent acquisitions. Not a bad outcome should they achieve it within a period of corporate cost cutting.
Tight registry
Chairman Shan Kanji owns a significant stake in the business (circa 50%) with CEO Stephen Kowal owning 3%. The other thing I find interesting is that there are no major investment houses on the books; this could be a future tailwind if a deep pocketed investor wants in. Though this will likely have to see Mr Kanji sell down a portion of his holding. Though I note with interest a small high conviction fund took a 5% ownership in the company on 1st June. The more eyes they can get on them from the money managers the better.

At the moment though it should be noted though, that liquidity is an issue with so much held by one person. As a result investors need to be wary of taking too heavy a position in a stock that trades on average just a tick over $50,000 per day.
But looking through with a positive lens, ATA is much closer to the start of its corporate journey than the end, therefore should it continue to meet its objectives and still grow, this dynamic in time will no doubt change and it may result in the stock melting up as investors can sit on the sidelines no more and need to get in.
Further, a significant amount of the registry is also made up of the founders of the divisions they acquired. Hopefully the company will be able to continue to leverage off their skill base as they grow the business and deepen its penetration.
Conclusion
I started this article by asking could ATA be another TNE, and while it has someway before it becomes a $5B behemoth, at this early stage it seems to be making all the right steps.
It is acquiring strategic capabilities and embedding them into a process that services some big names, including TNE itself. However such tightly held entities in the IT space often can be left unfulfilled as some investors see such companies as personal play things rather than investing vehicles (eg DWS which for years was shunned despite growth and strong dividends. Ultimately it was acquired in 2020.)
However, all a company can do is perform, and the market will do what it does. And for those looking for a way to play this space without paying nose bleed valuations though with a little less liquidity, then ATA is a possible candidate heading in the right direction.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?