AUB - A broker taking the clip on a bigger ticket
I often like covering stocks that I analysed as a junior in order to monitor how they look right now. One that consistently has kicked goals on its growth trajectory is AUB (ASX:AUB)

I remember covering AUB when it was known as Austwide Brokers. Just to show you how old I am (and how long I have been doing this stuff) I can remember OAMPS and the like and number of what it calls “transformative acquisitions” to get to where it is today. But this is not a case of me reminiscing about the good (or bad) old days. Rather we are going to look at AUB with our modern lens.
Today as AUB it is a $3.7B Mkt Cap stock, it’s in the ASX200 and it’s a leader in its target market.
It operates a network of retail and wholesale insurance brokers and underwriting agencies. It works through a network of approximately 595 locations globally, employing over 5,500 team members who manage over AUD 10 billion in insurance premiums on behalf of around one million clients (which includes me as owner of an AFSL). The group’s services (according to the company) include:
Australian Broking: Provides insurance broking and advisory services primarily to small and medium enterprises (SMEs) in Australia, covering insurance policy placement, member services, life insurance broking, premium funding, and claims management.
New Zealand Broking: Offers similar insurance broking and advisory services to SMEs in New Zealand, with equity stakes in several major broker partners.
Agencies: Operates underwriting agencies that manage insurance products on behalf of licensed insurers, specializing in general commercial, strata, and specialty insurance.
International (Tysers): It purchased this in 2022. Tysers is a wholesale and retail broking and managing general agent (MGA).It primarily operates through the Tysers platform headquartered in London, with a significant presence in the Lloyd’s market.
Support Services: Provides technology platforms like BizCover, automated quoting, and other support services for brokers within and outside of AUB’s network.
AUB Group operates across multiple segments, including broking, underwriting agencies, and insurtech, which allows it to generate income from various sources, reducing dependency on premium-based income alone. Eg like an IAG or other insurer.
While “roll-ups” can be a dirty word when it comes to investing given some high profile failures, in the case of AUB it has been a boon as it has boosted the scale and capability of the organisation, as well as in the case of Tysers, has opened new growth opportunities globally.
Quality
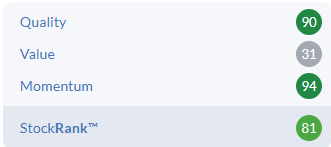
Despite the number of acquisitions it has made. AUB ranks as a 90 from a Quality perspective meaning we can somewhat believe the rhetoric sounding the good integration of existing businesses. Particularly as many of their distribution networks are owner/founder lead.
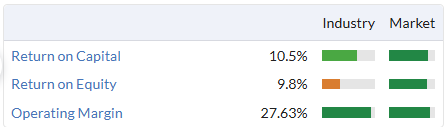
When it comes to assessing this business though relative to peers it makes it a little more difficult as it can be bundled with a lot of premium writers, when in fact its numbers can be more assed like an Industrial style business.
Therefore looking at the Return on Capital and Return On Equity may not be outstanding, however they have been consistently good over time. In fact their operating margin of 27.63% is exceptional given the product they sell if often recession proof (ie I need insurance irrespective if it rains)
As discussed in this forum before, I also like to see a business that is expected to see continued growth in sales and ideally profitability (should the margins be juicy enough). In the case of AUB we see that clearly a trend has been established and if analysts are correct, is expected to continue moving forward.


Investors who keenly watch for such things can see that EPS Growth in the latest year was very strong. However, prior to that it was mixed. This was mainly on account of new shares issue to support recent acquisitions and has seen the number of shares on issue grow by 9% CAGR over the last five years.

Investors will be hoping that organic growth can now support the growth moving forward with early indications looking very pleasing.
It still sees further consolidation within the industry as possible, and following the recent capital raise it did in FY24, according to the firm it has approximately $470M of cash and debt funding to support future growth. (More under outlook.)
Value
This is where the stock is most challenged given that overall it rates a 31. However, given all the good things I have said to date on this company, there is a reason why you have to pay to play with this stock.
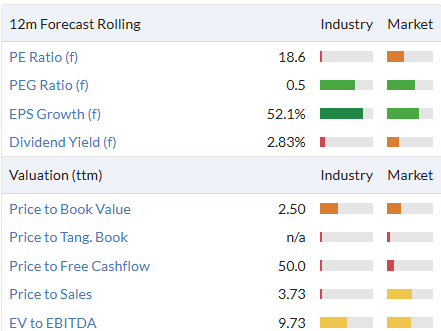
But for a company like this a forecast P/E of 18.6 and EV/EBITDA of 9.73 is by no means extreme.
Further its history of increasing dividends paid to investors is also reassuring. Particularly as they say that shareholder returns overall are important to them. It also helps make the current forecast dividend yield of 2.83% more palatable.

Momentum
This is the company's strongest overall score at 94. That is evidenced by the green circles that sit near both its relative measures and the price trend which sees the stock trade near all time highs despite the pullback we have witnessed since August.
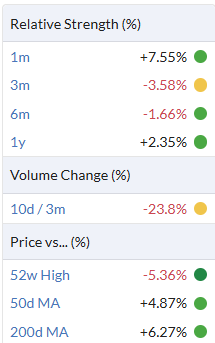
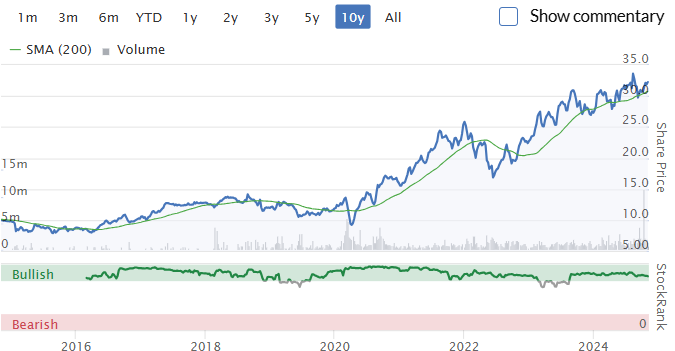
Analysts have also been steadily increasing their EPS targets on the business on the back of each positive announcement from the business. Its ability to maintain this trend will be essential in sustaining what would appear on the surface to be a lower Value score.

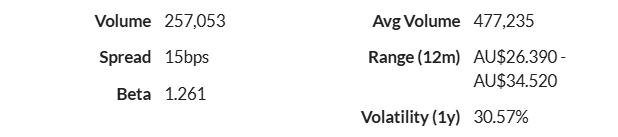
Perhaps interesting for some is that AUB has a current beta of 1.261 which means the stock is relatively volatile. Ie when markets go up it does better, when the market goes down it does worse. Of course this can change over time, but it is interesting to see at the minute.
Leadership
As discussed previously, following the wide range of roll ups and acquisitions made by AUB over the journey the share registry is a hotch-poch of different holders.

That said, despite access to a significant number of shares, it is interesting to see that the stock doesn’t overly trade on a daily basis. In my view this is a good sign that not many people may not want to sell the business, and therefore it has a loyal shareholder base.
Outlook
The company traditionally can be rather coy when it comes to their expectations of the future. Obviously as previously discussed I feel the continued expansion overseas through the Tysers and Pacific Indemnity deals (it owns 70% of the latter and acquired that in July 2024) are going to be key to the success of AUB moving forward. It did provide a profit guidance of AUD 190 million to AUD 200 million, which according to the company represents an anticipated growth of 11.1% to 16.9% compared to FY24.

Source: AUB AGM Presentation 2024
According to the annual report and a recent presentation from the business it is focused on growing the UK Tysers retail business , leveraging Tysers' extensive client base and distribution network. Further the acquisition of Pacific Indemnity strengthens AUB’s underwriting capabilities and scale, especially in the financial lines insurance sector. Finally it said that it has continued revenue expansion goals along with improved margins which it hopes to see across all its divisions. This will be achieved through a mix of technology improvements, synergy benefits and general business optimisation.
Risks
While a large part of their risk is removed by not being the premium taker, there are still risks that any investor in AUB should be aware of (outside of market and economic risks.).
One of the major risks in my view is the integration risk of recent acquisitions, such as Tysers and Pacific Indemnity, which may affect anticipated synergies and overall operational efficiency. History has proven that the complexity of combining these businesses poses risks related to alignment of culture, processes, and client management.
Operating in multiple jurisdictions exposes AUB to diverse regulatory environments. Particularly in the UK where the joke is often shared that it is where good companies go to die. Changes in regulations, compliance requirements, and data protection laws could lead to increased costs and affect the company’s ability to conduct business seamlessly.
Further it is important to remember that AUB relies heavily on technology for its operations, making it susceptible to cyber threats and potential disruptions. Cybersecurity breaches or system failures could lead to data loss, regulatory penalties, and reputational damage.
Finally, the insurance brokerage market is competitive, with both domestic and international players. Increased competition could pressure AUB’s market share and margins (profitability).
Conclusion
It has been wonderful to witness the evolution of AUB from the sidelines as it has grown from a solely local focused operator to a now global monolith. How it continues to evolve will be of interest.
It stands out as a resilient and growth-oriented company, driven by strong financial performance, strategic acquisitions, and a commitment to shareholder returns. Its diversified portfolio across insurance broking, underwriting agencies, and international markets, particularly with the addition of Tysers, enhances its global footprint and revenue potential. The company’s consistent dividend growth and efficient operational structure underscore its dedication to sustainable and responsible growth.
For investors seeking a solid, expanding business with proven resilience and forward-looking strategies, AUB could be that opportunity.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?