Avoiding interest rate sensitive businesses

We know rates have been rising and are at their highest level in over 10 years. When using the Screen Tool to identify stocks you can also use criteria to help avoid stocks. Given rates are high, this may be prudent to add such a criteria to help refine your lists further while reducing your exposure to interest rate risk. Below we will discuss some of them.
Stocks with high long term debt to equity
The ratio is calculated by taking the company's long-term debt and dividing it by the book value of common equity. It can be found in the Screen Tool.

The greater a company's leverage, the higher the ratio, and therefore more risk. A highly-geared company is more vulnerable to a sudden bump in the road, either operationally or due a change in the economy such as an increase in interest rates.
By using long-term debt alone rather than including short term debt means we measure the component of debt which is compounding and can lead to significant strain if left unchecked. That said, if possible, spend some time assessing whether there is any debt required to be refinanced into the near future. Doing so now will mean a higher rate of interest than what they had previously paid.
Note: due to the way accounting works there will often be nonsensical results. For example, stocks can have accumulated losses which result in very high debt to equity ratios as the accumulated losses are subtracted from the equity value (eg Qantas Airways (ASX:QAN) has a long term debt to equity over 42,000% as the equity value is so low (and planes are very expensive.)
Also some penny dreadful mining companies have very low debt to equity. But that is because they don't make any money, so who is going to lend them money in the first place? But there are many other risks these businesses carry that need to be assessed beyond debt/equity.
This can also throw up notoriously strange results for Financials businesses as obligations to clients/members are seen as liabilities. Therefore don’t read too much into the LTDebt / Equity on these businesses.
Stocks with a poor AltmanZ score
The whole premise of the Altman score is to identify stocks that could go broke within the next two years if things don't improve from a numbers perspective. That is why we use it to help measure Bankruptcy Risk.
So herein lies a problem. If the company is unable to improve operationally, then a higher debt burden will only weigh further on the business with either a capital raising or other financial stress emerging.
Look for companies with an Alltman Z score above 1.8 as an absolute minimum. Use the Altman 1 score for manufacturing businesses and the Altman 2 score for non-manufacturing companies.
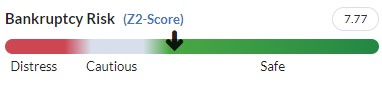
Note: this indicator is not to be used on Banks, REITs and Insurance companies
Stocks that pay a high yield / bond proxies
The past decade of anaemic interest rates forced many term deposit refugees into high income stocks as a means to supplement their income.
However as deposit rates start to "slowly" rise, the relative attractiveness of such stocks starts to diminish. This is because the risk reward/relationship between being in equities which are highly volatile vs cash products which are stable, changes as interest rates move. Why chase a 4% yield in a volatile share, when I can get it risk free?
This is one key reason REITs have been particularly volatile in the current environment. Therefore you may wish to consider using a filter for stocks looking for increasing consistent dividends rather than just “the highest”.
“Dividend per share CAGR of 5yrs” greater than 5% in combination with Dividend Yield of less than 4% is a good way to balance off a more modest yield with a stock that has grown the dividend that it has paid, providing some comfort that the company is focused on cash returns to investors..

Stocks where their fortunes are closely linked to consumer sentiment
This is fairly obvious but when the consumer is stressed they buy less.
At the moment, whilst consumers are mainly employed, they are feeling the pinch with high inflation. We are starting to see this in a number of updates to the market recently including National Australia Bank (ASX:NAB) who spoke of mortgage stress at its latest half year result.
While it is impossible to find stocks that either directly or indirectly avoid the potential issue of consumer stress (remember… Company Executives are consumers too), this point is to avoid stocks whose fortunes are closely linked to consumer sentiment, and without it don't have the operational strength to ride through the cycle.
Often running a cyclical business is not about making money while the sun is shining. Rather it is surviving when the winter solstice kicks in (figuratively speaking).
In the filter you can choose to exclude specific sectors. Select “Industry Grp” and then exclude the specific industries you feel may be at risk.

Non profitable business
Other than the obvious, the issue with investing in such businesses during a high interest rate environment is that interest rates are an input into future valuations. Basically the higher the interest rate, the higher the discount rate for future cashflows and therefore the lower the future value of a stock.
If your company is not making money and relies on capital raisings to stay alive, then not only does this impact perceived value in the stock, but means that future raisings may have to occur at an even larger discount resulting in greater dilution.
In your scans be sure to include metrics that ensure your companies are profitable. Using the Quality factor in your scans is also particularly useful at the minute.
Stocks not expected to produce positive cashflows
Further to this point, you want profits to translate into cashflow.
There are three sources of funding for a company, Debt, Equity and Cash. Cash is by far the cheapest and best source of funding.
But if you company is not producing Cash then they will require other sources of funding which in a rising rate environment become more expensive.
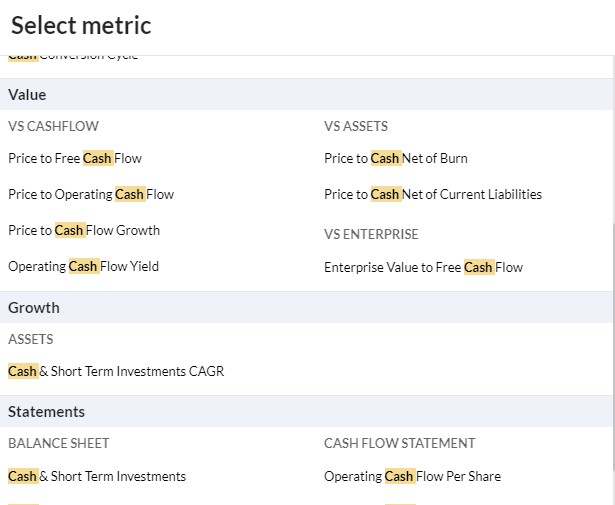
Therefore when you are screening for stocks, look at including criteria such as "Cash Return On Invested Capital", "Free Cash Flow per share" or "Free Cash Flow 5yr CAGR" to help identify business that at least are self funded within their current operations.
Stocks with nose bleed valuations
As mentioned above, as interest rates make up part of the input of a valuation, as interest rates go up, the valuation of future cashflows comes down.
Therefore stocks trading at nose bleed valuations are at risk of corrections. While the impact on non-profitable businesses has been discussed, even on profitable companies this needs to be a consideration.
So when you are looking at companies, be sure to be wary of stocks with poor value ranks (even the profitable ones). However, don't just look at value alone. Be sure to compare a stock against peers because if you find two stocks which look like similar businesses, in the same industry, operating at similar levels, then it is likely the more expensive one will see its price suffer more in a rising rate environment.
Also consider using PE to help rate stocks relatively. While the last decade has seen valuation ratios like EV/EBITDA and Price/ EBIT gain popularity, none of these capture the "interest" component of the income statement. In high rate environments PE can be more insightful as it does capture that element.
One feature that may prove fruitful here is the “Compare Tool”. So once you run a screen, note the four or five companies that look of interest. Then search one of the companies (in this case I did BHP (ASX:BHP) BHP. I can then go to “Tools >> Compare with….” This will allow me to compare BHP against the other stocks in my scan of interest (in this example it is RIO, FMG & IGO)
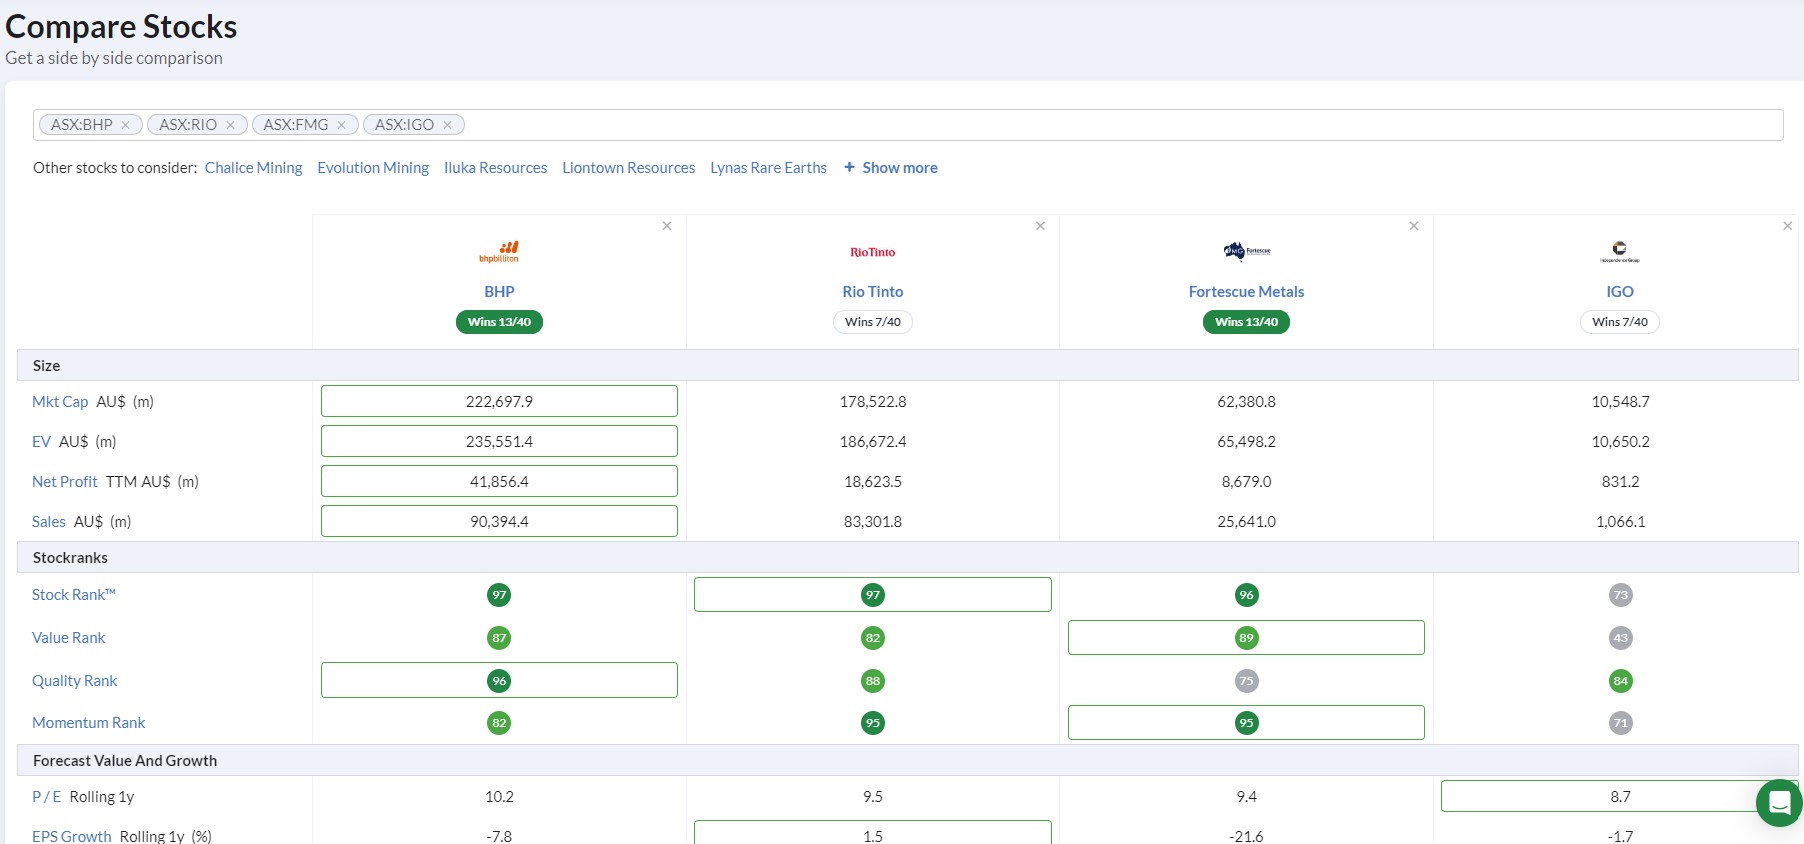
I can now compare the PE against the four (as well as a number of other criteria. (In this example IGO (ASX:IGO) has the lower PE on a rolling basis.)
Don’t worry…. Help is but a click away.
If any of the screen criteria discussed come across as confusing, don't despair, there are excellent definitions within Stockopedia that explain how each criteria works and how you can apply it. If that fails, we are always here to help.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
2 comments
Thank you Elio for another extraordinarily enlightening Report.
Your thoughts please.
It seems, possibly with the RBA assessment, and surrounding commentary, of an 80% possibility of a decline in 2024, Cyclicals will be viewed negativity. Consequently, this is a sector which could provide opportunities whilst the market focuses on defensives. I wonder if the similar opportunities could occur with low PE's.
Yes, every correction creates opportunities especially in cyclicals. (That is unless you feel people will never ever again buy shoes, pyjamas, meat pies, vases or brand name t-shirts.)
As with most things the market is forward looking and therefore though 2024 will be tough, that will be reflected in prices beforehand. A simple rule of thumb I find is, if there is a company that has fallen 50% from its recent high, and it is high Quality, then I will be inclined to have a look. While it could obviously fall further, 50% of steam out of the price is a significant chunk I've missed.
What we need to be cautious of is the adding of double negatives. Where we have one negative sentiment event, then things stabilise, to only be followed by a negative sensitive event. Funny how a stock falling from $4 to $2 is exactly the same as a stock falling from $2 to $1.
However we are not in correction territory yet.... so plenty of time to snap up more bargains if you hold the view that cyclical businesses are in for a tough time. Thanks for the comment.