AZJ Revisited: Falling off the rails
I thought it would be good to revisit a stock that we have talked about and has had its latest financials updated within Stockopedia.
Aurizon Holdings (ASX:AZJ) operates one of the largest rail networks in Australia and transports a comprehensive range of commodities, including mining, agricultural, industrial, and retail products for a diverse range of customers across Australia. As mentioned, this has been covered at depth in a previous commentary of the business. For those that need to familiarise themselves further with AZJ you can refer to my previous article written on 23rd August 2023 .
AZJ over recent years has increased debt levels and acquired One Rail in FY22, invested heavily in new wagons, upgraded terminal & port services infrastructure, and purchased new locomotives in and attempt to diversify revenue, earnings, and profits away from the regulated returns of their Central Queensland Coal Network (CQCN) asset. As in, FY23 CQCN generated circa 30% of AZJ’s revenue & earnings and nearly 70% of profits and a quick look at their FY24 segment breakdown it doesn’t look like much has changed.
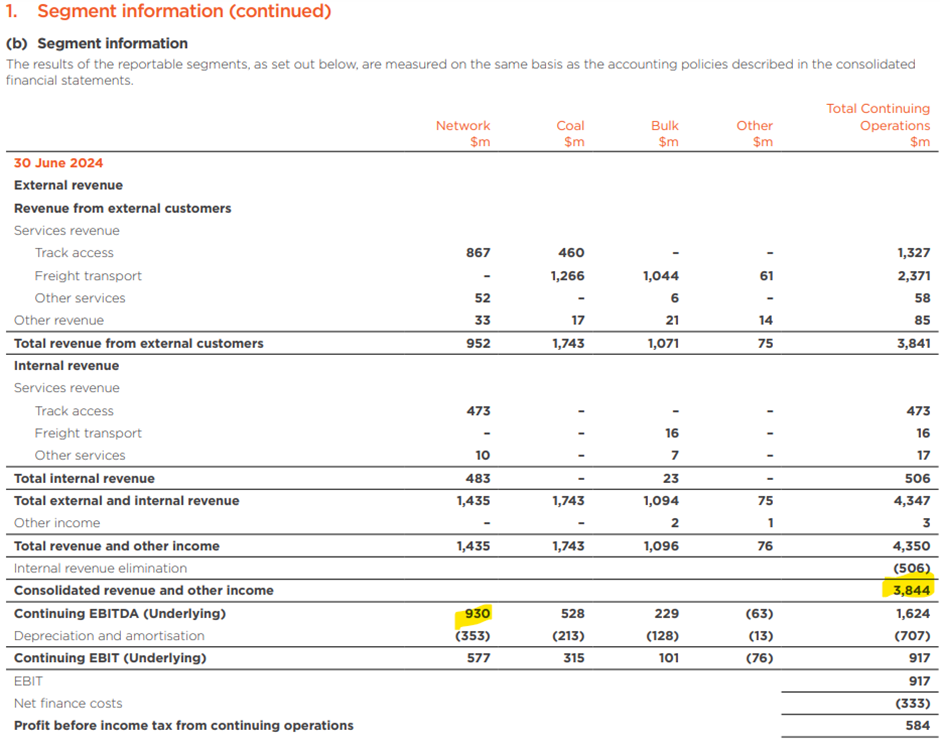
Source: AZJ FY24 Annual Report
Other points of interest are, AZJ’s financial performance over the past 6-years had been lacklustre with revenues returning to FY15 levels, otherwise remaining flat. Profitability and cash flow measures have been in decline. Interest coverage has fallen from 6.8 in FY22 to 3.09 in FY23 on the back of increased debt levels and declining cash in the bank. However, since 2016 AZJ has returned $5bn to shareholders via dividends and share buy-backs and generated free and operational cash flows during this period. So given AZJ reported early this month, let’s see how they are going with their goal of diversifying away from their CQCN by increasing exposure to bulk and containerised freight.
StockRank:
First stop, the StockRank and individual factors. On the back of a much-improved financial performance in FY24, which saw net profit increase from $276m in FY23 to $406m in FY24. This on the back of AZJ increasing revenue and operating profit from $3.5bn to $3.8bn and $713m to $913m respectively. The improved FY24 performance has resulted in AZJ’s Quality factor increasing from 66 to 83. Their Value factor has increased on the back of the improved financial performance and AZJ’s share price declining from $3.68 in August 2023 to $3.32 at the time of writing. Momentum has further declined by 29 to 38 at the time of writing. The sum of this is AZJ’s overall StockRank increasing by 5 points to 75.
August 2023

August 2024

Having a light read of the Chairman’s and CEO report in AZJ’s Annual Report there is a definite softening in the diversification strategy compared to FY23, with the focus now being on the resilient earnings of the business while capitalising on the expected growth in bulk and containerised freight. With the CQCN being the major contributor to the resilient nature of the AZJ’s business.
AZJ also noted that they had rounded out their investment in bulk and containerised business segments in FY24, too.

Despite AZJ’s improved performance, shareholders have the right to be disappointed with this, given one year ago this diversification strategy featured prominently, with this strategy and was the main reason why AZJ increased debt.
This change in narrative I would suggest is the main reason AZJ’s StockRank is flat, as the worsening Momentum, supported by the price decline and analyst write-downs, offset the gains in Quality and Value.
Financials:
On the back of increased earnings and profits AZJ are in much better financial shape with their F-Score increasing from 4 to 7. With a large part of this increase due to the substantial increase in cash flow from operations increasing from 57c a share in FY23 to 87c a share in FY24.
August 2023

August 2024

AZJ’s bankruptcy risk has remained flat with the main two issues contributing to this cautious reading, being, book value does not compare favourably to liabilities and their assets mainly comprise illiquid assets.
More to this point, for a company that has a net-gearing ratio of 113% you would expect to see better asset liquidity than a quick ratio of 0.57 and interest coverage of 2.75. These ratios have not improved much since FY23 result’s, either. Another contributing factor to AZJ’s lacklustre performance is AZJ’s book value which has remained flat since 2019.
August 2023

August 2024

On a more positive note, AZJ did increase revenue and operating profit and margins. With this flowing through to profitability. With all profitability ratios except for ROA up 3-4% on FY23.

Also, AZJ has committed to an on-market share buy-back of $150m in FY25. This is small in the scale of things given AZJ is a $6bn market cap stock and will have minimal impact in terms of helping their share price.
It does however continue with their recent trend of decreasing the amount of shares they have on issue.

Liquidity and Ownership:
AZJ sit in the big end of town with a market cap of $6.2bn and 1.8bn shares on issue with 99.4% of these shares classified as free float. Their largest shareholder accounts for 7.09% of issued shares and top shareholders accounting for 35.09% of issued shares. With all this being said, there is plenty of AZJ shares to go around and a DIY share investor will have no issues buying or selling shares.

Outlook:
AZJ’s operations are highly leveraged to hard & soft commodities, and the growth areas of bulk and containerised freight. They have a dominant market poison and national footprint with critical infrastructure in most states.
AZJ is forecasting for FY25 group EBITDA to be between $1.66-1.74bn (FY24 1.62bn) and is expecting Network EBITDA to be higher than FY2024 with an increase in the regulated revenue, partially offset by lower external construction works. Coal EBITDA is expected to be broadly consistent with FY2024. Bulk EBITDA is expected to be higher than FY2024 driven by volume growth in Bulk Central, and containerised freight is expected to have a broadly neutral EBITDA contribution.
This outlook from the company differs with consensus estimates though who expect a decrease in net profit in FY25 and FY26.

You can quite visually see it as EPS downgrades following the recent result (contributing to the negative Momentum Rank move.).

Conclusion:
If AZJ’s FY24 results have told us anything, it’s that the CQCN is still the engine driving AZJ as it is the major contributor to earnings, profits and cash flows and their diversification strategy has lost momentum.
With the only real positive being that the AZJ board is happy to return capital to shareholders via dividends and share buy-backs, albeit small in terms of their overall market cap.
What I see in AZJ is an average company that has a questionable diversification strategy and has underperformed for many years. For the most part they have been able to get away with this; Due to the ability of their CQCN asset to generate profits and cash flow for the company.
But as the saying goes “profits cover many sins”. However, based on their share price performance of late, maybe investors have already started looking elsewhere.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
1 comment
AZJ continue to under perform, it does look like they are focusing on reducing costs now. Read the business update here:
chrome-extension://efaidnbmnnnibpcajpcglclefindmkaj/https://cdn-api.markitdigital....