Best Of The Best - a high quality growth stock for troubled times?

No doubt most investors are feeling bruised as a result of what is proving to be a pretty ferocious stock market drawdown. Even good companies are getting hammered.
Such conditions do provide long term opportunities, though, as Mr. Market presents us with new prices every day. Those good companies are just as high quality as they have ever been, it’s just now they are cheaper than they were a couple of months ago. Now more than ever it’s important to identify the best stocks to invest in because the odds are we will get chances to buy at good prices.
On first glance, Best Of The Best (LON:BOTB) shows some signs of having what it takes to be a long term winner. It has a clean balance sheet. Its revenue and profits have been growing consistently for years. It has a QM Rank of 98. It generates consistently strong returns on capital and chucks off cash, which is reinvested in growth opportunities or returned to shareholders. The founder still runs the company and owns nearly 50%.
These are promising early signs.
It looks like there will be significant disruption to certain parts of the economy as a result of measures to prevent the spread of Coronavirus. I imagine a lot of Leisure & Travel companies are registering some pretty steep like-for-like revenue drops right now, for example. Other companies will be less affected by these measures, and this is where there might be some opportunities.
The key driver of growth for BOTB is its evolution into a purely online host of weekly skill-based competitions. I think this could make it reasonably well insulated from the challenges other parts of the market are facing.
The story so far
Ever since 1999, car enthusiast and BOTB CEO and founder William Hindmarch has been busy building a cash generating machine - and, with a market cap of just £37m, I reckon there is still plenty for BOTB to aim for.
The group’s core business is in running car competitions. Once upon a time you would find them in airport terminals and shopping centers but the world has changed and now these competitions are online.
There is a lot to like about this company from a financial and shareholder perspective. A well run operation is one thing though. What makes BOTB interesting now is that it has a big expansion opportunity and is executing on it as we speak. Today, its addressable market is much larger than it was 20 years ago. As BOTB itself notes:
The Company continues to evolve away from being an operator of retail based car competitions, to a pure online operator. The scope and breadth of our competitions and other products will be further developed to target the much larger addressable market online, both in the UK and internationally, using all available marketing channels.
What’s more, as it moves online, the company cuts out rent and labour costs and marketing becomes more targeted. Social media and TV advertising are having a pronounced effect on revenue growth - and the more money BOTB makes, the more it can spend.
The data is a little patchy on the group’s progress here but I’ve cobbled together a table that shows everything appears to be moving in the right direction:
March 2020 | 2019 | 2018 | 2017 | 2016 | 2015 | |
270,000 | 249,000 | 215,000 | 185,000 | 160,000 | 120,000 | |
17,700 | ||||||
114,000 | 80,000 | 50,000 | ||||
Youtube | 37,600 | 31,000 | 23,000 | |||
Website monthly visits | 180,000 | 225,000 | 165,000 |
Over the past seven years, online revenue has grown at a compound annual growth rate of more than 33%. The trajectory is still strong: online sales have increased by more than 30% year-on-year in the past two years as well and are now almost all of BOTB’s business.
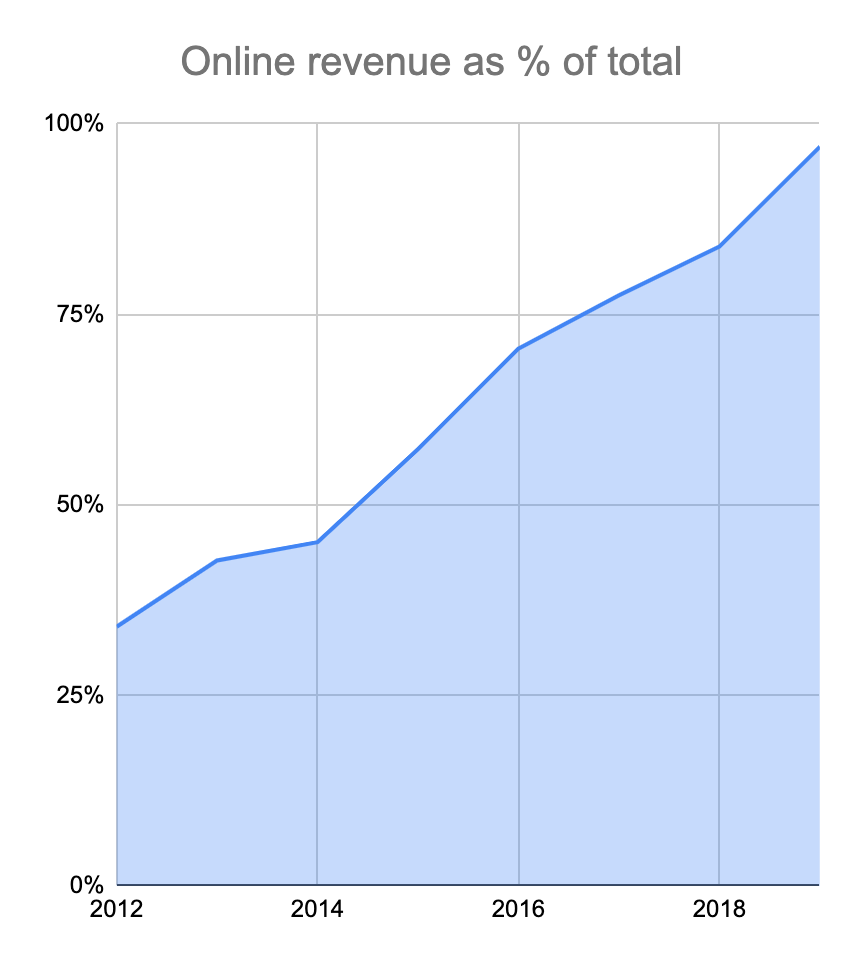
The evolution into a pure, higher margin online business appears to be a successful one. BOTB is growing sales, profits and marketing efficiency. An enlarged, predominantly in-house marketing team has invested in a multitude of channels, including Social Media, TV, Radio, PR and YouTube Influencers to acquire new players.
The enhanced insight into its customers that these new channels bring is paving the way for more tailored competitions, pricing and products. It also gives BOTB a better chance of building a relationship with people that might encourage them to participate in future competitions.
On top of this growth, the group operates with a reassuring sense of financial safety - no debt and strong cash generation. Meanwhile, the move to exit from shopping centres and airports has allowed it to shed costs, particularly rent and staff expenditure.
Nearly a decade of steadily increasing revenue and profits
This strategic shift is supported by some very encouraging figures. Revenue and gross profit have increased every year for the past nine years. Operating profit has increased every year for the past seven years and operating margins continue to improve.
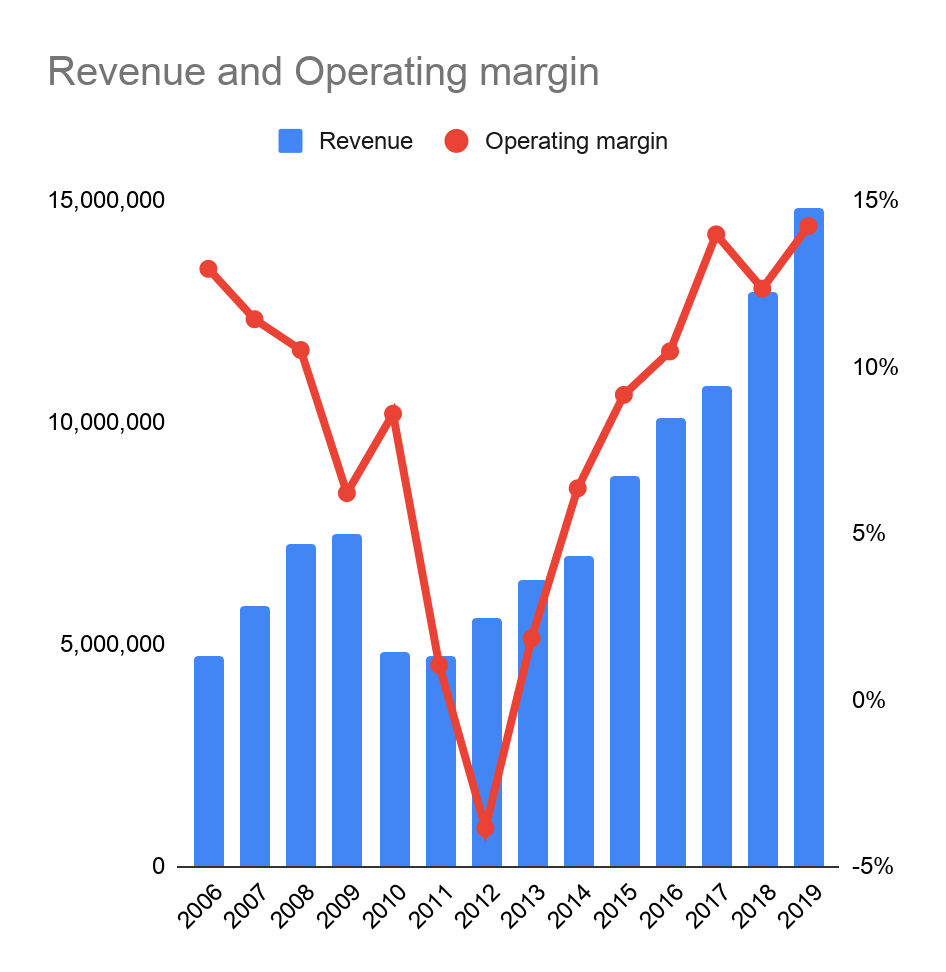
We can see that BOTB has an impressive track record across key financial measures in the 2014-2019 period:
2014-19 CAGR % | |
Total revenue | 16.2 |
Operating profit | 60.1 |
Net profit | 61 |
Free cash flow | 50.6 |
EPS normalised | 35.3 |
Dividend per share | 12.7 |
HY20: Interim results for the six months ended 31 October 2019
Back on the 30th of January, Paul wrote in the SCVR that he “like[d] everything about these figures” and it’s not hard to see why:
- Total revenue +6.7% to £7.6m
- Profit before tax +27.8% to £1.38m
- Earnings per share +37.3% to 12.4p
- Cash balances of c£4.3m
- A special dividend of 14p per share declared
- Encouraging sales momentum and FY earnings to be in excess of forecasts at the time
The update sparked another upgrade to broker EPS forecasts. These upgrades have been material: up from 12.4p in March 2019 to 22.7p in March 2020.
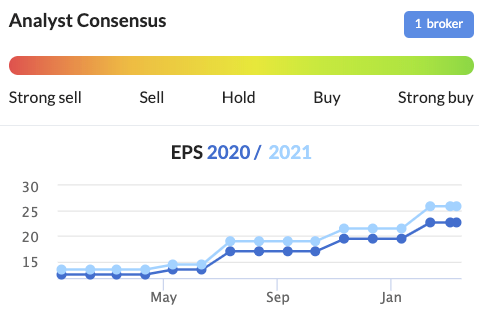
Sometimes when this is the case analysts can be slow to appropriately price in the near-term upside. It’s not something I’d bank on, but it is certainly nice to see the positive direction of travel.
Financially safe, cash generative and aligned management
BOTB has some encouraging quality characteristics. It is heartening to see a cash-rich balance sheet and management alignment with shareholders.
Trading at just 15 times forecast earnings despite high returns on capital and a better-than-expected half-year statement, this looks like a promising “QARP” candidate with a strong operating track record and ample room for future growth.
Strong balance sheet
The group has historically been financially prudent, with net cash on the balance sheet even after frequent special dividend payments in recent years.
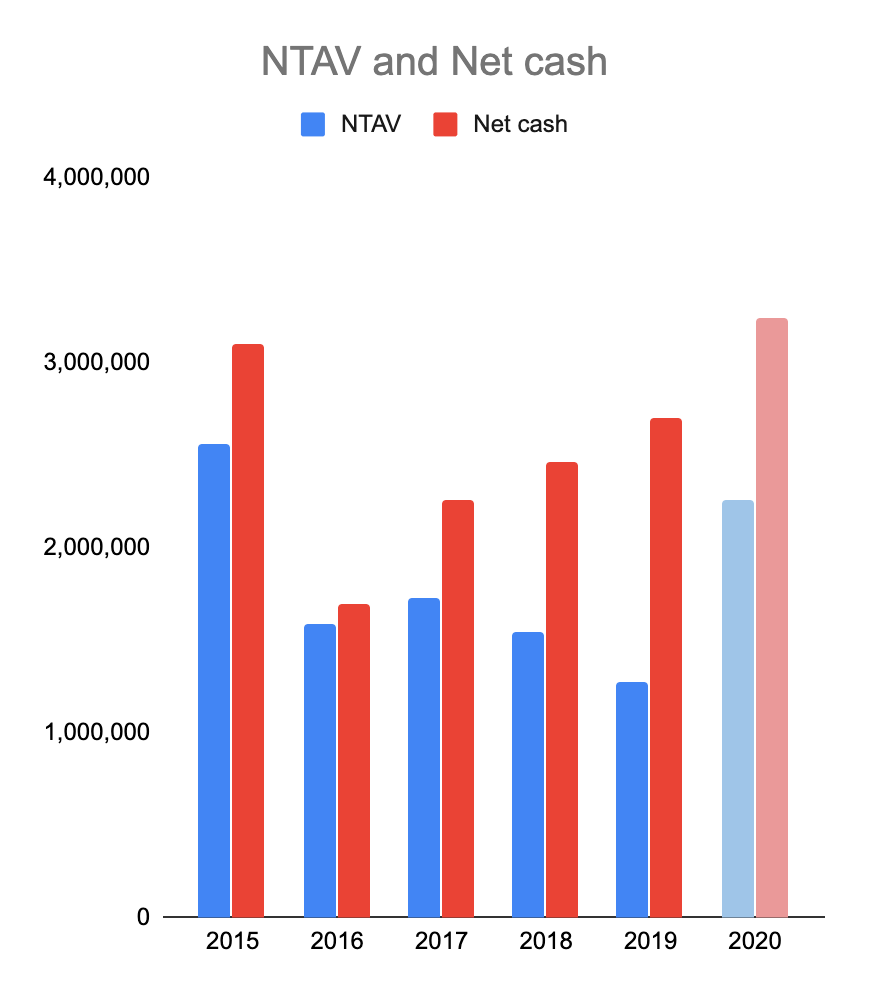
The balance sheet is also quite clean. No pension fund, no debt, very few liabilities or intangibles that need to be checked out.
Solid liquid and strong cash generation
The group converts a high proportion of net income into free cash flow, which is good news for shareholders:
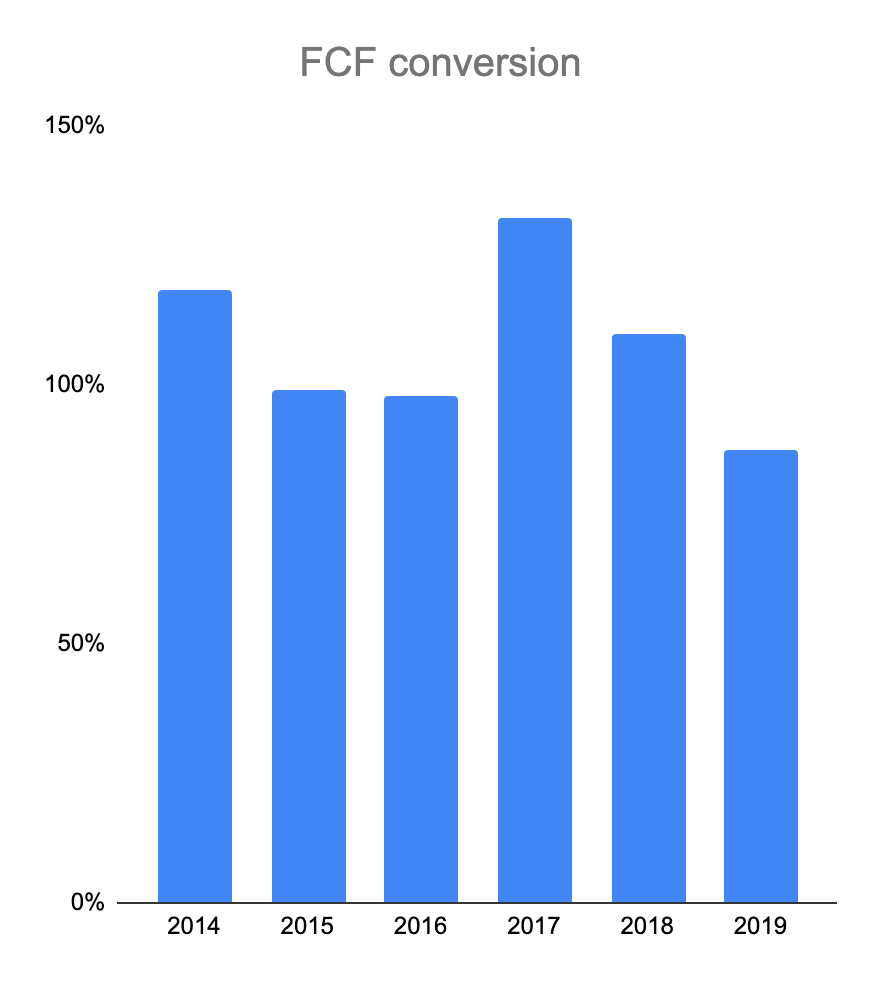
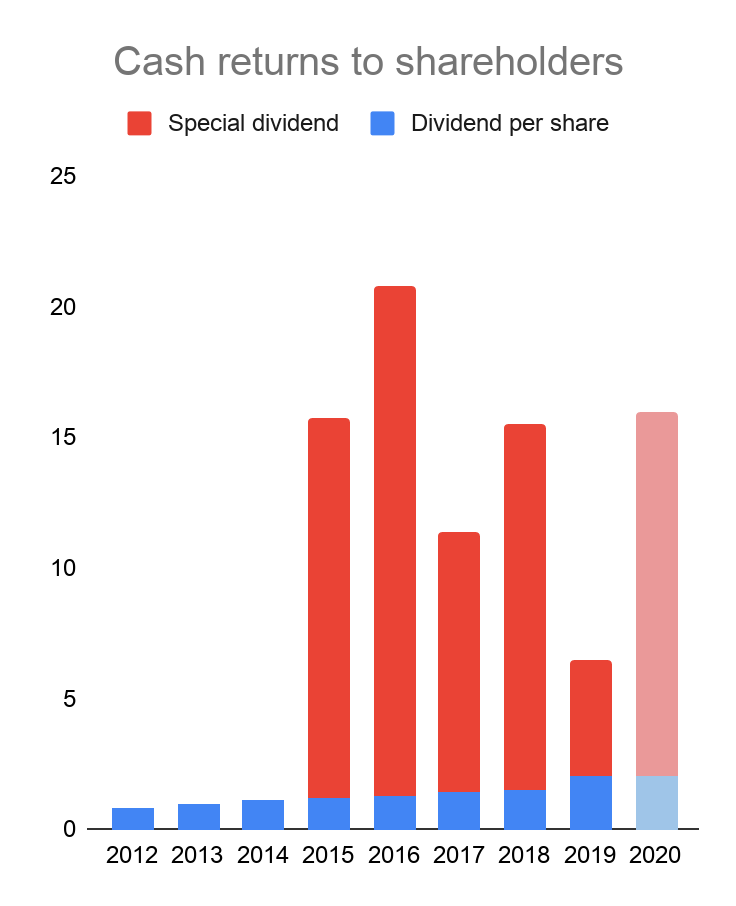
While some of this cash is reinvested back into the company, a lot of it is simply returned to shareholders.
Aligned management
It’s fair to say the board has skin in the game here - between them, they own about two-thirds of the company. The holdings as of 30 April 2019 were as follows:
Shares held | Percentage ownership | |
William Hindmarch | 4,725,658.00 | 50.39% |
Ruperta Garton | 1,389,467.00 | 14.82% |
Michael Hindmarch | 832,023.00 | 8.87% |
David Firth | 4,623.00 | 0.05% |
This does have implications for the liquidity of this micro cap’s shares given its tiny free float. Nevertheless, I take it as a positive for shareholders that management holds such a big stake in BOTB.
Risks
As with any micro cap, there are risks to consider.
In the group’s FY19 accounts, BOTB registered a sizeable exceptional gain as a result of a tax dispute with HMRC. While this clearly worked out for BOTB, it does flag a degree of exposure to regulatory risk depending on whether you interpret BOTB’s competitions as skill or luck-based.
The group’s small size and tiny free float also make its shares quite illiquid, which can make buying and selling expensive. As BOTB is also now entirely online, it is prudent to acknowledge the potential for website and IT infrastructure disruption.
Conclusion
While the small size of BOTB both in terms of market cap and free float might put some off, I see a lot to like in this company.
It is run by its founder, who retains a large shareholding. This alignment with investors is reflected in the company’s generous dividends in recent years. BOTB earns superb returns on capital and the group’s shares have held up well in the recent market sell off.
This latter point is possibly as a result of its cash-generative online business model and debt free balance sheet making it one of the safer stocks from Coronavirus related disruption.
Over the past seven years, online revenue has grown at a compound annual growth rate of more than 33% and has increased by more than 30% year-on-year in the past two years. Operating margins have improved and profits are growing. Given this track record, a valuation of 15.1 times forecast earnings looks undemanding.
A key point now is how much you can trust forecast earnings in general, given the widespread disruption created by the spreading Coronavirus. This development will be potentially disastrous for a lot of companies, so caution is key. There is no rush to invest but I also think now is the time to be identifying opportunities.
BOTB is reasonably well insulated from this risk and it has strong quality characteristics. For that reason, I think it is worth monitoring to see if the market unduly discounts its growth prospects for the years ahead.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

12 comments
The price now has halved to 1620p. A bargain, or might it be another Patisserie Holdings, as earnings manipulation risk is rated as high.
I shared my current watchlist with a friend who fairly recently became interested in the markets following the launch of new trading apps like Trading212 and Freetrade. (Yes, I know I should’ve taken that as signs of a frothy market!).
Below is his reply to me. Apologies for the lack of eloquence, I wanted to leave it unedited... But I do think it is a fair piece of scuttlebutt that has put me off for now.
“I wouldn’t buy BOTB.
I used to play that shit when they were the only ones doing it. People got pissed off as it’s basically spot the ball. But it’s not a true win.
You pick a dot where you think the ball is and they have a panel of celebs or football experts who decide between the three of them where they think it is. The closest to their dot wins. Not the closest to where the actual ball is.
It’s a shit system and people have sussed it out. But more importantly the market is flooded now with more companies doing the same thing but with a raffle ticketed system so everyone actually has a fair chance of winning. Tickets on the other sites are limited to so many per person. 7 Days Performance is the one I use now. But there are many others with Celebs off Love island and Towie etc promoting them now.
Just my opinion.”
Hi Bryans,
Thats very interesting, and quite blunt, what I dont like abut BOTB is that they might sell 100 tickets or 1000, and you never know if the prize is proportional to the revenue & therefore the casino's 'take'. So quite easy to feel the odds are against you, 7 day performance limit the tickets and show you how many sold, so you can work out their take & rough profit and. decide if thats 'fair enough'. I have a lowboy order in, but I dont like the business model enough to make it a long term hold.
7 Days Performance looks rubbish - it is more expensive and a tiny number of options. Are there any serious competitors to Best Of The Best (LON:BOTB)? That's an important Q
Hi Jack,
Best Of The Best (LON:BOTB) is one of the few shares that I have held through the recent events, as I think it should be fairly insulated and, if anything, receive a small boost from people staying at home and happy to spend a few £s/EURs/etc....
However, one thing that concerned me from the last results was that online growth of 30% from the previous 2 years actually slowed to 13% in H1 FY20 (and that follows a sequence of several periods of downward growth starting from 2017-18 H2: 53%, 49%, 19%, 13%).
That's quite a drop.
For what it's worth, I still think the company is undervalued, even with such low growth rates.
Cheers
A
Thanks abtan, much appreciated. I saw the slower HY20 top line growth but, given the double digit profit growth and management's track record, I provisionally gave it the benefit of the doubt.
I did not see that it was following on from lower H219 revenue growth... Certainly something to monitor and be aware of.
Is this a temporary dip, or is this Best Of The Best (LON:BOTB) reaching a ceiling? I'm minded to think the former, for now. Management says that it is growing into a much larger addressable market, although I haven't seen any solid market data and want to scope this out a bit more.
I'd just flag, that the online growth comps were very tough over the last 2 halves, and now start to ease. And the numbers are not truly like-for-like above as have the regulatory regime change part way through.
What's interesting in my eyes is that the market can now look to see growth re-accelerate again at the top line given airport revenue is now basically gone. So it's pure online and the growth should significantly accelerate from the around 6% group growth in the first half of the year.
If this company can sustain, let's say 8-9% organic growth for 5 years (in reality think they can do 10-15% - the market is significant and they have clearly the best position product-wise and financially), then a 15x multiple is really not expensive at all, so totally agree with you Jack. The financial quality metrics are very strong and should really justify a strong premium multiple (20+).
In terms of competition, there are definitely competitors but they're very small. Don't think a comparison between Rightmove and On the Market would be an unfair analogy (not saying this is as high quality as RMV!). Can tell very simply from the arrange of products you can enter into. That moat is valuable IMO and having the bigger marketing spend helps you build out that moat greater over time.
It's pretty much now just a case of them chucking marketing spend into the funnel to maintain strong growth. The number of users they must have is likely a tiny fraction of their total potential user market and easy wins to go after in terms of mobile conversion rates etc. And we know the company is in good shape at the moment with building momentum. I can't see any coronavirus impact here either.
Simple question for me; Revenues here were around £15m last year. Can this grow to £30m? I don't see what the constraint on that would be. And with operational gearing and multiple expansion, that would be pretty clear upside. End game I imagine is that they sell the company and the raft of customer details to a larger player, however far in the future that will be. Forecasts out there by Finncap look conservative (as they have proven to be historically)
Hello Jack, nice piece as always & coincidentally i put in a resting order @ 320 today. The price ran away a little while ago, but 320, who knows with this market.
Less footfall through airports as a result of the virus.
Revenue is almost 100% online now
A very sensible analysis of an unusual, small company. I note the possible difficulty that could arise when needing to sell when the Market is volatile. Now is the time to watch and wait.
Cheers Anthony, I agree that the lack of liquidity could be the big drawback for a lot of investors. I'm personally looking for "buy and hold" type investments where getting in and out is less of a concern. In that regard, I think there are some promising signs from £BOTB.
I'd like to get a better picture of the size of the competition market that BOTB can grow into, and how good its competitors are. A key part of the company's attractiveness, for me, will be the scale of its growth prospects, which I would like to do a bit more work on...