Billington profit outlook falls apart on problematic contracts

Analyst’s view:
It's unfortunate to see that both 2026 and 2027 estimates have been cut, even though 2027 will benefit from profit that has slipped out of the current year. The company's downbeat commentary on conditions in the wider steelwork and construction markets seems to have fed into lower forward expectations. Based on 2027 forecasts, the P/E ratio is now 7.5x. I don't view this as a bargain, considering the sector and the difficult market conditions, but the balance sheet does potentially offer some support. For that reason, I don't see the need for us to take a more negative stance.
Down 17.5% at 338.5p (£45m) - Trading Update (profit warning)
We've been moderately positive on this structural steelwork contractor, but it has let down investors today with a poor update.
2026 underlying PBT is expected at £4m to £5.5m, well below market expectations for £8.3m.
When such a large profit warning happens so late in the year, it tends to exacerbate the disappointment.
However, in this particular case, there are reasons to think the underlying business might not be doing quite so badly as the size of the profit warning suggests.
There are "two contract specific matters" that have undermined its profit performance for 2026:
This expectation arises as a result of previously anticipated contract profits not being recognised in FY26 and the performance of an industrial project. A final determination as to whether certain contract profits can be recognised will be made following the year end and, accordingly, the final FY26 outturn may be at the higher end of the range referred to above.
Accounting rules require that revenue can only be recognised when obligations under a contract have been satisfied.
With a contractor like Billington, the date when obligations have been satisfied might fall just before or just after financial year-end, having an enormous impact on profitability.
Along these lines, one of the "contract specific matters" is to do with "client-led delays to a significant bridge contract being undertaken by Tubecon". These delays have pushed its profit recognition into 2027. But note that Billington may have already done some or most of the work for this contract in 2026.
The other problem is more substantial:
The Group has experienced a disappointing performance on a contract for an industrial sector project in the north of England. The project has proved more challenging to deliver than anticipated and, following a reassessment of the costs required to complete, the Group expects a material reduction in the margin contribution from the contract.
This is unfortunate but not a very uncommon event in the sector - and it's one of the reasons that contractors tend to trade cheaply. Profit margins can be thin and unpredictable, even for the company itself. Hopefully Billington will have learned from this experience.
With the problems constrained to only two contracts, Billington is able to say that "Notwithstanding some of these contract specific matters, performance across the wider Group remains positive."
Looking ahead, the company has "a record order book, providing good visibility through 2027 and, for certain projects, into 2028", even though overall conditions aren't great:
The wider structural steelwork and construction markets remain challenging and subject to continued pricing pressure. However, Billington remains well positioned in those sectors where demand is strong and continues to have a substantial pipeline of further opportunities.
Estimates
Many thanks to Cavendish for covering this one. They have left revenue expectations unchanged both for 2026 and for 2027.
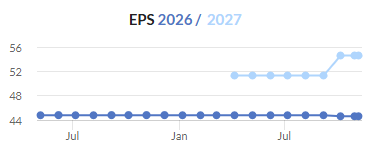
In terms of profitability, it's unfortunate to see that both 2026 and 2027 estimates are cut, even though 2027 will now benefit from the Tubecon bridge contract contribution. The adj. PBT estimate for 2027 falls by nearly 11%, from £9.5m to £8.5m. The adjusted EPS estimate for 2027 falls from 51.3p to 45.1p.
Graham's view
The downbeat commentary on conditions in the wider steelwork/construction markets seems to have fed into lower 2027 expectations.
With 2027 starting in eight weeks, I think it's fair to value this on 2027 earnings rather than 2026 earnings at this stage. That puts the shares on a P/E ratio of 7.5x at the current share price.
Is that cheap? On the basis of that earnings multiple alone, I don't think so.
I generally expect contractors to trade on single-digit earnings multiples, even in benign market conditions. But conditions are challenging, with "continued pricing pressure", according to the company.
And as we know from experience, profit warnings are generally followed by an increased risk of further profit warnings.
Billington's EPS forecasts had been holding up quite well until this point:
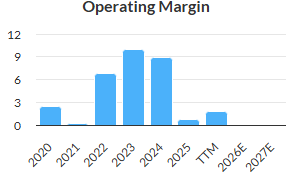
But note the volatility of the operating margin, and how thin it tends to be:
As for our stance, I am taking us down to a neutral position here. The balance sheet does potentially offer some support: estimates suggest that it will finish 2026 with net cash of £15.1m (source: Cavendish). For that reason, I don't see the need for us to take a more negative stance.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Billington Holdings (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?