BIS: Steeling themselves for future success
Bisalloy Steel (ASX:BIS) is an Australian steel manufacturer that specialises in designing and producing high-strength steel products, and has done so for over 40-years.
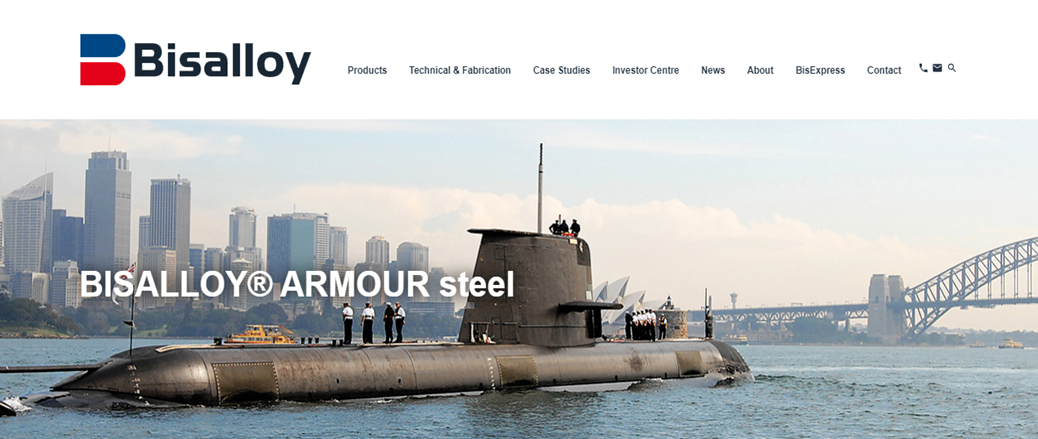
Publicly listed since 2003, BIS offers a range of products including wear-resistant steel plates, military-grade armour, structural steel, and mining equipment. BIS is Australia’s only quench and tempered (Q&T) steel plate producer which serves our mining and defence industries. One of the notable products from BIS is their Bisalloy Armor steel, which is specifically developed for military applications, with this product being used in our Collins Class submarines and Bushmaster vehicles deployed in the Ukraine conflict.
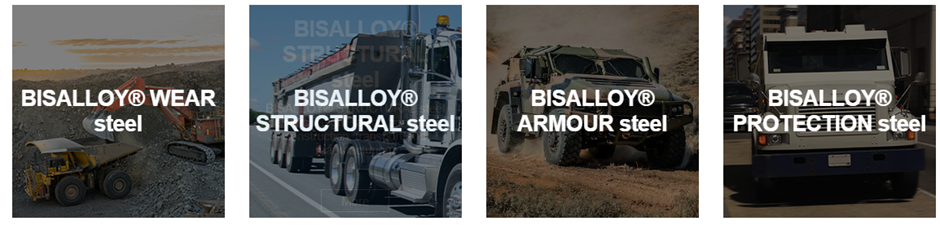
BIS comprises two operating segments, Australia and Overseas. Their Australian operations manufacture and sell wear-grade and high tensile plate through distributors and directly to OEMs in Australia and abroad.
Their Overseas operations comprise three entities operating in China, Indonesia and Thailand which distribute Q&T plate as well as other steel plate products.
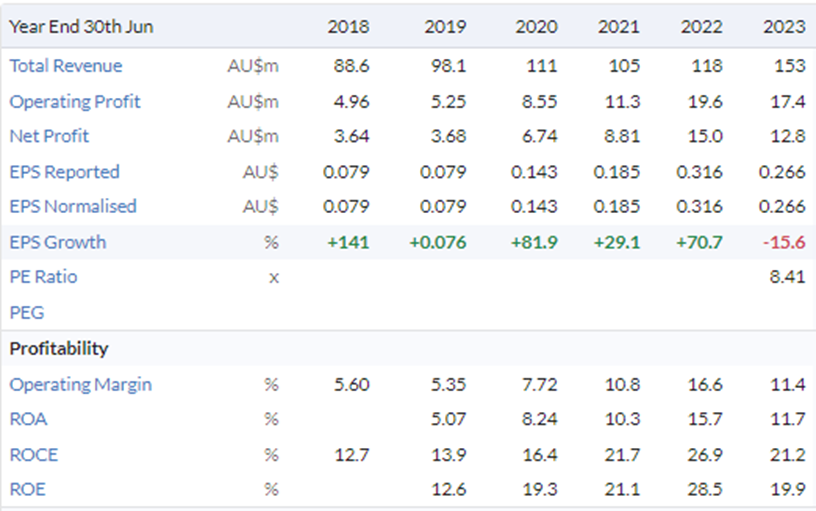
The Australian segment of the business is the largest by far contributing $128.8m to total FY23 revenue of $153.1m, with the overseas segment contributing $24.3m in revenue. FY23 revenue was up 30% on FY22, but due to higher inputs (gas & electricity) and freight costs, earnings and profits declined 7.5% and profit 14.6%. BIS has reduced their workshop employees by 20% to help offset rising costs.
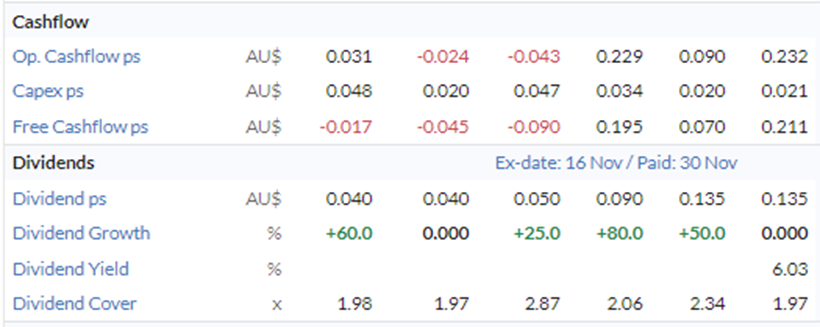
Further impacting the full potential of sales was a change to their enterprise resource planning system (ERP) which impacted sales of some products, this has been rectified. Despite these headwinds, BIS continues to be a profitable company generating solid returns and paying dividends and will pay a special dividend of 10c per share in November 2023 (goes ex on 16th November)..
Looking forward to FY24 and beyond BIS is continuing with its growth strategy of focusing on the premium grades of Q&T steels, including armour and defence grades, while developing the volume growth of other products.
StockRank:
Given the headwinds the business has faced, their StockRank and QVM scores are impressive and speak to the underlying quality of the business and the demand for their products. BIS have continued to increase sales and for me most importantly, operating cash flow and free cash flow. With these two factors being a driver of Q and V, especially value when valuing them based on a price to sales ratio.

“Anticipated headwinds including, international steel plate prices, increased shipping costs, disruptions to international and domestic shipping, and ever-increasing energy costs… continue to affect the business.” - BIS Annual Report FY23.

“Our freight costs and in particular sea freight to our Western Australian market also increased significantly during the year. We do not see this situation changing in the near term and are looking at alternative and more cost-effective forms of transport to maintain our supply.” BIS Annuel Report FY23.

BIS has no broker coverage (due to their small-cap status) which impacts their Momentum figure but despite the lack of coverage, Momentum is up 10 points over the past 30-days to 60 with relative strength %, volume change % and price verse % all up indicating there is support and buying interest for their shares (see image above).
Financials:

Given revenue has increased but margins and profitability decreased, it’s not surprising to see BIS’s F-Score at 5. I am also comfortable with their Z-Score sitting just in the safe zone given they have very little debt and good asset liquidity.

The theory is that large blue chip stocks trade on a high PE multiple due to their market strength and stability of earnings and profits etc. So, by quickly comparing BIS to BlueScope Steel (ASX:BSL), a David and Goliath comparison, we should see BSL with superior returns and margins.
BIS

BSL

However, despite their diminutive stature, BIS has higher margins and returns than a company some 80 times larger! Highlighting the quality of the business, products, and their competitive advantage in being Australia’s only Q&T plate manufacturer.
Liquidity and Ownership:
As mentioned previously BIS are on the small side of small with a market cap of $106m and 47.5m shares on issue, with just over half of issued shares being classified free float and able to be traded.

This is mostly due to major shareholders holding 50.1% of the company and the top two shareholders owning nearly 30% of the company, including its Chairman David Balkin.
This makes AGM’s and anything that requires a shareholder vote a forgone conclusion and the ability to get larger parcels of stocks impossible unless further equity is issued. As much as I like the stock, an investor needs to keep this in mind and may look to reduce these risks by keeping a small position in the stock.
Further given the modest stock liquidity at times, a position in this business would need to be taken with a long term horizon as it can be prone to short term volatility as evidenced in recent months.
Outlook:
BIS have given little forward guidance apart from they expect FY24 to be another positive year despite forementioned headwinds. They have expanded their sales team to help increase sales and market share. This statement has been taken from their 2023 AGM, and is indicating they are focusing on growth through leveraging their existing overseas relationships by continuing to develop and produce quality products.
“All our Joint Ventures made a positive contribution to the business during the year. Indonesia increased in volume, delivering a particularly strong bottom line by also improving sales margins. Thailand also delivered a positive bottom line but was lower than anticipated due to a reduction in project orders. China, despite the slowdown in the overall Chinese economy continues to make a significant contribution to the Bisalloy business and with the removal of travel restrictions, we had the opportunity to visit all our global operations, re-establish relationships and re-engage around growth opportunities and targets.
Over the last 12 months we have placed a much greater focus on how we develop and deliver a stronger and more sustainable business. From a ‘shorter term’ perspective, we have identified some real growth opportunities. These include, new markets, new customers, several new products, ideas and potential for more vertically integrated products, and potential for partnerships for greater global co-operation and reach. We have also identified significant opportunities for our joint ventures/subsidiaries that could provide significant growth opportunities.”
Conclusion:
Any investment in BIS needs to consider the liquidity and ownership risks and needs to be looked at from a long-term point of view. As there are cost headwinds facing them short-term. But given the underlying quality of the business and their competitive advantage in supplying and manufacturing Q&T plate to the growing mining and defence industries, both locally and overseas, they are positioned to benefit from this long-term and create potential value for shareholders.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?