BMW's electrifying performance

BMW Group is the world's largest premium carmaker and saw sales volumes rise 7.9% in 2014 to a record 2.1m units. This was driven by a recovery in European demand and continued strong sales growth in Asia. BMW's recent investment in fuel efficiency and new models suggest that it is well placed to capitalise on the underlying growth drivers in its market.
A premium product can be defined as one that “promises a stronger satisfaction of needs by special characteristics." This translates into consumer desirability and the realisation of a higher sales price in the market place.
BMW Group's three brands: BMW, MINI & Rolls-Royce

Source: BMW Group investor presentation
BMW Group is the largest premium carmaker by volume with its main brand, BMW, experiencing a 9.5% increase in sales to 1.8m in 2014. The small car brand, MINI, saw sales fall by 0.9% in 2014 to 302,183 as a planned model changeover hit demand.
Europe is the key market for BMW Group and saw a 6.4% increase in vehicles sold in 2014 to 914,587. The second largest market, Asia, saw a 13.8% increase in vehicle sales in 2014 to 658,384, and in third place the Americas saw a 4% sales gain to 482,257 units.
BMW's sales by market in 2014: firing on all cylinders

Source: BMW Group investor presentation
BMW Group is clearly currently firing on all cylinders with European demand recovering and Asian demand continuing to grow at a rapid clip. BMW's total vehicle sales in 2014 increased by 7.9% to a record 2.1m units, which is the fifth year of growth and 90% higher than the 1.1m sold in 2003.
Looking at the performance over the financial crisis and sales fell by 14.3% from 1.5m in 2007 to 1.29m in 2009. Cars are consumer discretionary items with purchases deferred in tough economic times and as such car markers are viewed as cyclical stocks.
BMW has seen strong sales growth since 2003

Source: BMW Group investor presentation
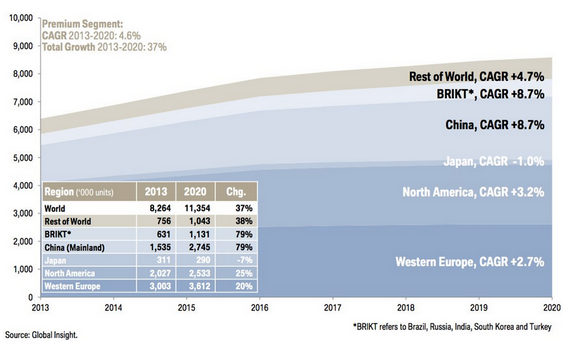
The outlook for continued sales growth at BMW is positive with global demand for premium cars expected to increase by 37% from 8.26m in 2013 to 11.35m in 2020. This represents compound annual growth of 4.6% and reflects growing demand from emerging markets like China.
As countries get wealthier premium cars become a greater proportion of total sales with consumers shifting to higher-end brands. Premium car sales in China and the BRIKIT countries (Brazil, Russia, India, South Korea, Turkey) are therefore expected to increase by 79% from 2013 to 2020.
Global premium car market
Source: BMW Group investor presentation
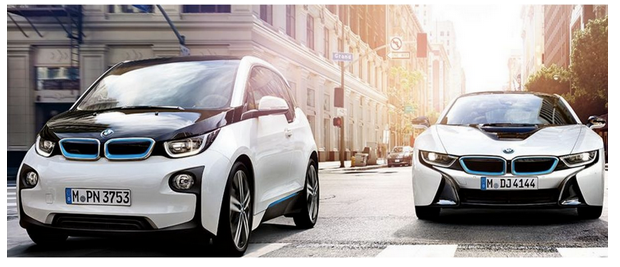
BMW needs to remain competitive to capture this market growth and such has been investing heavily in new models and fuel efficiency. On this front the group recently launched the BMW i family which includes the all-electric BMW i3 and the plug-in hybrid BMW i8.
BMW i sales were only 0.8% of its total BMW vehicle sales in 2014 but the technology will be used to “electrify" the existing model line-up. A plug-in hybrid version of the BMW 3 Series - 26% of BMW brand sales in 2014 – is set to be launched 2016 and will have a 35km purely electric range.
This technology shift should enable BMW to meet the challenge from electric carmaker Tesla and hybrid car markers like Toyota. One edge that BMW currently has is that it is the only firm using strong and lightweight Carbon Fibre Reinforced Polymer (CFRP) in mass-produced vehicles.
The BMW i3 & the BMW i8 both use carbon fibre
Source: BMW Group investor presentation
BMW's outlook for 2015 is for a “solid rise" in vehicle deliveries and revenue, which is expected to translate into a “solid increase" in earning before tax. This follows the 7.9% increase in vehicles sales in 2014 and the 10.3% increase in earnings before tax to €8.7bn.
Looking at recent sales and January and February combined saw a 7.3% increase on a year ago which is a solid start to the current year. BMW has cautioned, though, that sales growth is slowing in China, its single largest country market, to a more moderate pace.
Summary and valuation
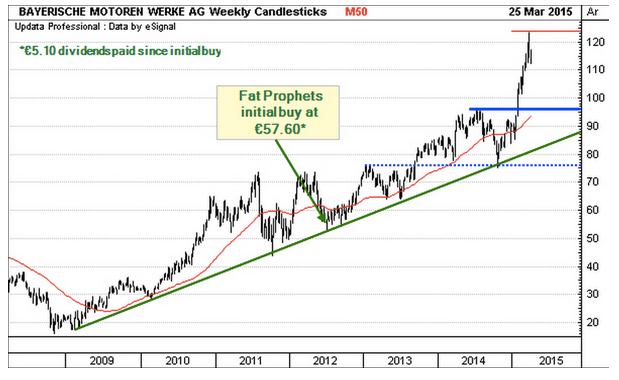
As a carmaker BMW sells consumer discretionary items and as such saw a 14.3% fall in sales at the start of the financial crisis from 2007 to 2009. Profits also fell back and the share price tumbled from a high of over €50 in 2007 to a low of €17.6 in 2009.
However, BMW also offers long-term growth with a focus on premium cars and a strong position in emerging markets like China. This dynamic delivered a 90% increase in BMW Group vehicle sales from 2003 to 2014 and is expected to produce a “solid rise" in vehicle sales in 2015.
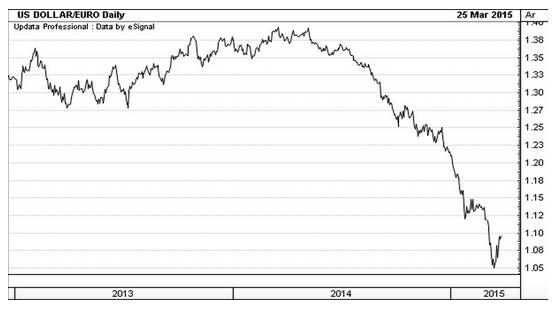
The weak euro will boost BMW's reported euro profits
A strong share price rally for BMW means that the forecast P/E ratio for 2015 is 12.2X with a yield of 2.7% (3X covered). However, looking further out to 2018 and the P/E ratio falls to 10.5X with a forecast yield of 3.8% (2.5X covered by profits).
Whether the valuation is expensive or not depends on where we are in the economic cycle and the prospects for Chinese demand. What is clear, though, is that BMW's investment in electric vehicles and fuel efficiency will help cement its position as the leading premium carmaker.
This report was produced by Fat Prophets Senior Research Analyst, Andrew Latto
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?