Boohoo Results, 12 months to 28 Feb 2021 - new thread, 5 May 2021

Good morning, it's Paul here with a new thread for discussion of results from Boohoo (LON:BOO) (I hold) due out imminently on 5 May 2021.
We decided a little while ago that the market cap of BOO at £4.3bn is much too high to continue discussing it in the Small Cap Value Reports (SCVR). Hence a separate discussion here will avoid cluttering up the SCVR for today, so please keep the discussion of BOO on this separate thread.
Just before the results come out, here's a quick summary of previous guidance, which we can use to measure performance today against:
- Strong peak trading
- 4 months to 31 Dec 2020: 40% revenue growth
- 10 months to 31 Dec 2020: 42% revenue growth
- Guidance for 12 months to 28 Feb 2021: 36-38% (raised from previous range of 28-32%), adj EBITDA margin c.10%
- Medium-term guidance: 25% p.a. revenue growth, and adj EBITDA margin of 10%
Stockopedia shows broker consensus for FY 02/2021 of: 8.47p
Fingers crossed!
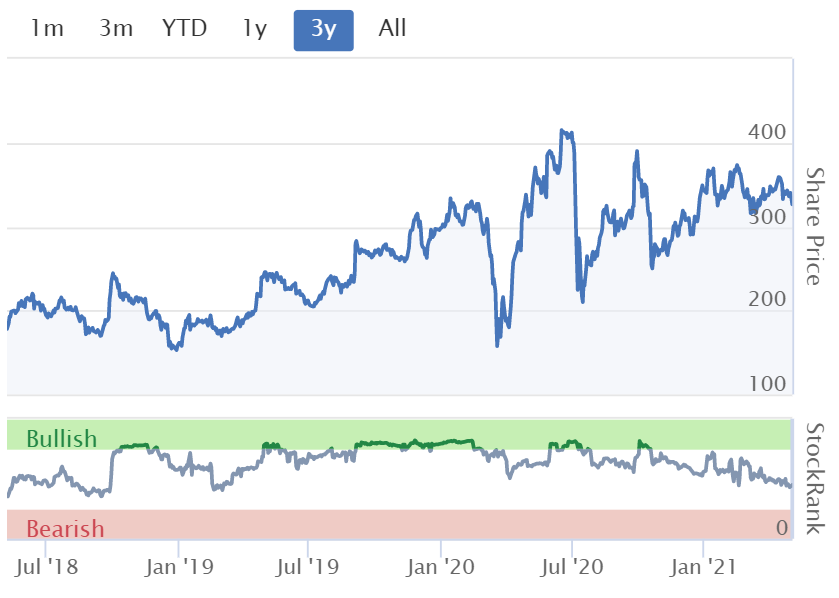
.
Useful links:
Click here for the presentation slide deck
Click here to view webcasts on video recording (select "view online")
Here are my notes from the actual FY 02/2021 results -
- Revenues: up 40% - ahead of guidance of 36-38%
- Adj EBITDA margin of 10.0% in line with guidance
- Adj EPS 8.67p is a beat against broker consensus of 8.47p (2.4% ahead)
- Adj EPS of 8.67p is up 47% on last year
- Strongest growth geographically was in USA, at +65%
New guidance for FY 02/2022: 25% revenue growth (of which 5% from newly-acquired brands) - note that guidance tends to be raised as years progress.
Current trading - trading in first few weeks of new financial year has been “encouraging”
Returns rate - benefit from a lower customer returns rate in FY 02/2021 is expected to “begin to unwind”
Carriage & freight costs - significantly elevated, expected to continue
Lockdowns - mixed effects - some benefits (e.g. lower returns rate, less competition), but core product categories saw “significant declines” (i.e. not selling party/clubwear so much during lockdowns)
Re-opening - already seeing “early benefits” from this, i.e. resumption of sales in party/clubwear
Gross margins in established brands expected to be maintained
Adj EBITDA guidance: 9.5% to 10.0%, slightly lower than previous 10% guidance, due to investment required in new brands
Seasonality - expect a return to H2 weighting for adj EBITDA (up against strong H1 comparatives)
Medium term guidance - unchanged, at 25% p.a. revenue growth, and adj EBITDA margin of 10.0%
Newly acquired brands - already seeing the early rewards from their growth
.
My opinion - this all looks good to me. BOO tends to guide cautiously, then upgrade expectations as the year progresses.
It’s clear that lockdowns were a mixture of positive & negatives. Also note that BOO actually continued to trade very well when the re-opening of physical retail happened last summer. Plus there’s less competition on physical High Streets now.
No sign of margins eroding, despite extra costs of cleaning up the Leicester supply chain. Gross margin rose slightly, from 54.0% to 54.2%. I think that’s because Leicester was used for speed, and wasn’t low cost. So margins could go up in future, as more product is imported from Asia.
Broker consensus is currently 10.7p EPS for FY 02/2022. BOO normally comfortably beats forecasts, which are raised throughout the year. I think the new brands could begin to really kick in later this year, and beyond. Hence I’m working on the assumption 12p+ is more likely for the current year. At 326p per share, the PER would be 27 times - which is a bargain, for such a strongly growing business, with almost unlimited growth runway internationally, and with multiple brands.
That doesn’t even factor in future years’ growth. I remain of the view that BOO shares are the ultimate “coffee can” shares, to hold forever. This is likely to be a very much larger business in a few years’ time.
I don't know what the short term share price will do - we've seen that it's extremely volatile & unpredictable, hence why I ignore it.
Broker update - a note from Zeus Capital has just hit my inbox, via Research Tree. This starkly demonstrates that BOO shares are priced completely wrong, given the growth track record & prospects. Consider these latest forecasts:
FY 02/2022: Revenues £2,194m, Adj PBT £185m, Adj diluted EPS 11.81p (PER of 26.8, at 316p per share)
FY 02/2023: Revenues £2,741m, Adj PBT £240m, Adj diluted EPS 15.31p (PER of 20.6, at 316p per share)
How does that valuation make sense? It's ludicrously cheap for a group with such a strong growth record. I think the market is offering us a wonderful bargain today. Obviously DYOR, as usual.
.
My notes from this morning's webinar
A reader rather stole my thunder on this, by making the main points in the comments below. But fair do's, he got there first! I'm sitting outside this afternoon, so to keep my fingers warm, will type up my notes from the webinar. NB this is not verbatim, it's just my recollection of the points which seemed most important to me, and my impressions/views of what was said.
Opening remarks from Mahmud Kamani
CEO John Lyttle continued, focusing heavily on ESG - 20 of the 34 Levitt Report recommendations have already been implemented. The rest will be implemented by Sept 2021. My view - BOO's comprehensive response to ESG is way more than just green-washing. They're totally serious about putting things right in the supply chain & wider environmental issues, and turning this into a positive.
20% of BooHooMan product will be made from recycled (or similar) materials by end of this year. Other brands following.
Leicester factory being set up by BOO will make 20-25k garments per week (not much, in the overall group total), and be a base for training, compliance, etc.
Revenues have grown 15 times since 2014, and EBITDA up 10x in same period - remarkable growth.
Social media - now have 47 million followers. Created 4,500 jobs.
In last 2 years, gone from 4 brands, to 13. Much wider addressable markets & demographics now.
USA: 65% revenue growth in last year, but <1% of addressable online market.
Acquisitions of new brands - £250m invested this year. Acquire & integrate quickly.
PrettyLittleThing - full acquisition of minority interest, has created shareholder value for BOO group shareholders.
Debenhams - beauty, sportswear, homewares, new markets. 90% brand recognition amongst public. Already a UK top 10 eCommerce fashion website. 4% of fashion market in UK pre covid. 20% market share in prestige beauty products. Launched new beauty website last week. Signed up "pretty much all" major beauty brands. Aim to create UK's largest marketplace. "Headless front end" - phrase used several times, I don't know what this term means. Companies should try to void using jargon that may not be familiar to the audience.
Warehouse capacity - Wellingborough & Daventry warehouse acquisitions, Also automating existing warehouses.
Lots going on to improve IT.
Staff survey - 81% feel inspired & respected by their manager(s). 75% said would recommend to friends & family working at Boohoo. Not bad at all, but scope to improve further I think. All employees given £3,600 in free shares (did I hear that right? Not sure. Very good, if correct).
Test & repeat business model emphasised as a key advantage, especially when covid caused major shift in demand from party, to casualwear - able to respond very quickly
EPS benefitted from acquisition of minority interest in PrettyLittleThing
USA - all brands showing strong growth
Brexit - operations uninterrupted, but some extra duty costs - high single digit £m's. Can mitigate this with price rises, efficiencies.
Marketing costs struck me as very high, at 9.1% of revenues (down slightly from 9.5% LY). This gives BOO tremendous flexibility, since marketing is completely variable - a key advantage of online businesses.
Distribution costs high, at 24.2% of revenues (LY: 22.5%)
Other admin costs fell, to 12.4% of revenues (LY: 13.3%) - operating leverage from growth, and offset some of the rise in distribution costs
Loyal customers - shown a year-by-year customer cohorts diagram, showing impressive customer retention & repeat orders
EBITDA margin of 10% achieved despite cost headwinds & investment in new brands
Carol then took over from Neil Catto (CFO). I like her presentations, as she's steeped in product & branding, so has a different emphasis.
Debenhams brand - becoming a digital department store, growth opportunity
Showed a diagram of the different brands, covering a range of markets & demographics
"Our ambition for Debenhams is just huge"
Lockdown - turned marketing upside down, as party, going out images & products not relevant
Brand collaborators - over 100 of them, really important. PLT: Molly May is very good. Rachel Stevens has been a "huge success" for Oasis brand.
Huge shift in how people dress - no nights out, no dressing up, no formalwear. - these categories fell off a cliff. Growth came from new areas, e.g. Athleisure., quilted jackets, knitwear, leather, which have all been good. This brought it home to me, that BOO has not had an easy time, it's had to be highly flexible to do well in lockdown, adapting fast. So this strong performance was not automatic, just because physical stores had to close.
Dressing up is now returning, as a product area
Covid/lockdown has demonstrated how fragile the fashion sector is. Hence test & repeat is so key - adapt fast.
Karen Millen brand - aimed at 20-40 yo, career-minded women. Launched 18 months ago under BOO. 5k styles now. Global brand. Sales have started in the USA now - early days.
Coast brand - also 18 months under BOO ownership. Occasionwear. Now up to 4k styles for sale.
Warehouse - revived brand. 25+ customer age, trend-led product. Influencers are important.
Oasis - 30-something women. Ranges received well. Disrupting the middle market.
ESG - social media influencers are spreading the new sustainability agenda - important point, I think BOO is really serious about ESG, and wants to turn this previous negative into a future positive. I wonder if/when ESG funds might want to buy back in?
Burton - first move into formal & smart casual menswear
BOO is keeping brands alive & making them relevant again
Brands are at different stages, depending on when they were acquired - showed a timeline for each, from acquisition, sorting out, greatly expanding product ranges, online marketing, then international launch & expansion
Debenhams - successful launch of new website. "Going to be enormous in future". Such an exciting opportunity for the team. New product categories, plus came with its own brands, such as Maine, Principles, Red Herring, and others.
Beauty - millions of existing DEB customers. Launched last week.
Overall demographic - BOO group used to be 16-24. Now it's 16-50+,ages sizes 4-24, doing petite, curves, and tall. Big ambitions.
Then it moved to Q&A, but unfortunately my sky broadband conked out again, so I was cut off.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
119 comments
Hello all,
Holders of Boohoo may be interested in this write up of a potential competitor, Shein.
https://www.notboring.co/p/she...
Sounds like a similar model to Boohoo and potentially capturing some of the US market?
https://homeofdirectcommerce.com/boohoo-launches-new-dorothy-perkins-wallis-and-burton-websites/
Sounds good.... but I'm not a computer guy.
just after viewing the results presentation , all looks good until I see the Mahmud Kamani ficking through his phone while his management is rolling out the results .... it doesn't look good .... was he checking the share price ? ...
mind you I can't knock him for the success of boohoo . His certainly has the nack of picking a good management team .
they also mention that the next warehouse will be in the US and more news on that will come later . The US sales could easy exceed the UK figures in short few years in my opinion
Some great comments on here. I love reading Paul's take on Boohoo as well as all the comments. Thank you for all your contributions.
Just checked out the Debenhams website and it looks really cool (probably not cool to say cool anymore but hey ho)
Being an ex Debenhams customer, what did disappoint me was the lack of size for jeans available. In the style I chose at random, Mantaray, only 38 or 40 available, neither any good for me. I need somewhere to buy jeans and it will either be the web site or M&S, and at the moment, I am now down to one choice.
For a fast fashion chain, I am surprised they do not have a larger range of sizes, and if they don't sort it out soon, then I probably will not check back too often.
The web site, for me, is a bit "all talk and no trousers (or jeans)", have they launched it too quickly, or at least the number of items.
No wishing to teach you to suck eggs, but:
debenhams.com home page. Hover over men, click "jeans", filter for 36R (my size yours may be different), 79 options appear.
Likewise and not really wishing to take business away from Boohoo (LON:BOO) (which I hold) but did you know that on Amazon you can buy jeans and they take them up to the precise length that you want?
I discovered this a few years ago after our sewing machine packed up (I sabotaged it). Even better, when I came to reorder a couple of years later their system remembered what length I required. Now, that's customer service.
Amazon will never crack fashion, in my view. It's too complex, and products/brands are not generic, so can't just be copied & sold in scale. For example, each brand has its own specific fit. Hence I know when I order Large in Next & Joules, it will probably fit me like a glove. Customers get to know their favourite brands, then stay loyal to that brand.
I would buy generic household items from Amazon, but never fashion items. If Amazon tackled this area, they would make a complete hash of it, in my view. Hundreds of thousands of SKUs, etc, 40-50% customer returns - imagine the logistics of doing this! They'll leave well alone, if they have any sense. Leave it to the experts.
Regards, Paul.
Ah but I'm not a fashionista.
I dare say I'll still be wearing Levi 501s when they cart me off.
Paul,
Are you really saying that Amazon aren't able to handle lots of SKU's? I rather thought that was their raison d'etre.
They have more than 12 million SKU's of their own, excluding Market Place sellers which take them into the hundreds of millions. Amazon US has 33 million SKU's in the clothing, shoes, and jewellery category.
They have dozens of their own fashion brands already - I count more than 50 different clothing brands among their 80 private labels- see this list
Then there's their patent for on-demand apparel manufacturing.
Just saved £20 using Amazon over the brands own website for a martial arts kimono. Not high fashion but for everything else maybe. And due this week not sometime in the distant future.
Sounds like a lot of effort for a scruffy pair of jeans. Each to their own.
I think you have to accept this is a soft opening. They are ramping up products on a daily basis. I fully expect how the site looks and it’s range will be much improved by the summer.
GloucesterBob,
BOO relaunched the Debenhams website literally a few days ago!
They'll be adding many new styles on a daily basis, but it's a work in progress. Most important thing was, at the start of the Q&A, before I got cut off by my useless broadband provider, a couple of analysts asked them how the product ranges on the new DEB website would be "ready for peak"? By which I think they mean peak trading Oct-Dec 2021, and the replies from BOO sounded pretty confident.
I was less keen on Neil Catto (CFO) answer to the analyst question about how many of the 19 million Debenhams customers are BOO expecting to keep? "We want to retain them all. The sky's the limit!" - that doesn't cut the mustard, and detracted from the presentation. Investors want specifics, not daft stuff like that.
Regards, Paul.
Why don't you think keeping them all is a possibility? Their ambition is to make Debenhams a market place, so even if a niche area of the market isn't covered by Boo brands hopefully "someone" will be there for all those customers.
It may have come across a bit naff, but I think they genuinely believe they can grow so eventually everyone will be looking at one of their portals occasionally.
My customer service experience with Boohoo (LON:BOO) hasn't been great and I won't choose its brands. Considering Amazon's obsession with customers, Boohoo (LON:BOO) has lots to learn. Investors will eventually notice.
Thank you Paul for going to such lengths with your notes and links. I have a few observations (as a hard nose retailer) regarding Boohoo (LON:BOO) (and yes, I hold!):
Rinse and Repeat - how will that work with non-textile homewares, lead times are generally longer in this category?
Customer subscriber list - Debenhams including beauty customer base, not as big as one might think as email subscribers have to opt back in, (emails sent out a couple of weeks ago, what's the take up going to be, when the EU'd new data protection rules launched a couple of years ago many online retailers lost 70-90% of their base . This is a similar exercise.
Headless - already explained by others previously headless commerce is having a different system powering the operational back end from the software powering the front end (customer facing website). That's good because you'd want the Debenhams back end to be stronger than the truly appalling website launched last month. I'm sure that will get better and can only believe it's a holding site so they can trade now pending a proper site build. Look for example at the search filter options on category pages, the gallery image views, product image magnification and product information - truly dreadful and not even matching stand alone sites in the Boohoo stable - many small eCommerce retailers doing less than a £1m pa present much better than this.
All that said I think the opportunity is huge as Paul and others have described. The threat is other multi-brand platforms, ASOS, Next, even M&S and Amazon, and so the big questionmark is around execution with such rapid expansion in what is going to become a very competitive marketplace. In particular I'm concerned about how Boohoo will retain the Debenhams customer base, (of course they'll add new) and how they will shift age demographic, the Debenhams customer is definitely a bit older than Boohoo's traditional profile, or maybe that's not the idea at all and they want to lower that traditional older age profile - that is a big execution risk.
"how they will shift age demographic, the Debenhams customer is definitely a bit older than Boohoo's traditional profile"
But the stated ambition is never to merge Debenhams and Boohoo (Debenhoo? Boohams?) into one platform, one brand.
The ambition is to build a "conglomerate" of brands. Like FMCGs do with multiple brands, different demographics, customer segments, etc.
Hey guys, just a thought as a very small holder, aren't some of you forgetting one of the very first rules of investing "Don't get emotionally involved with your investment". There does seem a bit of the "Its the elite doing us down" syndrome that drives so much these days in some of the comments.
I note and do agree with your point.
I would say however that some of us are also interested in politics and regardless of the strengths and weaknesses of Boohoo (LON:BOO) notice some quite hostile arrogance towards the company, it’s products and its customers from both politicians and media...perhaps symptomatic of the drubbing the Labour Party are getting today.
ive clearly said too much.
Ha! You think you've got it tough.
I've been accused of being sartorially challenged.
I've fallen in love with one thing about Boohoo (LON:BOO) - the numbers.
See the historic EPS below. I've put in yellow highlighter what I think could be possible once DEB kicks in (based loosely on Zeus forecasts, plus a bit more on top). This is a no-brainer. Downside risk? An online sales tax, and possible windfall tax, which would undoubtedly be a bump in the road, but as a coffee can stock that doesn't matter to me. It might matter to you, your choice.
I am a holder of Boohoo and happy to remain a holder based on recent announcement. When I purchase shares for my SIPP as a general rule I will look for good quality measures such as ROCE and a strong trend in sales and earnings growth. I then sense check this using the stock valuation tools by performing a discounted cashflow calculation on a series of assumptions.
Based on latest results I used a FCF of £110m (Excluded acquisitions). I then plugged in 2 years of growth at 25%, next 2 at 20%, next two at 15% and two years at 10% with the remainder at 5%. I used a 10% discount rate. The calculations gave a current share price of £4.11 versus £3.20, hence a potential upside of 28%. I have also used stronger growth assumptions which give a price in excess of £6.00.
I find there are few shares that give a positives value when I use conservative numbers in the DCF calculation.
No one knows what the future holds and there is execution risks on the acquisitions, but I remain happy to hold while the cashflows emerge and hopefully the institutions feel they find a reason to buy again.
I will top-slice at £4.00 and the rest stay in the coffee can segment of the SIPP.
Good luck to holders and thank you to Paul for his retail insights.
Greyster.
The Times is off my shopping list.
The guy has history - criticised Reach for a minimal share buy-back a few years back when it should be 100% focused on paying pensions to journalists - might have been a conflict of interest there?!
Continually ask myself - where is local law enforcement in this? Yes this problem has been known in Leicester - FOR DECADES. They've never done anything about it and now - oh great - a major company has got slightly embroiled so we can pass all the blame onto them. But boohoo can't enforce criminal law against people for this wrong-doing. Stinks !
Rant over - loaded up the truck today as it will recover.
Continually ask myself - where is local law enforcement in this? Yes this problem has been known in Leicester - FOR DECADES.
It's also been known at national level, so there's no excuse for either government or retailers. The main reason given for a failure to investigate and enforce is the decision by Chris Grayling in 2011 to cut the number of proactive investigations by the HSE. As Grayling said:
“If we try to legislate out all risk, we will lose jobs to other places.”
Or, in other words, we'll turn a blind eye. At least until there's a global pandemic and people start noticing (and dying). Without proactive investigations it's pretty much impossible to catch illegality in action.
This is what Next's head of ethical compliance said about it in 2019:
Grayer said it was a sad irony that the risk of worker exploitation is likely to be as high in Leicester as in Turkey or Bangladesh. “We are a Leicester-based business, and we are now very limited as to where we can source products and the level of business that we can place in the region, with the assurance of compliance to our standards; this is because of the exploitation and the incorrect standards that are taking place.
“If you see a dress advertised for £12 as made in the UK, do the maths: it’s impossible for the workers to have been paid the legal minimum wage. Fast fashion is growing at a speed that doesn’t necessarily include the investment into the quality and compliance side of the business.”
https://www.reutersevents.com/...
timarr
RBC CUTS BOOHOO PRICE TARGET TO 380 (420) PENCE - 'SECTOR PERFORM'
What am I missing here? I fear I’ve drunk the KoolAid but I’m struggling to understand what a downgrade might be based on. Cost headwinds?
I noticed there is a £23m in claims provisions recorded in the accounts this year. The narrative says ' claims represent the estimate of claims against the group that are expected to settle in the period within nine to twelve months after the year end'.
When questioned on it during the results presentation, Management (CFO) said they related to a variety of claims which are entirely expected for a large growing business.
Seems a little odd for all of these claims to have arisen this year and the amounts are substantial. I would have thought it warranted more explanation given the potential outflow and possible impact on the business.
Perhaps I'm being overly skeptical. Do others have a view on whether these could be concerning?
A little; without any further information or context it’s not great. Hopefully that will come out in the annual report.
Typical negative comment by Ben Wallace in the Editorial page of the DT. He is demanding that the Chairman steps down and is replaced by a fit and proper figure !! Just feel there is an Agenda here with racial undertones . But as Paul has mentioned this is a long term hold so such bizarre comments are best ignored , and significant drops in the share price give a buying opportunity. Many of you will think I am nuts to have as much as 27% of my portfolio represented by Boohoo, but I am very comfortable with this.
27%! Phew! Re the racism suggestion, yes to me it certainly has felt that way with regards to the often quite personal attacks on the Chairman.
Perhaps I should explain that is 27% of my self managed portfolio. I do have a more conservative portfolio managed by professionals. Of course my portfolio has,on paper,substantially outperformed the professional one ;)
I agree that there are racial overtones and bias (unconscious or not) in Ben Wallace's comments that is sad and unfortunate (mostly for him and the opportunity cost he suffers as a consequence - I'm not just talking about Boohoo shares either). I am happy to take advantage of this ignorance and buy this high quality stock and hold for many years. This company would benefit greatly from a USA listing and an international shareholder base, and I'm sure it will happen.
https://www.thetimes.co.uk/art...
Hi Paul
By way of contrast to Boohoo (LON:BOO) with its UK and push into US. Some might be interested by Zalando's update this morning.
£ZAL (Zalando) the German online fashion company which sells across Europe (Eurozone mostly)(I hold).
UPDATE 1-Zalando to add five warehouses as ecommerce booms
* Q1 EBIT 93.3 mln vs 99 mln loss in 2020
* 2021 revenue growth outlook raised to 26-31%, from 24-29%
* 2021 EBIT outlook raised to 400-475 mln euros
(Adds details, background)
BERLIN, May 6 - German online fashion retailer
Zalando ZALG.DE said on Thursday it will add another five
warehouses to its network by 2023 as it reported
stronger-than-expected first-quarter sales and profits and
raised its outlook again for the full year.
Zalando said sales rose 47% to 2.24 billion euros ($2.69
billion), while operating profit came in at 93.3 million, helped
by a continued lower return rate - a trend that started when
shoppers were confined to home during coronavirus lockdowns.
It said it recorded its strongest customer growth in eight
years, to reach 41.8 million active customers.
To help it reach its ambition to capture more than 10% of
the European fashion market, Zalando said two new warehouses in
Rotterdam and Madrid would go live this year and it would start
building three more in France, Germany and Poland. Zalando
already has 10 fulfillment centres around Europe.
Zalando said late on Wednesday that it now expects revenues
to grow 26-31% in 2021, up from a previous forecast for 24-29%,
and it expects operating profit of 400-475 million, up from a
previous 350-425 million.
It also launched a share buy-back programme of up to 200
million euros, starting on May 7.
($1 = 0.8331 euros)
Regards
Howard
Thanks for this.
Just to add that Zalando oddly does not have a UK distribution centre, which I found most interesting given its size.
Cheers
No forgiveness from the Times.
To summarise... ...Even if you do everything perfectly re ESG, you should change your Chairperson and probably flog yourself unconscious in Leicester town centre... ...okay I exaggerate slightly.
"Frock tactics don’t work at Boohoo"
https://www.thetimes.co.uk/article/frock-tactics-don-t-work-at-boohoo-5jxlk8qdx?shareToken=686081a5745b96cf6c7468fa5c1b9be8
I believe that there's a strong racial and cultural element to the way that Boohoo will be criticised when others aren't. This seems quite likely to keep its rating lower than it ought to be for some time.
There's a disdain for the culture of people who buy from Boohoo, a disdain for the culture of people who make them, a disdain for the culture around the sales methods, a disdain for the lifestyle photos of the founders family and starting to look for a dislike of him. It's the other end of the spectrum from middle class metropolitan woke.
I'm sure Next will be feted. Though the case against the interest rate exploitation of its credit customers isn't so different.
It's all noise to me, given sufficient time these things change. I hold, and will continue to hold. (I hold Next too - my only retailers.)
I can’t pick up the article from the code, but get the idea. There is just a weird smugness going on that stops at our shores. So any issue re low pay, now resolved by boohoo, is modern day slavery, but any other clothing company paying pennies per hour in foreign countries...,nah, no issue. I find that really strange.
Boohoo is mostly not engaged with upper middle class clothing...much of the media attitudes appear to be arrogant disparaging of either the young or of working class/lower middle class fashion and buying tastes (as we know from the Labour Party RIP) that has become an acceptable attitude amongst the chattering classes. Meanwhile boohoo goes from strength to strength
My apologies, I just missed the one hour cut off for correcting my post. I posted the correct link at 08:04. Here it is again...
"Frock tactics don’t work at Boohoo"
https://www.thetimes.co.uk/art...
i haven’t seen anything on the US investigation into the workers issues. Has this gone away now? This is why I sold out and is putting me off buying back until it’s resolved
what was this? I dont recall a Us investigation into workers issues.
It was a non story that Sky made the headline of the day back in March. Some legal advocacy organisation trying to make a name for themselves by trying to set something up about ‘slavery’ in Leicester with the Americans...who promptly filed it in the bin it appears.
It is something to watch out for as much of the media inflate, conflate or just endlessly repeat the issues that the company had, to some extent, already identified prior to media involvement. What they tend to report on very little, is the effort being undertaken by the firm to not just resolve some dodgy supplier issues, but to fundamentally revise the business’s approach to ESG in a route and branch manner that is very impressive and will have far reaching positive consequences. The bad news was over a few months, this good news will roll on for many years.
When I started following Boohoo (LON:BOO) I could not have imagined such an impressive response to last summer’s moral panic, I have been involved in reputational / business process and ethics turnarounds, and this has already been a superb example of how to do it, with a lot more more to come...(love boohooMan going 20% recycled materials).
As you may gather, I hold.
I am in exactly the same position as you.
Last year when Liberty filed a petition against a palm oil company it took 5 months for the investigation to happen, after which the import ban was imposed.
However the fact that the issue wasn't mentioned at all on the boo analyst call makes me think maybe Martin is right and it's just gone away.
The closest boo got to mentioning it in the finals was to say 'The group has been working .... with the .... GLAA, who, ...., confirmed ..... no evidence to support claims of modern-day slavery in the boohoo supply chain.' Maybe that's enough to forestall any CBP investigation?
Personally I'm going to try to wait that full 5 months before buying back in.
Just to be clear, although I see myself as an ethical investor, I have never had any doubts about Boohoo's credentials in this area. Even before the Sunday Times investigation you could see from boo's Glassdoor reviews that they are a relatively good employer.
I'm just worried about the political risk.
Regarding the phrase "Headless Front End", I believe this is to do with the website development and e-commerce.
I'm by no means an IT Boffin, but my understanding from a bit of googling, is that "Headless" means that the backend of the website (stock/ordering/customer management system etc.) is de-coupled from the consumer facing front end. This helps free up the 'design' people to create a nice looking and well functioning website without having to also be experts in the more technical back end programming.
Headless Architecture: What It Is and Why It Is So Popular? | IT Consultis (it-consultis.com)
What Are The Benefits of a Headless Architecture? | IT Consultis (it-consultis.com)
Disclaimer, no background in IT - happy to be corrected by anybody knowledgeable on the subject.
Headless Front End is really just a bit of IT jargon for the website implementation. It is considered good practice.
If they have designed their systems well it should be easy for them to change the websites, or to create new websites like Debenhams that offer the same items that they have on the other websites without affecting the other websites.
For instance Debenhams can display a Karen Millen garment and get all the information they need about that garment and display it in a different way to how Karen Millen display it without having to ask Karen Millen to change anything.
A bad design would be a system where the Debenhams website is dependent on the Karen Millen website, the Boohoo website, the Oasis website etc and the Debenhams website breaks if any one of the other websites decide to change something. Or a system where none of the other Boohoo brands can change their website without checking with Debenhams and all the other brands that they change they are making isn't going to cause problems for the other brands.
So they've just put an SDK in front of their database?
While we’re at it, how about a spot of tasseography too .......
Gus.
What ever floats your tea leaf.
I took a straw poll amongst my daughter and her friends. One actress, one estate agent, 2 uni students in their third year. Only one was aware of the ESG issues, all 4 had Boohoo items in their wardrobe , like the product lines and would purchase again.
Small sample I know, but core market. None of them were aware that the different brands all belonged to Boo.
alexdonnelly - just Create Account and await bombardment of offers/emails etc.:-
https://www.debenhams.com/sign-in
I think results were very good
However the Debenhams website is nothing special. Yes the clothes are there but in home only bedding and soft furnishings. Big miss is I see no where to sign up to the mailing list. If it is there is not easy to see it
Paul maybe you could mention it to management about the mailing list
Why for now does Stockopedia say:-
"Falling Star"
Q 96 - yes very good indeed
V 28
M 21
SR 45
Yield Nil Point
PE 30.4
Why is Stockopedia still not yet showing the +80 or +90 StockRank that StockRank theory associates with the biggest likelihood of success?
(For what I hold, my SR's are 99, 99, 98, 96, 86, 76.)
Surely SR and Magic Formula should be sign posting £BOO's trajectory?
* I can totally appreciate that if you're in Boohoo (LON:BOO) @ 260p or less, then your position is completely different then if you have no base established.
Also technically looks vulnerable to down draft, and volume on these last 2 down days is much higher than average............25% higher than average volume day. Those are not bullish signs at least short term, so some large players must be exiting here.
It's a Falling Star because it has high quality, low value and low momentum.
Low value rank because the value ratios are high. Low momentum rank because the share price has been underperforming. Average stockrank because it has low value and momentum ranks.
It doesn't make the Stockopedia Magic Formula screen because it isn't in the top 30 stocks sorted by Magic Formula Score Descending, but all the other rules are passed.
It may well go on to be a good investment, but at this point it isn't the sort of investment that the stockranks are going to pick up. It is unlikely to become a value share unless the share price collapses, the momentum rank will only improve if the share price improves.
Thank you Syrio, Most helpful.
I have read the book that Paul talks about '100 Baggers' by Christopher Mayer, and I have decided to try and apply those principles in the book to my Boohoo holding - so I am going to tuck away my 15% of portfolio holding, and have a look at it in 5 years time !
I first bought in between 2014 to 2015 at several prices, and as low as 25p, but I started top slicing from 118p several times and was all out at 251p in 2017.
I then felt sad and really missed my Boohoo shares !
So I am thrilled that we have had this wonderful opportunity in 2020 and now!, to get back into this fantastic company, which is now more grown up and more ambitious than ever to become a massive global leader in what it does so well.
I guess this from the Investors Chronicle explains the weakness in todays share price ... "
Closer to home, a big lockdown winner has been Boohoo, which reported a 41 per cent increase in sales in its annual results this morning, spurred by demand for ‘athleisure’, or ‘lockdown outfits’. Boohoo’s strong online presence has served it well during the pandemic as retail shifts online. But questions still circle around the company’s environmental and social credentials after last year’s scandal and there remains uncertainty about the extent to which the company's recent acquisitions can be properly integrated.
Judging by the 41% growth into a headwind of ESG concerns - it does not seem BOO's core customers care much about such issues and or believe in the anti-BOO press.
Love the IC - still can't get myself to cancel my subscription.
The IC will still be telling all and sundry in 10 years time that Boohoo (LON:BOO) has a ESG problem - its an elephant - good memory but little brain.
Phil
Yes. I am a subscriber at the moment and think that IC (like its sister the FT) are clueless when it comes Boohoo.
Not because of Boohoo (LON:BOO) both subs will lapse this year.
The last sentence nails it on the head for me.
Adding 25% growth in a year to a £1bn+ revenue business, after a year of 40%+ growth, would already be an ambitious task for any company.
Yet alone trying to onboard and integrate Debenhams and the Arcadia brands bought.
Along with a year of transforming the supply chain.
For me, either the revenue growth target will be missed this year. Or it will be met, but margins will suffer due to lower costs / extra promos to drive that top-line.
Either way, a miss of revenues or margins this year will probably lead to a re-rating downwards to 20x PE for FY21. In a downside scenario, I assume a 10% miss to the 10.7p EPS (so 9.6p), and the market ascribing a 20x valuation in panic, so my downside scenario share price of 192p. A 40% loss from the current price.
Hi
The link on the Boohoo web site for the recording of the webinar:
https://webcasting.buchanan.uk...
Is not working.
Does anybody have the correct link.
Very frustrating and basic error.
Has anyone managed to view the Boohoo (LON:BOO) (I hold) investor presentation webinar and if so what link did they use please - I agree Michael - most frustrating.
Cant find the webinar, but here is a FY21 results presentation in PDF format.
Very glossy and some good pointers to the future around ESG concerns
https://www.boohooplc.com/site...
Not sure if you're still unable to watch, but I just tried the link above and worked fine for me using MS Edge browser.
the capital H in the title is triggering me hard
Boohoo (LON:BOO) (no position)
It's good that revenue are going up there, but that doesn't really matter if there are higher shipping costs further down the P&L.
One thought on Boohoo (LON:BOO) is that the ongoing share price downward pressure might be prompted by a bit of short selling by the usual hedge fund culprits (pending release of a carefully researched, independently minded hatchet job on the company). However, no evidence of this - current short positions are just over 1%.
Gus.
I think it’s just sentiment. Lots of stale bulls.
I also wouldn’t be surprised if there’s someone building a position in the background but I have no evidence for this - price action just doesn’t make sense based on forecast growth and the plummeting PE.
And in fact, by Friday the shorts had gone below the 0.5% declarable. So they clearly saw the results as being decent relative to share price, and decreased their shorts (whether they completely closed them, we will not know).
At 11.00, I have listened to the webinar and I have read the comments so far. Thanks for all contributions which always broadens ones thinking. I have a few thoughts which don't seem to have had much coverage here.
The first is, for me, the management in the webinar focused really very heavily on ESG
factors and indirectly in countering the what has been intense criticism from the media and others. Paul has said previously several times that this is what happens in the rag trade. Well, that is as maybe, but he has also said that Boohoo (LON:BOO) is carrying the load for all of them. What about £ASOS or even the Persil-bright-white Next (LON:NXT)?
Methinks Boohoo (LON:BOO) management are clearing up the bad history as much as they can, and at the same time, still demonstrating by these historical figures this will not prevent them running an extremely successful business. So lets not go running away with disappointment in a lack of 'we can beat that' forecasts. Lets be happy with just steady as she goes for the moment. The beloved 25%/10% is maintained.
In truth, in what has been a constant attack and a constant series of responses which must have taken up huge quantities of management time, the business not only grinds on at a fast pace, but also acquires and develops a major number of additional brands too. I was absolutely gob-smacked when Carol Kane talked about the expansion during 2020 of the lines at 2019 acquired brands Karen Millen and Coast. How they manage it all, I literally do not know!
So for me they are cleaning up their act, and in all of this one figure really lifted me, and has not been mentioned here at all. Share based payments which were earned by every member of staff regardless of level equated to £3,600 last year. That's £70 per week, not far short of statutory sick pay, though contributors here have probably never had to exist on that. I would guess that every John Lewis 'partner' would have been pleased to receive that this last year.
The second is that they truly are going into uncharted territory. Year 2 summer of living with C 19 - very tough comparatives as the FD said; how will people be allocating their monies between Boohoo (LON:BOO) offerings and holidays etc?; how will people want to shop in future?; what will be the effects of high distribution costs every company is facing, and how long with the are going to continue? Lets be a bit cautious, especially for the figures over the next 6-9 months.
One very exciting feature for me is Debenhams Department Store. I didnt know until recently that formerly Debs had 15m online customers if remember correctly. I didnt know they had 1.6m Beauty Club members. What an opportunity, and its already begun in April with a soft sell which Carol K said would be ramped up in the autumn. During the webinar I drifted onto the website, and it is already up and running with terrific brands as well as a good selection of Boohoo (LON:BOO) own/newly acquired other brands.
It really is an exciting time, but the next year will be very important - on the ESG front (and not just in Leicester; the CEO mentioned lots of other ESG tracks they are following too), the integration of the newly acquired brands; and especially the Debenhams Department Store opportunity. In 12 months time, we could be looking at a very different SP.
very well said. I personally couldn't care less about the current market price - my thinking with every company I purchase is to hold forever if I can - obviously some businesses don't execute to plan. This always brings to mind a quote which I think was from Benjamin Graham or it could have been Warren Buffet or Charlie Munger - memory doesn't serve me well. The market is a voting machine in the short term but a weighing machine in the long term. Boohoo may not have the votes at the moment, but it sure (at least for me) has the weight.
Great post. thank you.
I hold.
Excellent Post - I hold.
I've just been on the BooHoo (I hold) analyst webinar, and taken 2 pages of A4 notes. Lots of interesting points. Will type them up here later, got to do some small caps next, or there will be complaints!!! Key point is that they see tremendous growth potential from Debenhams digital department store, which has already launched, and lots of new product categories coming on stream before peak trading in the autumn. All sounds really exciting. I don't think the stock market has realised how much potential growth there is from all these new product categories such as beauty (where DEBs was no.1 or 2), homewares, footwear, sportswear, etc, and a much broader demographic.
More later.
Regards, Paul.
My thoughts exactly Paul. I have been following the Debenhams website since it was set up (my wife by coincidence bought some stuff from what it turned out was the last day of the old Debenhams website, she went on the next day and was shocked at how slick the website had become...this was when Boohoo (LON:BOO) took it over) almost day by day, new products and categories are being added, including new markets for Boohoo (LON:BOO) owned brands and products like women’s underwear, household goods, and children’s clothing and new retail of other companies’ products, particularly perfume, make up and grooming.
The range of products they are now making is growing rapidly and their range of products is huge. If you have not looked, go explore the Debenhams website, many new (or previous Debenhams brands) are popping up like ‘Glamorous’ for lingerie, ‘Mantaray’ for older men and women’s clothes (you can tell that, as there are no male models with tattoos or piercings) and very cute ‘Blue Zoo’ for kids clothing.
Marketing will only get going in serious manner when the old shops close in the next two weeks. But I expect to see a lot more of Debenhams as the year wears on.
The £83m revenue estimate for the acquired brands seems rather modest.
Overall, this now sounds like a more mature and diversified business growing at over 25% pa...what’s not to like? ..... Mojomogoz that was rhetorical ;)
Interesting times.
I've looked at the new Debenhams website several times and so far I've been disappointed but it does seem to be improving.
Pricing and discounting on the website is confusing and off-putting. If you view the same item on Debenhams and Karen Millen for instance, then Karen Millen appears to have it cheaper. But if you put the item in your basket then Debenhams apply a discount and it ends up being the same price. I think this is just unnecessarily confusing for shoppers who are going to check the Karen Millen price if they have any sense.
Pricing on the Beauty products doesn't seem competitive. For instance CK Eternity For Men Eau de Toilette 100ml is £60 at Debenhams, but £40 at Boots and even cheaper elsewhere.
Some things do seem to have improved, I didn't see Details and Care information on garments before, but it is there now. Also I think the homepage looks better now, previously it had the Boohoo brands all over it, but now it seems more like a separate Debenhams site although all the Boohoo brands are still available.
I’ve been watching it regularly, it is developing at scintillating speed, so there will be bumps and inconsistencies along the road...but from what I’ve seen to date, not for long.
By the time we get to September and the build up towards Christmas, I suspect that Debenhams will be both vast and impressive.
Regarding headless front end: Separating the product and order management from any customer-facing frontend.
In other words, making sure your key e-commerce data is decoupled from a single frontend touchpoint so that it can be displayed on any frontend touchpoint. An ambitious headless e-commerce project could be pushing product data anywhere: social, mobile, IoT, POS, smart screens, etc. (omnichannel).
Nicked from the internet, I didn't have a clue either! It does sound like a great idea though.
Like most of us, I think these results are well north of decent but I am a little perplexed as to why the SP has dropped. Could it be some larger ESG type funds are using the good news to have a clear out? I can not believe its PIs doing this but maybe I am wrong. Maybe there is some futures exposure coming into play?
One of my key guidelines is to by a good company on bad news - this has served me very well in the past - as an example Greggs springs to mind.
Buying a good company on good news goes against the grain a bit - but today I've decided to compromise and have added to my BOO holding. If the share price drops further I will be buying more.
Boohoo (LON:BOO) have not yet disclosed revenue by brand (these come in the Annual Report, due in a few weeks time). But by my estimates, each of the boohoo and Pretty Little Thing brands alone could do £1bn of revenue in this financial year. If each brand alone was listed on an index like Nasdaq, I wonder what those companies would be valued at? London-based Farfetch is valued at 10x revenue on Nasdaq (I recognize that Farfetch is a fashion platform rather than a brand but the growth profile is very similar) . If the Boohoo management team can successfully scale their other brands then it looks to me like there is a lot of upside to go for with a current market cap of c£4bn.
More weakness and therefore bought more at 317. Now nearly 27% of my portfolio.
Amazing, unanimous positive comments so far. Very helpful! Mirrors the ADVFN and LSE boards.
I’m amazed you bother with the cesspool that is the Boo ADVFN thread.
I popped on there the other day and it one of the worst BB's I've come across - exactly the kind of place that gives BB's a bad name.
It's as though a dozen lunatics (and BOO holders) all escaped from the asylum at the same time and then devoted their waking hours to bombarding each other with absurd posts.
A question and not a view:
Isn't the UK growth a bit disappointing given the expansion of brands with strong history and name recognition in the UK? (Pre Debs as obvs no time for that) And then perhaps a more clear negative is the guidance. Yes they under guide but with so many acquired brands shouldn't this be additive rather continuative otherwise what is the rational to the plethora of acquisitions?
Relative to spectacular history Europe and UK growth look soggy (the latter assuming my comment in prior paragraph holds...and I may be being unkind on the former as covid lockdowns perhaps more impactful than in UK?). US obviously fantastic...
...but all the UK centric acquisitions and re-positioning means the biz has clearly signalled a very UK focus for the foreseeable future and strategic growth plans. This is dissonant with a view of continued rapid growth of the traditional boo model. Given US growth rates isn't it sensible to assume that guidance is assuming stodgy UK growth and maybe Europe too...are they approaching a limit to the growth trajectory in these markets with the old model?
Doubling down in the US looks optimal but given valuation and revenue mix to signal such a US centric main strategy as that is where the clearer blue sky is would likely cause trouble for share price in the short term as UK and Europe growth repriced.
Questions rather than views. Partly built on this prior scepticism -> https://www.stockopedia.com/co...
mojomogoz
Ref brands I think they paid pretty much pennies for these brands (ok 55 mill isnt pennies but it is a household brand) and i suspect it will take time to get these back up to speed - but who knows.
Should we be expecting higher growth ? and are these new brands masking somhwhat a decline in growth rates elsewhere in the group - unknown but its not unreasonable to say the new brands will be flattering the topline numbers - that is a given.
All i know is that in the round the growth over the last 12/24 months and future expectations of 25%+ compounded is enough for me to have bought back in recently despite having previously sold out at much lower levels. At least the minority interets worries are put to bed and other issues somewhat sorted.
I think there is a reasonably clear route to 20p EPS and that level of earnings in the future underpins the shareprice where we are - i somewhat see Boohoo as a slightly defensive play in some respects which some may seem strange to some ? due to the current pe here -at the 20p EPS point they would certainly be deemed to have good competitive advantages due to thie size and proven delivery ref the plan - if growth eventually moderates and they are chucking off buckets of freecashflow thats no biggie I suspect the fact that the shareprice has levelled out does confirm your suspisions that the market is not 100% convinced they will will continue to grow at 30%+ pa year on year over the next 5 years and that actual lfl growth in some markets will be stodgy. Hopefully though they will continue to quiety deliver strong numbers on an ongoing basis and that will deliver decent returns ref the shareprice. They have plenty of potential for future acquisitions/expansions to keep the numbers trending in the right direction too.
Hi rmillaree
My scepticism is probably misplaced. There is much that is super impressive about boo. But with my tainted vision I can't help feel that UK centric acquisitions and new strategy (particularly re Debs) indicates a business that is undergoing a significant transition. I view this as a risk as well as an opportunity and have a somewhat simplistic perspective that the sp on transition will tend to j-curve even if successful (ie down before up). Of course, boo is not UK only so strong international growth can cushion UK transition.
Guided 25% revenue growth with 5% from acquisitions is sort of saying established business is levelling off somewhat? Guiding for H2 sales growth due to covid comparison is also a little hint of maturing (not slow, but maturing relative to boo spectacular history). If one were super cynical could read that as a bit of a cautioning from mgt.
The better message given high valuation and expectations would be to say they were growing the core business globally as the the scope for growth is very high. There current message is that they need to work harder to maintain growth -> again risk.
At the moment boo is the wrong price for the risk for me but I am perhaps more conservative or contrary than some investors (I do have highly rated things tho).
This is not a forecast but a company going through a maturing transition like boo always risks some disappointment short term even if the long term works out. Throw in the covid comparison YoY and uncertainty re how trading comes out once lockdown over for online biz then I see a downside risk. Highly rated stocks are reflexive and a little disappointment compounds thro outsized disappointment in price as narratives inflect.
Thoughts not forecasts. If I'm lucky I might get a look in at boo at either a lower price or around current but with a more proven UK transition under its belt and evidence that the ambitious Debs plans are executable
'Guided 25% revenue growth with 5% from acquisitions is sort of saying established business is levelling off somewhat? Guiding for H2 sales growth due to covid comparison is also a little hint of maturing (not slow, but maturing relative to boo spectacular history). If one were super cynical could read that as a bit of a cautioning from mgt.'
I agree with what you're saying and I did get that sentiment from the outlook blurb but they've guided 25% at the start of every FY for the last 5/6 years (inclusive of inorganic growth). I would be very surprised if it is not substantially upgraded in the next trading update due to partyware sales ramping back up (alluded to by Paul above). Yes retailers will discount heavily on the high-street but I can't see anyone getting close to the sheer range available online. Range to me is the key thing here as every outfit the target demographic (both male and female) wears is posted on social media and there is pressure to A) not wear the same thing twice and B) not wear exactly the same thing as your friends are/ have posting on social media.
Also does anyone have a link for the webcast - I can't seem to locate one. Perhaps they haven't uploaded it yet.
From the RNS:
Investor and analyst presentation
A webcast for analysts will be held today commencing 9.00am (UK time). To access please click the link below:
https://webcasting.buchanan.uk.com/broadcast/608837210386285386ccb8d9
A replay will subsequently be available on the boohooplc.com website from 12 noon via the same link.
Regards
Michael
Sorry link not working.
Hi WhaleHQ, you are very likely correct re guidance. But mix and profitable old rather developmental new trends will be interesting.
Hello Mojomogoz. I take your point about UK-centric. However, having watched the webinar this morning- and Im not sure the webinar is on the website after that, but the presentation is - I feel that they didn't choose this path. It fell into their lap so to speak.
First, nobody asked Debenhams to collapse but it did. Up came the opportunities and in stepped Boohoo (LON:BOO) and others....and IMHO what an opportunity it is going to be. A galleria on the internet.
However, one chart shown in the webinar and I hope it is on the website was a very telling one about the journey that the company is looking at for all brands, ignoring the Debenhams Department Store for the moment. It showed where the company was headed with each of its brands, those acquired in 2019 like Karen Millen and those more recently in 2020/ Karen Millen was at the right hand side of the graph with International Development and to the far left the newly acquired brands with Integration or something similar.
Also re UK-centric again, it happens that during C19 and post Brexit proper, distribution availability and costs for longer distance markets have been rising and this has hit those markets. Not planned, but sometimes you have to roll with the punches.
The US market is very much a target, and that cannot be regarded as UK-centric. Also I think there was some mention f the EU being similar in population to the US, so again the future opportunities lie there too, when things settle down.
Perhaps I have misread where they are going but that is my 2 penny worth.
Kind regards
I am probably getting hugely off-topic here, but actually MyCashley asked Debenhams to collapse and he even gave them a push. Unfortunately (for him) when they toppled, they failed to fall in to his lap.
I may well be wrong but I just do not get this at all. Debenhams was a brand and the brand value was predominantly linked to the 'high street' presence. For sure the Debs website may now be a lot slicker than it was, but personally I think that the number of former Debs customers who feel they are still dealing with Debs (or someone better) will be vanishingly small.
Same for he other acquired brands; I strongly suspect that the cost of converting these customers to Boo will be substantially higher than the cost of acquiring new customers from scratch.
Personally I think the acquisition of these brands was classic management over-confidence. It may be that the underlying BOO businesses are strong enough to pull them through this, but frankly I think they bought "assets" that they are not positioned to monetise.
“I may well be wrong but I just do not get this at all. Debenhams was a brand and the brand value was predominantly linked to the 'high street' presence.“
Ok let’s do a test here - the stats for Debenhams Linked below seem pretty encouraging if we compare these stats to say sosandar with £42 million market cap it seems to blow sosandar out of the water - am I missing something here gromley? To me the split between stores and online is non relevant as long as the online numbers are enough then that’s proof that the website brand can stand on its own two feet - I would concede it is a gamble as these numbers could dwindle and die when stores close but I would have thought these odds are well below 50%
https://www.similarweb.com/website/debenhams.com/
It's a brand with a strong online presence. Needs building rather than getting going, so lower effort and cost. Some of the other brands they've bought do need more work to establish online, but they appear to have made a fine start with Karen Millen in the US. And feeding them into Debenhams ought to be mutually beneficial.
I agree there are associated risks, but it's a scalar opportunity and such opportunities come around very rarely.
Gromley, I don't know the answer...but I feel the move for Debs and other UK brands is somewhat dissonant and could prove a signal. Simply put, the best thing mgt could have done was continued their focused boo-centric very rapid UK and international growth. Why get embroiled in flotsam? Maybe as you say its over-reach. But I think its more likely to reflect a feeling they where getting towards the end of the road in terms of old growth model and/or facing competition. See Zalando comment made by someone below. I've long had the (simple and dumb) view that expansion through Europe could be tricky to scale as there is a need a for local 'feel' (an inexplicable local intangible that is true from clothes to cars to sausages...even though all are basically the same across countries).
It could be genius and I don't manage/start-up retail operations and develop their brands so could be missing it. But it might be mid to longer term corporate good rather than near term where it could leave a lot of things to sort out and through.
I note that these changes come after Jon Little took the reigns...with hindsight and in reflection of these 'strategy changes' Little's appointment was perhaps the signal that boo had reached the end of a road...
I feel hopeful that I get to assess where the very impressive boo are at in future at a lower price
"I strongly suspect that the cost of converting these customers to Boo will be substantially higher"
But that's not the Boohoo strategy. They're not shutting down the acquired brands, and trying to migrate the customers over to Boohoo.
They're revitalising and investing in those brands, and pivoting them to be online only. Completely replumbing the back-end, operations, and logistics.
Hi ridavies, I partly responded to some of your points in response post to Gromley comments.
I'm not a boo expert. I did watch the presentation too. I'm a little bemused by the idea that boo want to go from fast fashion for those most engaged and hungry for it....to selling flower pots online for old folks ;)
I feel its a little odd. Why take this risk rather than push your past success further up the supposed mountain ahead of it? As I've said before, its like they've decided they're going to go toe-to-toe with Next (LON:NXT) ....I can't help think that's premature and a bad idea.
I think its the Brexit effect - why buy quality clothing when you locked indoors? Its definitely one to watch in the next update as we start opening up again.
One thing to note from the Boohoo (LON:BOO) results is the European performance in the context of Brexit. I have been worried about this because of their lack of European warehouse likely raising both costs (which they note today) and delivery times given new custom rules. By comparing the final results with their 10 months to 31 Dec trading updates we can see that in the final two months (i.e. Jan and Feb 2021) they made an extra £40m from Europe - last year that was £31m so that's c.30% growth which is pretty decent still. Although I would still like to see them address the European warehousing issue.
The US growth is exciting.
Yes, IMHO, it is bizarre that Boohoo (LON:BOO) do not have warehousing in Europe and the US both to facilitate returns and to avoid/reduce tariffs. It would be interesting to hear a convincing argument why this is not happening when there is significant planned spend on warehousing in the UK.
They have previously stated it doesn’t give them much, if any advantage. Now that might have changed in terms of customs arrangements for Europe with Brexit.
Because the US is so vast, customers there are used to 2-3 day delivery times. The major markets in Europe can be shipped next day, and once international travel starts again air freight costs to Europe should come back down.
The vast majority of parcels to the EU from UK used to go by road - air is too expensive for anything but super-express delivery services via dedicated courier contracts (and also surprisingly slow too for general cargo!). Unfortunately the barriers Brexit has put in the way mean that cross-border from UK to EU will never be as competitive as it once was. If anyone could do it, Amazon could, and their pan-EU FBA fulfilment no longer includes the UK, and it won't come back.
I would imagine BOO are looking at European options but that's a crowded trade right now with many British businesses looking for a solution,
Thanks Paul for the speedy delivery. As always you deliver quality at speed!!
Thanks Paul, this has saved me a whole lot of work!
Thx for starting this thread Paul.
For me the most important line in the premiums that I have read so far is:
“USA
The group’s highest territorial growth rates have been seen in the USA, as the brands’ momentum builds and market share increases. PrettyLittleThing, Karen Millen and boohooMAN continued their exceptional growth, whilst boohoo and NastyGal grew strongly too. With all brands supported by the success of social media outreach and the compelling customer proposition, group USA revenue increased by 65% to £435.1 million. Return rates have also been significantly lower than in the previous year.”
A 65% increase in sales in very impressive all be it in the context of, for the states, a very small base. This echos the increases in turnover that Boohoo (LON:BOO) saw in the early days when sales increased 40% 51% 96% in 2016 2017 and 2018 respectively.
All in all very happy with the results in my largest holding at 12.2% of portfolio.
Regards
Michael
zeus capital have 2023 EPS forecast at 15.31p
I see the broker forecasts on Stockopedia suggest 29% sales growth in 2022. Perhaps the 25% from Boohoo (LON:BOO) is just management caution. Obviously reality has been a let better historically than 25% sales growth p.a.
I think they also started last year with 25% sales growth expectations and ended up with 41% growth. Definitely time for sales expectations to be increased as we go through the year.
Yes, that 25% ambition was set pre-COVID.
And as we know, almost every online company has outperformed.
Boohoo (LON:BOO)
Ok very simple company here with regard to the numbers , all we really need to look at is the expected sales growth.
So we have nice simple 25% pa growth expected at present going forward numbers like that are enough to keep me invested. Pretty simples. Nice to see they don’t expect significant headwinds ref the exit from lockdown - we could perhaps of expected a % of customers to return back to shopping in the stores - that doesn’t seem to be an issue particularly.
Boohoo (LON:BOO)
Morning Paul - results just out and to my untrained eye appear excellent but await your expert analysis. I appreciate from newspaper coverage etc, they were expected to be good so I have been somewhat surprised to see the share price drift south in the last week or so. I assume this is the Market Makers again up to their usual tricks which I find very irritating and it appears to me that as I follow a lot of stocks that certain ones seem to be subject to manipulation/movement on a regular basis Boohoo being one of them. A further buying opportunity for this one at this level maybe though, should open higher though I would have thought.
Agreed. Excellent results IMO. Alot of increases in costs, staff and other expenses though such as air freight. But, to me they are negligible & natural increases which will ease. My perception is that the acquired brands should be continued to be integrated, its key, their strategy in doing that. Looks a winner but still waiting some more stories from disgruntled ex suppliers or ex supplier employees that the QC Levenson has said some have been struck off the supplier list for not adopting certain ESG changes.