Bumper harvests boost this rural transport company

The name Lindsay has long been associated with transport and logistics in Australia. If you spend much time on country roads, you are probably familiar with the distinctive red and white trucks of Lindsay Australia (ASX:LAU). Not to be confused with the red and yellow trucks of Linfox founded by the other well known Lindsay of logistics, Lindsay Fox.
Brothers Tom and the late Peter Lindsay founded Lindsay Australia in 1953 when they bought three trucks and started transporting produce around the Coffs Harbour area. Michael Lindsay started with the firm in 1974 and in 1983 founded Lindsay Rural. Since 2002 he has been Managing Director and CEO. He retains a significant stake in the business, alongside Tom, as shown below in the Major Shareholders table available under the Accounts tab.

Investment firm Washington H Soul Pattison and Company own a 19% stake. When investing in small cap companies it is important to review the Major shareholders table to get an idea of how much of the stock is tied up with strategic holders and how much is available to be freely traded on the market (also known as the free float). It is also good to know the size of a founder’s holdings. A founder CEO with a substantial holding is likely to have well aligned incentives with other shareholders.
Consistent with their origins, Lindsay Australia is focused on the agriculture and rural sectors. They derived 72% of last year's revenue from transport and 22% from rural services. Rural services is a network of outlets that sell rural supplies with a particular focus on the horticultural industry. They also have an operation in the Brisbane markets providing fumigation, ripening, quarantine, and export and import services.
Their competitive advantages include their expertise in fresh food logistics, and their integrated road and rail services. They also provide a lot of refrigerated transport by both road and rail. The last year has seen considerable investment into their rail capabilities. They have added over 100 refrigerated rail containers recently and now have a fleet of over 400 rail containers, most of them refrigerated. The chart below shows how this investment has been driving revenue growth.
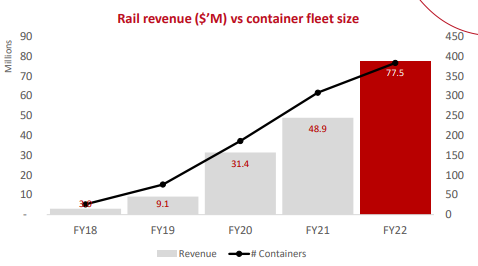
Source: LAU FY22 Results presentation, 17/8/2022
This combination of rail and road transport helped them to reduce the impact on the business from the flooding that has deluged the eastern states over the last two years.
Despite the floods, Australian farms have been producing record harvests. This helped to boost revenues by 27% last year and underlying net profits before tax by 94%. The StockRank(™) has held steady in the top quartile for the last five years, but received a real boost from the growth of the last year, taking it to 99. As can be seen, it is very strong in all three components.
Of course they have not been immune to the challenges on the cost side as rising inflation, staff shortages and COVID impacts added pressure to the bottom line. As they provide an essential service, the transportation of food, they were able to keep operating during the various lockdowns, however like most businesses they had to deal with high absenteeism due to people catching COVID or being close contacts.
In addition to the investment in rail, they continue to expand their road fleet and add higher capacity trucks in response to the high levels of demand. This demand should continue at least in the short term, with strong harvests forecast again in the coming seasons.
They have also been adding additional centres to their rural supplies network, in key horticultural areas and additional sales staff, resulting in strong growth in sales and profits for this division.

Source: LAU FY22 Results presentation, 17/8/2022
Profit, when measured as EBITDA has been growing steadily in both divisions over the last 5 years. The transport division accounts for 86% of profits on this measure. This shrinks to 79% after depreciation is taken into account due to the higher depreciation expenses associated with transport. However, this is still higher than the 72% when measured at the revenue line.
Margins in rural services were impacted in the prior year due to the need to build up higher inventory levels to compensate for supply chain disruptions, especially with imported goods and the increased freight costs. Revenue in this division grew by 14% while EBITDA grew at 26%. Growth rates in the transport business were notably higher.
The reported net profit after tax tends to move around a bit, due to temporary impacts of tax credits and some other one-off expenses such as the costs associated with the Brisbane floods.
The balance sheet is strong. The net leverage ratio has been declining. There is over $100 million in equipment loans, but these are secured against the equipment.
The stock is paying a healthy dividend yield of about 5% based on last year’s dividends. The dividends were unfranked and they are forecast to remain unfranked until 2024. This is due to the Federal Government’s temporary accelerated depreciation initiative which resulted in the group not having to pay any tax. Companies can only pay franked dividends when tax has been paid on the profits.
The share price has almost doubled since June, but despite this, the stock is still only trading on a historical PE ratio of about 10. There are only two market analysts covering the stock and they both rate it as a buy.
The sector is a competitive one and there are also a lot of factors outside the firm’s control, such as adverse weather and COVID impacts. This can make short-term forecasting difficult but when viewed over a multi decade horizon, the business has continued to grow. With the continued investment in efficiency and capacity, as well as the expected bumper harvests, the business may well keep on truckin.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
5 comments
Not a great scenario but you would think Lindsay Australia (ASX:LAU) will benefit from the liquidation of Scott's Transportation, who were the major player in cold-chain logistics and serviced all the major supermarkets. Administrator's tried for a business sale, but no takers and now they will sell off Scott's assets. Over interests to all is probably Scott's rail containers and their 20+ cold DC's. LAU may pick up extra contracts and cheap assets.
Yes. Good point. The high quality ranking LAU is generating strong revenue growth while a competitor is going broke. It will be interesting to see if they can pick up some of the assets.
LAU was added to the All Ordinaries Index today.
Much appreciated. Comprehensive analysis as always. thank you
Thanks Sagie. Glad you found it interesting